Category: entrepreneurship

  • Business Start-up Process: full 18-period Senior 1 guide

    Business Start-up Process: full 18-period Senior 1 guide

    The Business Start-up Process is Senior 1 Topic 4 in Uganda’s lower secondary Entrepreneurship syllabus, taught across 18 periods in Term 3. It takes learners through the steps in starting a business, the sources of business finance, savings and investments, and how to choose a business location. This guide breaks down every learning outcome, activity and assessment so a teacher can plan the whole unit.

    • 18 periods in Term 3 — Topic 4 sits under the Start-up Process theme.
    • Four sub-topics — Steps in Starting a Business (4), Sources of Business Finance (5), Savings and Investments (5), Location of a Business (4).
    • One competency — the learner follows the steps in starting a business, saves money and invests in a profitable venture.
    • 72 periods — the full Senior 1 Entrepreneurship year, with Topic 4 as its Term 3 centrepiece.
    • Three-column layout — learning outcomes, suggested activities and sample assessment for every sub-topic.

    What is the Business Start-up Process in Senior 1?

    The Business Start-up Process is the fourth topic in the Senior 1 Entrepreneurship syllabus, allocated 18 periods in Term 3 under the theme “Start-up Process”. It teaches learners how a new venture is born: the steps to follow, where start-up money comes from, how savings and investments work, and how to pick a business location.

    This topic closes the Senior 1 year. It follows Topic 3, Business Ideas and Opportunities, where learners have already generated ideas and run a market survey, so Topic 4 is the natural next step — turning a selected opportunity into a real, funded and well-located business.

    Topic 4 is not the whole of Term 3. It is followed by Topic 5, Introduction to Government Revenue, which runs for six periods. Together the two topics complete the 72-period Senior 1 year set out in the programme planner.

    TermThemeTopicPeriods
    Term 1Creating an Entrepreneurial AwarenessIntroduction to Entrepreneurship Education24
    Term 2Scanning the EnvironmentBusinesses in Uganda12
    Term 2Scanning the EnvironmentBusiness Ideas and Business Opportunities12
    Term 3Start-up ProcessBusiness Start-up Process18
    Term 3Start-up ProcessIntroduction to Government Revenue6
    Total72
    Table 1: The Senior 1 Entrepreneurship programme planner, showing Topic 4 in Term 3.

    This guide is published by Remedial Corner, a Ugandan inclusive-education and revision platform. The period counts, sub-topic names, competency and learning outcomes below come from the official lower secondary Entrepreneurship syllabus, and the NCDC Curriculum Framework is the governing document for that curriculum.

    What competency does Topic 4 build?

    The competency for the Business Start-up Process states that the learner follows the steps involved in starting a business, saves money and invests in a profitable venture. Every learning outcome in the four sub-topics feeds this one sentence, so assessment always returns to whether the learner can act on it.

    The learner follows the steps involved in starting a business, saves money and invests in a profitable venture.

    The competency has three parts, and they match the sub-topics in order. “Follows the steps involved in starting a business” belongs to sub-topic 4.1. “Saves money” and “invests in a profitable venture” belong to 4.3, Savings and Investments. Sub-topics 4.2 on finance and 4.4 on location support the first and third parts.

    Because the competency is the anchor, a teacher writes every lesson objective from it first. The syllabus then lists the learning outcomes that show, in measurable terms, what following the steps or investing in a profitable venture actually means for a Senior 1 learner.

    How do the four sub-topics build on one another?

    The four sub-topics run in a logical chain. Learners first master the steps in starting a business (4 periods), then study where the money comes from in Sources of Business Finance (5 periods), then turn to Savings and Investments (5 periods), and finally choose a Location (4 periods). Each stage feeds the next.

    1. Steps in Starting a Business (4 periods) — plan the venture and set its budget.
    2. Sources of Business Finance (5 periods) — find and weigh the money.
    3. Savings and Investments (5 periods) — build and grow the money.
    4. Location of a Business (4 periods) — place the venture.
    Sub-topicTitlePeriods
    4.1Steps in Starting a Business4
    4.2Sources of Business Finance5
    4.3Savings and Investments5
    4.4Location of a Business4
    Total18
    Table 2: Topic 4 sub-topics and their period allocations, totalling 18.

    The sequence mirrors how a real founder thinks. You cannot finance what you have not planned (4.1 to 4.2), you cannot invest savings you have not understood (4.2 to 4.3), and you cannot locate a venture you have not decided to fund (4.3 to 4.4).

    One source file labels the three later sub-topics under “Topic 5” instead of “Topic 4”, but the competency line and the 18-period total confirm they all belong to the Business Start-up Process. Teachers should read “Topic 5” as a print error, since the sub-topic numbers read 4.3 and 4.4.

    Overview of the four Senior 1 Topic 4 sub-topics across 18 periods in Term 3
    The 18-period unit in one view: four sub-topics that move a learner from the steps in starting a business to choosing a location.

    4.1 Steps in Starting a Business (4 periods)

    Steps in Starting a Business opens Topic 4 with four periods. It is where the learner first moves from an idea to a plan, covering the enabling factors, the correct sequence of steps, basic record keeping and the preparation of a budget.

    What are the learning outcomes in Steps in Starting a Business?

    Sub-topic 4.1 sets three learning outcomes. Learners know the factors that enable a person to start up a business, including basic principles of effective record keeping; they follow the correct steps in starting a business that lead to a business plan; and they prepare a budget, recognising its value to business development.

    • Know the factors that enable an individual to start up a business, including some basic principles of effective record keeping (k).
    • Follow the correct steps in starting a business which will eventually lead to developing a business plan (k, s).
    • Prepare a budget, recognising its value to business development (u, s, gs).

    What learning activities does Steps in Starting a Business suggest?

    Learners brainstorm the factors that enhance start-ups and explain why each matters. They listen to a presentation from a community entrepreneur on how that person began, then prepare and ask questions. In groups they summarise the steps in starting a business and share them, including how to prepare a budget from sample formats.

    • Brainstorm the factors that enhance business start-ups and explain why they are important.
    • Listen to a community entrepreneur explain how they started, then prepare and ask questions.
    • In groups, summarise the steps in starting a business and share them with the class.
    • Learn how to prepare a budget from useful budget formats and strategies.

    How is Steps in Starting a Business assessed?

    Assessment has learners share opinions and experiences on good strategies for starting a new business, with the teacher evaluating how well they identify key features of success. Learners also produce a written group report describing important aspects of the entrepreneur’s presentation, showing they can capture the essential points.

    • In conversation, evaluate how learners identify key features of success when sharing start-up strategies.
    • Assess a written group report on the entrepreneur’s presentation for how well it captures important features.

    4.2 Sources of Business Finance (5 periods)

    Sources of Business Finance follows with five periods. Here learners meet the different places a new business can get money, and — just as importantly — weigh the benefits and challenges of each so they can judge which source fits which venture.

    What are the learning outcomes in Sources of Business Finance?

    Sub-topic 4.2 sets two learning outcomes. Learners know the different sources of business finance, and they assess the benefits and challenges of each source. This pairing means they do not just list sources; they must weigh each one, which builds the judgement a real founder needs before borrowing or seeking capital.

    • Know the different sources of business finance (k).
    • Assess the benefits and challenges of each source of business finance (s, u, v, gs).

    What learning activities does Sources of Business Finance suggest?

    Learners discuss the sources of business finance in groups and justify why these sources are a starting point. They read case studies on the benefits and challenges of each source, discussing similarities and differences. In groups they then explore each source’s challenge and benefit and agree reasons for their responses.

    • Discuss the sources of business finance and justify why they are a starting point.
    • Read case studies on the benefits and challenges of each source and discuss similarities and differences.
    • Explore and identify each source’s challenge and benefit, agreeing reasons for responses.

    How is Sources of Business Finance assessed?

    Learners write a case study describing a business person in their community, illustrating the source of that person’s funds, the benefits of that source and its challenges. In conversation, the teacher assesses how well learners understand the effects of how businesses are funded — not just the labels.

    • Write a case study of a local business person showing the source, benefits and challenges of their funds.
    • In conversation, assess understanding of how businesses are funded.

    4.3 Savings and Investments (5 periods)

    Savings and Investments is the most practical of the four. Learners move from studying money to managing it: defining saving and investment, understanding their forms and purposes, and building a personal savings plan.

    What are the learning outcomes in Savings and Investments?

    Sub-topic 4.3 sets four learning outcomes. Learners know the factors that determine saving and investment, appreciate the reasons for and forms of saving, understand how to prepare a savings plan using spreadsheets, books and calculators, and know the factors to consider before taking an investment decision.

    • Know the factors that determine saving and investment (u, s, gs).
    • Appreciate the reasons for and forms of saving (k, v).
    • Understand how to prepare a savings plan, including how spreadsheets, books and calculators are used (u, s, gs).
    • Know factors to consider before taking an investment decision (k, u).

    What learning activities does Savings and Investments suggest?

    Learners first agree definitions for saving and investment as a class, then investigate the purpose and forms of each in groups. They agree a general statement on when to save versus when to invest, prepare a personal savings plan, form a savings group or SACCO, and start saving.

    • Agree definitions for saving and investment as a class.
    • Investigate the purpose and forms of saving, and the purpose and forms of investment, in groups.
    • Agree a general statement on when to save and when to invest, with reasons.
    • Prepare a personal savings plan.
    • Form a savings group or SACCO and start saving.
    • Investigate a range of investment plans and agree on one, explaining its benefits.

    How is Savings and Investments assessed?

    Learners write a monthly report on their savings and investment activities, identifying any challenges and considering practical solutions. The teacher observes how well the report is written, weighing the accuracy of the information and the nature of its content rather than just its length.

    • Write a monthly report on savings and investment activities, noting challenges and practical solutions.
    • Observe how well reports are written for accuracy of information and nature of content.

    4.4 Location of a Business (4 periods)

    Location of a Business closes Topic 4 with four periods. It turns learners’ attention outward, to the question of where a venture should sit — and why the wrong location can hold a good idea back.

    What are the learning outcomes in Location of a Business?

    Sub-topic 4.4 sets a single learning outcome: learners know the factors considered for locating a business. Although it is one line, it is dense — it asks learners to connect a chosen location to the type of business and to recognise when a location does not match.

    • Know factors that are considered for locating a business (k, u).

    What learning activities does Location of a Business suggest?

    Learners discuss the factors that influence business location in groups and present them to the class. They study contrasting locations and try to link each to its type of business, explaining cases where a location does not seem to match, then design a guide for entrepreneurs choosing a site.

    • Discuss the factors that influence business location and present them to the class.
    • Discuss contrasting locations and link each chosen location to the type of business.
    • Explain situations where a location does not seem to match the type of business.
    • Design a guide for entrepreneurs selecting a business location.

    How is Location of a Business assessed?

    Learners identify and describe a business in their community and find out the factors that led to its location. The teacher observes how well learners explain their ideas and how relevant those ideas are to business development — linking location back to a real venture.

    • Identify and describe a community business and find the factors behind its location.
    • Observe how well learners explain their ideas and how relevant they are to business development.

    How should a teacher plan the full 18 periods?

    Plan the 18 periods of the Business Start-up Process as a build: four for the steps in starting a business, five for sources of business finance, five for savings and investments, and four for location. Base every lesson on the learning outcomes, use the activities as a guide, and match each assessment to its outcome.

    Sub-topicPeriodsCore focusSample assessment
    4.1 Steps in Starting a Business4Factors, steps, record keeping, budgetConversation plus a written group report
    4.2 Sources of Business Finance5Sources, benefits and challengesA community case study
    4.3 Savings and Investments5Saving versus investing, savings plan, SACCOA monthly savings report
    4.4 Location of a Business4Location factors and site selectionDescribing a community business location
    Table 3: A ready-to-use planning map for the 18-period Business Start-up Process unit.
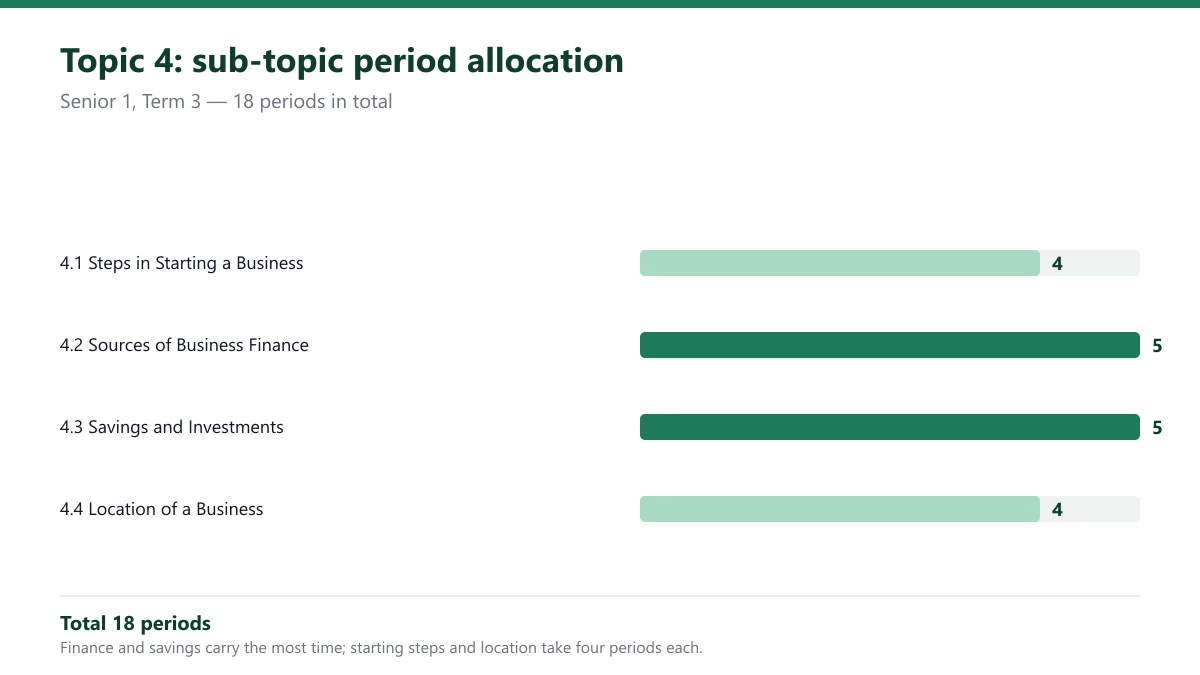
    Bar chart of Topic 4 sub-topic periods: 4, 5, 5 and 4, totalling 18
    Steps in Starting a Business and Location take 4 periods each; Sources of Business Finance and Savings and Investments take 5 each.

    These are not the only possible learning activities, teachers are encouraged to extend these and devise their own that are appropriate to the needs of their class.

    The three columns map onto a lesson in one step. The learning outcomes are the objectives, the suggested activities are the lesson body, and the sample assessment is how you check understanding. Because the activities are guidance, an inclusive classroom can adapt them to mixed abilities.

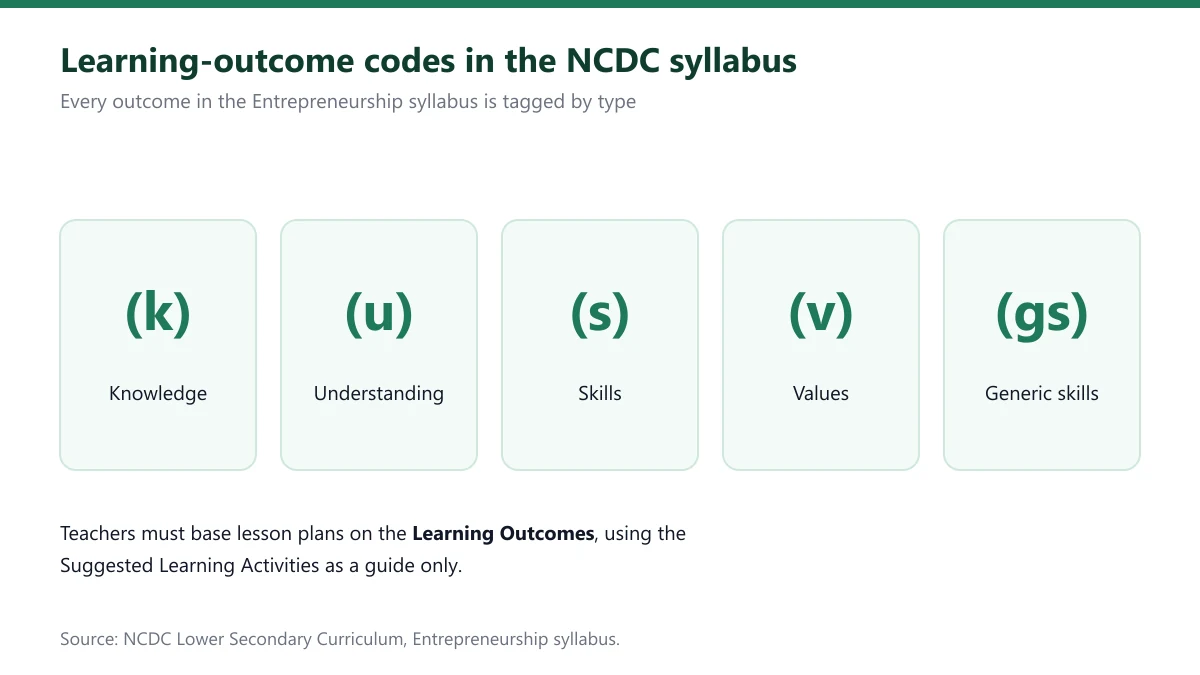
    The codes (k) knowledge, (u) understanding, (s) skills, (v) values and (gs) generic skills tag every outcome, so a teacher can see whether each one targets knowing, doing or valuing. For classroom reading beyond this page, the O-Level Entrepreneurship Education textbook expands on the finance and start-up concepts.

    Frequently asked questions about this Senior 1 unit

    Here are the questions teachers and parents ask most often about Topic 4.

    How many periods is the Business Start-up Process in Senior 1?

    The Business Start-up Process is allocated 18 periods in Senior 1, all taught in Term 3 under the theme Start-up Process. The 18 periods split across four sub-topics, and they sit alongside Introduction to Government Revenue, which adds six more periods to close the 72-period Senior 1 year.

    What is the competency for Topic 4?

    The competency states that the learner follows the steps involved in starting a business, saves money and invests in a profitable venture. Every learning outcome in the four sub-topics feeds this sentence, so a teacher writes lesson objectives from it and returns to it when assessing each sub-topic.

    What are the four sub-topics of Topic 4?

    The four sub-topics are Steps in Starting a Business (4 periods), Sources of Business Finance (5 periods), Savings and Investments (5 periods), and Location of a Business (4 periods). Together they total 18 periods and run in that order, each one building on the one before it.

    How many periods is the whole Senior 1 Entrepreneurship year?

    Senior 1 Entrepreneurship runs for 72 periods in total. Term 1 carries Introduction to Entrepreneurship Education (24 periods), Term 2 carries Businesses in Uganda and Business Ideas and Opportunities (12 each), and Term 3 carries Topic 4 (18) and Introduction to Government Revenue (6).

    What topic follows Topic 4 in Senior 1?

    Introduction to Government Revenue follows Topic 4, running for six periods to close Term 3. It covers what government revenue is, why the government needs it, and the sources of government revenue. The two topics together complete the Senior 1 year of 72 periods.

    For the next step up the ladder, read the Senior 3 Entrepreneurship syllabus breakdown, where Topic 11 turns the steps taught here into a full business plan. Browse the Remedial Corner blog for more subject guides, and read about Remedial Corner to meet the team behind these notes.

    Sources and further reading

    The sources behind this article, and where to read further.

  • Senior 4 Entrepreneurship topics: full topic breakdown

    Senior 4 Entrepreneurship topics: full topic breakdown

    The Senior 4 Entrepreneurship topics span three units across 136 periods: Insurance in Term 1, International Trade in Term 2, and Tax Compliance in Term 3. All three sit under the Business Support theme and are set by Uganda’s National Curriculum Development Centre (NCDC). This breakdown lists every sub-topic, its period count, its competency and its learning outcomes.

    • 136 periods total — 48 in Term 1, 48 in Term 2 and 40 in Term 3.
    • Three topics — Topic 13 Insurance, Topic 14 International Trade and Topic 15 Tax Compliance.
    • Eight sub-topics — four under Insurance, two under International Trade and two under Tax Compliance.
    • One theme — Business Support runs through all three terms.
    • Elective subject — four periods a week in Senior 3 and Senior 4.
    • Outcome codes — (k), (u), (s), (v) and (gs) tag every learning outcome.

    What are the Senior 4 Entrepreneurship topics?

    The Senior 4 Entrepreneurship topics are the three final units of Uganda’s O-level Entrepreneurship course: Topic 13 Insurance (48 periods), Topic 14 International Trade (48 periods), and Topic 15 Tax Compliance (40 periods). Together they total 136 periods and complete the lower secondary subject after the Senior 3 topics.

    Senior 4 picks up exactly where the Senior 3 Entrepreneurship syllabus ends. Senior 3 covered Topic 11 Business Planning and Topic 12 Introduction to Principles of Accounting, plus Tax Administration in Uganda. Senior 4 now adds Insurance, International Trade and Tax Compliance under one Business Support theme.

    TopicTitleTermPeriods
    13InsuranceTerm 148
    14International TradeTerm 248
    15Tax ComplianceTerm 340
    Total136
    Table 1: The three Senior 4 topics, their terms and their period allocations.
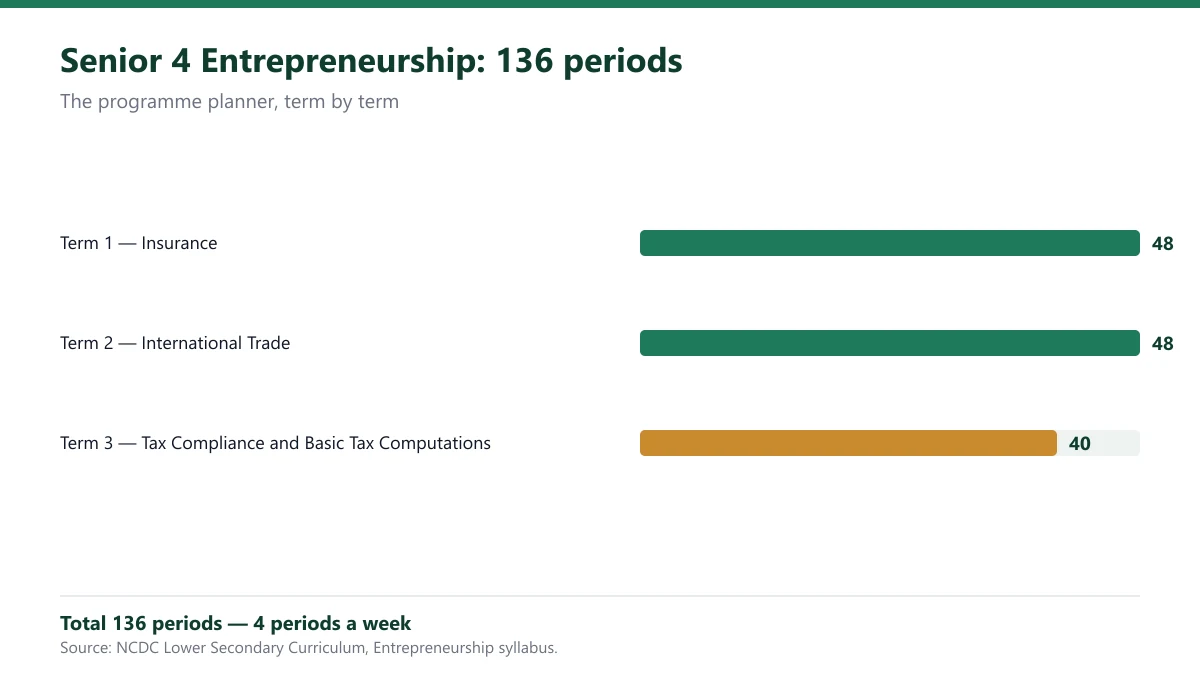
    Term-by-term period allocation for Senior 4 Entrepreneurship: 48, 48 and 40, totalling 136 periods
    The official programme planner: 48 periods for Insurance, 48 for International Trade, and 40 for Tax Compliance in the 136-period Senior 4 year.

    This guide is published by Remedial Corner, a Ugandan inclusive-education and revision platform. The period counts and competencies below follow the NCDC Curriculum Framework, the official source for the lower secondary curriculum.

    How many periods is Senior 4 Entrepreneurship?

    Senior 4 Entrepreneurship is allocated 136 periods in total. The planner splits these as 48 periods for Insurance in Term 1, 48 for International Trade in Term 2, and 40 for Tax Compliance in Term 3, the shortest topic of the year.

    The Senior 4 programme planner sets the year out in three rows, one per term, each carrying the Business Support theme. The table below shows the exact split.

    TermThemeTopicPeriods
    Term 1Business SupportInsurance48
    Term 2Business SupportInternational Trade48
    Term 3Business SupportTax Compliance40
    Total136
    Table 2: The Senior 4 programme planner, showing period allocation by term.

    At four periods a week, the year divides naturally across the three terms. Entrepreneurship is compulsory in Senior 1 and Senior 2, then becomes an elective in Senior 3 and Senior 4, so a learner only studies these topics if they chose the subject.

    The planner prints Term 3 as two rows — Tax Compliance (20 periods) and Basic Tax Computations (20 periods) — but the syllabus groups both as Topic 15. The two 20-period sub-topics simply split the 40-period topic across the term.

    Topic 13: Insurance (Term 1)

    Topic 13 Insurance opens the Senior 4 Entrepreneurship topics in Term 1, running for 48 periods under the Business Support theme. Its competency frames the whole topic, and four sub-topics follow it.

    The learner knows and uses insurance services.

    What are the sub-topics of Insurance?

    Insurance has four sub-topics: 13.1 Terms Used in Insurance (9 periods), 13.2 Principles of Insurance (15 periods), 13.3 Insurance Documents and Process (15 periods), and 13.4 Challenges Facing the Insurance Industry (9 periods). Together they total 48 periods, the whole of Term 1.

    Sub-topicTitlePeriods
    13.1Terms Used in Insurance9
    13.2Principles of Insurance15
    13.3Insurance Documents and Process15
    13.4Challenges Facing the Insurance Industry9
    Total48
    Table 3: Topic 13 Insurance sub-topics and their period allocations.

    13.1 Terms Used in Insurance (9 periods)

    Learners here understand the meaning and importance of insurance, and understand the basic terms used in insurance and the difference between types of insurance. Both outcomes are tagged (u), for understanding. Activities start with the class discussing and agreeing what the term insurance means.

    In pairs, learners tell each other why insurance matters and what they would insure in their own lives and why. They discuss examples where a lack of insurance caused considerable financial difficulty, and the opposite case where paying for insurance became a financial burden. They then identify two businesses in the local community and find out the importance of insurance to those businesses.

    13.2 Principles of Insurance (15 periods)

    Learners appreciate the principles of insurance (u, gs) and understand the types and classes of insurance (k). In groups they research and discuss the principles with guidance from the teacher, then work in pairs to define each principle with an example.

    Small groups think critically about the effects of these principles on the way people live. Finally, each learner completes an assignment on the principles of insurance, which lets the teacher check understanding in writing.

    13.3 Insurance Documents and Process (15 periods)

    Learners know the documents used in insurance (k, u), understand the steps to take up an insurance policy (k), and know the steps taken to settle a claim (k, v). Groups research the documents that carry the key features of the insurance process.

    Each group then considers an insurance they would need to take out, lists the steps and documents involved, and presents the process to the class, explaining the steps for making a claim. Individually, learners write an instruction guide for taking up a policy and settling a claim.

    13.4 Challenges Facing the Insurance Industry (9 periods)

    Learners appreciate the challenges facing the insurance industry (u, gs) and know possible solutions to those challenges (u, s). They interview an insurance broker, asking key questions to identify the challenges and suggest solutions.

    Learners then prepare a summary of their learning about insurance, outlining possible solutions to the challenges the industry faces. Assessment observes how well a written assignment captures the key features of these challenges.

    Topic 14: International Trade (Term 2)

    Topic 14 International Trade runs for 48 periods across Term 2, also under the Business Support theme. Its competency is broader than Insurance: it asks the learner to find and use opportunities on the international market.

    The learner identifies and exploits business opportunities on the international market.

    What are the sub-topics of International Trade?

    International Trade has two sub-topics: 14.1 Introduction to International Trade (24 periods) and 14.2 Regional Cooperation (24 periods). Both run in Term 2 under the Business Support theme, and together they total 48 periods, the same allocation given to Insurance in Term 1.

    Sub-topicTitlePeriods
    14.1Introduction to International Trade24
    14.2Regional Cooperation24
    Total48
    Table 4: Topic 14 International Trade sub-topics and their period allocations.

    14.1 Introduction to International Trade (24 periods)

    This is the longest single sub-topic in the Senior 4 Entrepreneurship syllabus, with eight learning outcomes. They run from understanding what international trade means, through its forms and documents, to the requirements for import and export trade. The outcomes are listed below.

    • understand what is meant by international trade (u)
    • know the forms of international trade, including e-commerce (u, s)
    • understand reasons for international trade and the various challenges it presents (u, s) (k)
    • know International Commercial Terms (INCO terms) (u)
    • understand the documents used in international trade (u)
    • know the commercial tools used to control international trade (k)
    • understand the factors affecting international trade (u, v, s)
    • understand the requirements for export and import trade (k)

    Activities begin with learners brainstorming the meaning and divisions of international trade, then agreeing a class definition. Groups discuss why a country needs international trade and its different forms, then study the commercial terms and their implications. They interpret and prepare international trade documents, and identify the commercial tools used to control trade.

    For assessment, learners identify Uganda’s main imports and exports and produce a table or diagram of them, judging how far the products reflect key aspects of trade in Uganda. They also research changes in international trade over the last ten years and predict what might happen next.

    14.2 Regional Cooperation (24 periods)

    Learners know regional cooperation and give examples (u, gs), appreciate its benefits (u, v, s), and understand its challenges (u, gs). Groups discuss the regional cooperations Uganda belongs to and outline the features of key ones.

    Groups then prepare a summary of the benefits and challenges of regional cooperation, using local and international examples. Learners explore why these cooperations began, linking them to political and economic change, compare them to other kinds of businesses with charts, and present their findings as a radio show or an advert.

    Topic 15: Tax Compliance (Term 3)

    Topic 15 Tax Compliance runs for 40 periods across Term 3, the final term of the lower secondary course. Like the rest of Senior 4 it sits under the Business Support theme, and its competency closes the subject by joining the local and international market to tax rules.

    The learner identifies and exploits business opportunities in the local and international market and complies with tax regulations.

    What are the sub-topics of Tax Compliance?

    Tax Compliance has two sub-topics: 15.1 Tax Compliance (20 periods) and 15.2 Basic Tax Computations (20 periods). Together they total 40 periods in Term 3, the shortest and final of the three Senior 4 topics that close the O-level course.

    Sub-topicTitlePeriods
    15.1Tax Compliance20
    15.2Basic Tax Computations20
    Total40
    Table 5: Topic 15 Tax Compliance sub-topics and their period allocations.

    15.1 Tax Compliance (20 periods)

    This sub-topic carries six learning outcomes, from knowing what tax compliance means to suggesting ways to improve it. Learners also appreciate the factors affecting compliance and weigh its advantages against the disadvantages of non-compliance.

    • know tax compliance (k)
    • appreciate factors affecting tax compliance (u, gs)
    • understand the elements of tax compliance (s, u)
    • know the advantages of tax compliance (u, gs)
    • know the disadvantages of non-tax compliance (u, gs)
    • suggest ways of improving tax compliance (u, s)

    Groups study case studies that illustrate both tax compliance and non-compliance, then sort them by an agreed criterion and justify the sorting with evidence. They agree a definition of tax compliance, identify the factors that affect it in each case, and debate its advantages and disadvantages with another group.

    Learners also agree a list of ways to improve tax compliance and research statements about it on the Internet, then draft their own statement for a local government website. For assessment they produce a strategy for government organisations to respond to non-compliance. The O-Level Entrepreneurship Education textbook expands on this content.

    15.2 Basic Tax Computations (20 periods)

    This sub-topic has a single learning outcome: calculate basic taxes (u, s). Learners are first shown how to calculate basic taxes, then work in groups to calculate four of them.

    • Individual Income tax
    • Corporation tax
    • Rental Income tax
    • VAT

    Learners then research contrasting examples of these taxes and compare the challenges and opportunities each brings to the economy and communities. For assessment, they calculate basic taxes using several business examples and other accounts, with the teacher observing how accurate the calculations are.

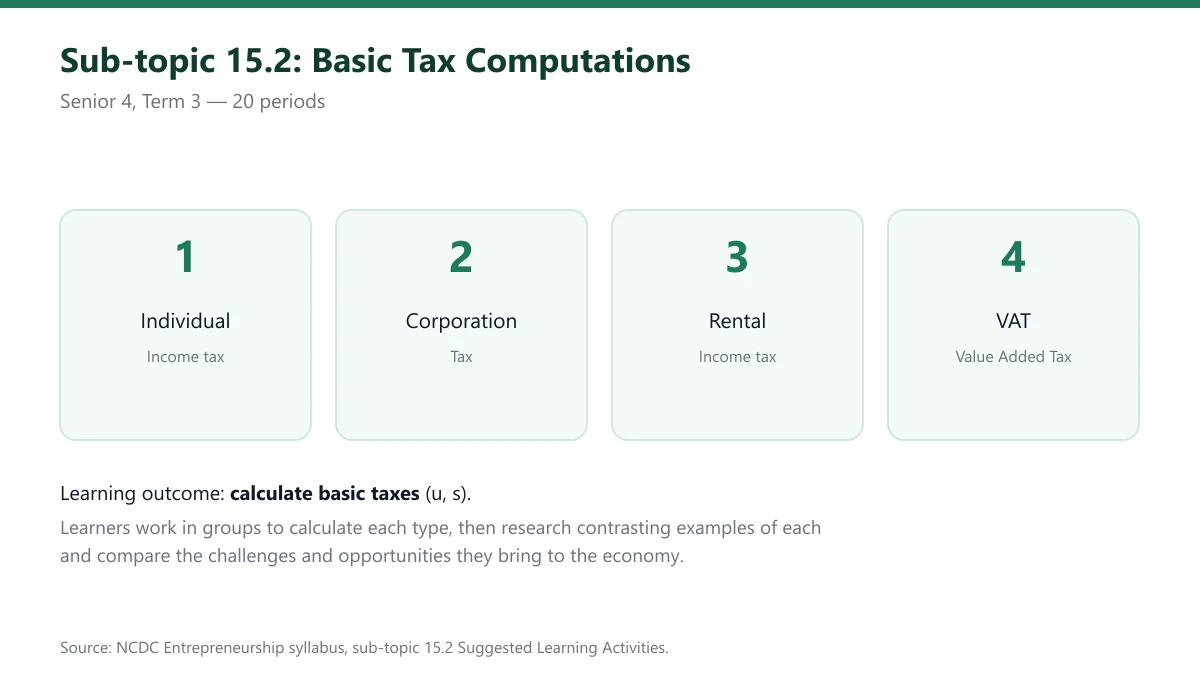
    Four basic taxes calculated in Senior 4: Individual Income tax, Corporation tax, Rental Income tax and VAT
    Topic 15.2 Basic Tax Computations: learners calculate Individual Income tax, Corporation tax, Rental Income tax and VAT.

    What do the learning-outcome codes (k), (u), (s), (v) and (gs) mean?

    The learning-outcome codes tag each learning outcome by type: (k) knowledge, (u) understanding, (s) skills, (v) values, and (gs) generic skills. They appear in parentheses after outcomes so teachers can see at a glance whether an outcome targets knowing, doing or valuing.

    CodeMeaning
    (k)Knowledge
    (u)Understanding
    (s)Skills
    (v)Values
    (gs)Generic skills
    Table 6: The five learning-outcome codes used across the Senior 4 syllabus.

    Because one outcome can carry more than one code, the letters also tell a teacher how to assess it. A knowledge outcome is tested differently from a skills outcome, and a values outcome is observed rather than marked. For example, 13.2 Principles of Insurance tags “appreciate the principles” as (u, gs), while 13.1’s “understand the meaning and importance of insurance” is tagged (u) alone.

    How should teachers use the three-column layout?

    Teachers should base lesson plans on the Learning Outcomes column and treat the Suggested Learning Activities as a guide only. The syllabus states these are not the only possible activities, and encourages teachers to extend them or devise their own to fit the class.

    These are not the only possible learning activities, teachers are encouraged to extend these and devise their own that are appropriate to the needs of their class.

    The three columns map onto a lesson: Learning Outcomes are the objectives, Suggested Learning Activities are ideas for the lesson body, and the Sample Assessment Strategy shows how to check understanding. A teacher planning 15.2 Basic Tax Computations writes the objective from its single outcome, then chooses the four taxes to practise, and finally observes the accuracy of the calculations.

    Because the activities are a guide, a teacher in an inclusive classroom can adapt each one to mixed abilities. A spoken question-and-answer can replace a written test without changing the Learning Outcome, which matters to an inclusive platform like Remedial Corner.

    Frequently asked questions about the Senior 4 topics

    The Senior 4 Entrepreneurship topics run in a fixed order across the year, term by term.

    1. Term 1 — Insurance, 48 periods
    2. Term 2 — International Trade, 48 periods
    3. Term 3 — Tax Compliance, 40 periods

    Is Entrepreneurship compulsory in Senior 4?

    No. Entrepreneurship is compulsory in Senior 1 and Senior 2, and becomes an elective in Senior 3 and Senior 4. A Senior 4 learner studies it for four periods a week, but only if they chose it as one of their electives.

    How many periods a week is Entrepreneurship taught in Senior 4?

    Entrepreneurship is taught for four periods a week in Senior 3 and Senior 4. By comparison, Senior 1 and Senior 2 allocate two periods a week. Across the full year, the Senior 4 timetable totals 136 periods for the subject.

    What are the three Senior 4 Entrepreneurship topics?

    The three Senior 4 Entrepreneurship topics are Topic 13 Insurance (48 periods in Term 1), Topic 14 International Trade (48 periods in Term 2), and Topic 15 Tax Compliance (40 periods in Term 3). Together they total 136 periods under the Business Support theme.

    What is the Insurance competency in Senior 4?

    The Topic 13 competency is: “The learner knows and uses insurance services.” It frames all four sub-topics in Term 1, from the terms and principles of insurance, through the documents and claims process, to the challenges facing the insurance industry.

    What is the International Trade competency in Senior 4?

    The Topic 14 competency is: “The learner identifies and exploits business opportunities on the international market.” It frames both sub-topics across the 48 periods of Term 2, from the meaning and forms of international trade to regional cooperation and its benefits and challenges.

    What taxes do learners calculate in Senior 4?

    In Topic 15.2 Basic Tax Computations, learners calculate four basic taxes: Individual Income tax, Corporation tax, Rental Income tax, and VAT. They practise in groups, then research contrasting examples and compare the challenges and opportunities each tax brings to communities.

    Where can I read the official Senior 4 Entrepreneurship syllabus?

    Uganda’s National Curriculum Development Centre (NCDC) publishes the lower secondary Entrepreneurship syllabus that sets this structure. This page summarises the Senior 4 content in one place — every sub-topic, its exact period count and its outcome codes — so you do not need to search further.

    For more subject breakdowns, browse the Remedial Corner blog, and read about Remedial Corner to meet the team behind these guides.

    Sources and further reading

    The sources behind this article, and where to read further.

  • Senior 2 Entrepreneurship topics: the complete breakdown

    Senior 2 Entrepreneurship topics: the complete breakdown

    Senior 2 Entrepreneurship topics span 72 periods across five topics, from Legal Forms of Business Ownership through Production in Business and Marketing to Money and Financial Institutions and Taxation. The year runs across three terms under two themes. Every sub-topic, period count and learning outcome below comes from the NCDC Entrepreneurship syllabus.

    • 72 periods total — 28 in Term 1, 18 in Term 2 and 26 in Term 3.
    • Five topics — from Legal Forms of Business Ownership to Taxation.
    • Two themes — Business Management (Terms 1 and 2) and Business Support (Term 3).
    • Topic 9 is the longest — Money and Financial Institutions takes 20 periods.
    • Topic 10 is the shortest — Taxation takes 6 periods.
    • Outcome codes (k), (u), (s), (v) and (gs) tag every learning outcome.

    What is Senior Two Entrepreneurship?

    Senior Two Entrepreneurship is the second-year lower secondary Entrepreneurship subject in Uganda’s O-level. It builds on Senior 1 by teaching learners how businesses are owned and formalised, how goods are produced, how products are marketed, and how money and financial institutions support trade before taxation closes the year.

    It is a hands-on course: learners study case studies, listen to guest speakers, run field visits and produce real marketing plans and products.

    Learners should be responsible for their own learning, think for themselves, and become critical thinkers ready to face new challenges.

    This guide is published by Remedial Corner, a Ugandan inclusive-education and revision platform, and follows the NCDC Curriculum Framework, the official source for the lower secondary curriculum.

    How many periods is Senior 2 Entrepreneurship?

    Senior 2 Entrepreneurship is allocated 72 periods across the school year. The programme planner splits these as 28 periods in Term 1, 18 periods in Term 2 and 26 periods in Term 3, which adds up to the full-year total of 72.

    TermThemePeriods
    Term 1Business Management28
    Term 2Business Management18
    Term 3Business Support26
    Total72
    Table 1: The Senior 2 programme planner, showing period allocation by term and theme.

    What topics are taught in Senior 2 Entrepreneurship?

    The Senior 2 Entrepreneurship topics are five: Legal Forms of Business Ownership, Production in Business, Marketing in a Small and Medium Business Enterprise, Money and Financial Institutions, and Taxation. Term 1 holds the first two, Term 2 the third, and Term 3 the last two.

    TopicTitleThemeTermPeriods
    6Legal Forms of Business OwnershipBusiness Management114
    7Production in BusinessBusiness Management114
    8Marketing in a Small and Medium Business EnterpriseBusiness Management218
    9Money and Financial InstitutionsBusiness Support320
    10TaxationBusiness Support36
    Total72
    Table 2: The five Senior 2 topics with their theme, term and period allocation.
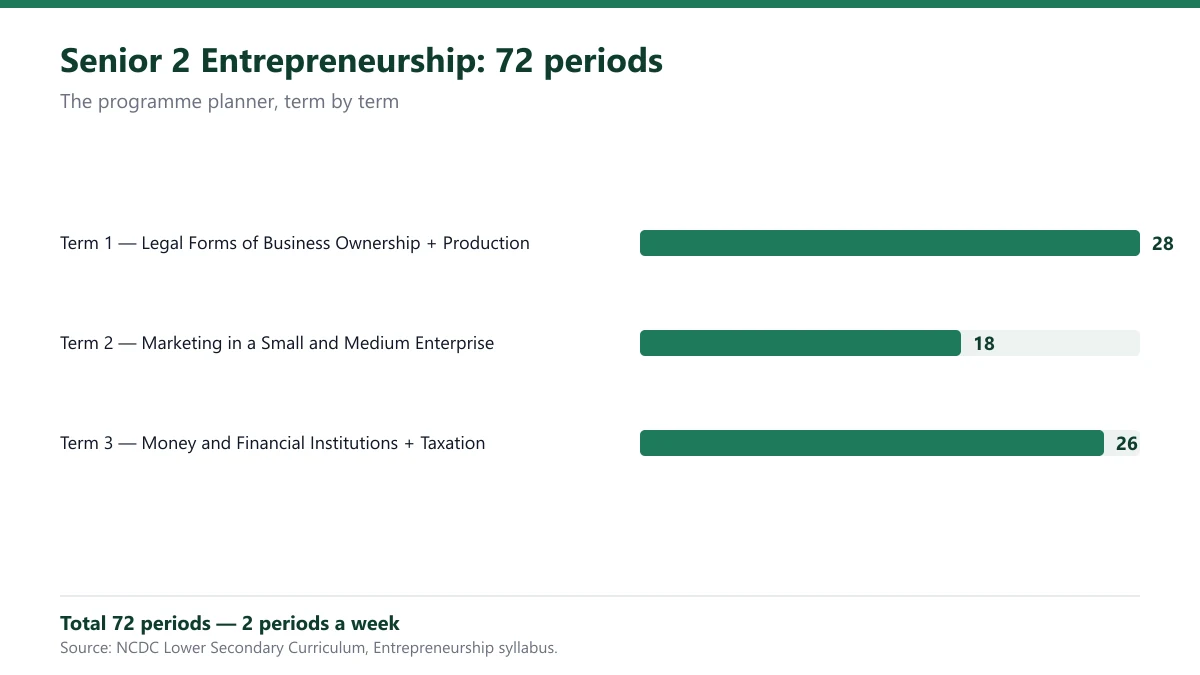
    Term-by-term period allocation for Senior 2 Entrepreneurship totalling 72 periods across three terms
    The Senior 2 programme planner: 28 periods in Term 1, 18 in Term 2 and 26 in Term 3, for 72 periods.

    Topic 6: Legal Forms of Business Ownership (Term 1)

    Topic 6 runs 14 periods in Term 1 under Business Management. Its competency is: “The learner compares the forms of business ownership and selects a suitable one.” Four sub-topics follow.

    Sub-topicTitlePeriods
    6.1Forms of Business Ownership3
    6.2Formalising a Business4
    6.3Cooperatives in Uganda4
    6.4Savings Credit and Cooperative Societies (SACCOs)3
    Total14
    Table 3: Topic 6 Legal Forms of Business Ownership sub-topics and their period allocations.

    6.1 Forms of Business Ownership (3 periods)

    Learners know the legal forms of business ownership, the types of limited companies, and the characteristics, advantages and disadvantages of each form. Groups study case studies and present the forms, while a guest speaker covers limited companies by single or multiple directorship, each by guarantee or shares.

    6.2 Formalising a Business (4 periods)

    Learners understand the process, benefits and indicators of a formalised business, plus the requirements, steps and limitations of registering, deregistering and re-registering one. They listen to a business owner, compose questions, build a guide for a new owner, and draw a registration flow chart.

    6.3 Cooperatives in Uganda (4 periods)

    Learners understand the meaning and history of cooperatives in Uganda, their principles and benefits, the types of cooperatives, and how one is formed. Groups produce a history timeline, agree a definition, and plan a report covering history, registration, principles, types, challenges and solutions.

    6.4 Savings Credit and Cooperative Societies (SACCOs) (3 periods)

    Learners understand financial cooperatives (SACCOs), how they operate, their benefits, and the challenges they face in Uganda with possible solutions. Groups investigate a SACCO case study, list benefits, outline solutions for debate, and visit a nearby SACCO to report on membership, savings, credit, benefits and challenges.

    Topic 7: Production in Business (Term 1)

    Topic 7 continues Term 1 under Business Management for 14 periods. Its competency is: “The learner produces quality products for sale.” Five sub-topics move from human wants to the machinery that turns raw materials into goods.

    Sub-topicTitlePeriods
    7.1Human Wants2
    7.2Factors of Production3
    7.3Specialisation, Division of Labour and Diversification in Production3
    7.4Raw Materials for Production3
    7.5Machinery, Equipment and Tools Used in Production3
    Total14
    Table 4: Topic 7 Production in Business sub-topics and their period allocations.

    7.1 Human Wants (2 periods)

    Learners distinguish between human wants and needs, understand the types of human wants, and appreciate their characteristics. Groups discuss wants and needs, build a table of types and characteristics, and link needs and wants to human rights and the 2030 sustainable development goals.

    7.2 Factors of Production (3 periods)

    Learners understand production, its types and stages, the benefits of record keeping, and the factors of production and their benefits. They make a simple production plan with a budget using spreadsheets, books and calculators, and produce an infographic or poster.

    7.3 Specialisation, Division of Labour and Diversification in Production (3 periods)

    Learners understand the difference between specialisation and division of labour, the types of specialisation, and the advantages and disadvantages of specialisation, division of labour and diversification. Groups count the specialist roles in making a product such as a car, then write about these concepts in their school.

    7.4 Raw Materials for Production (3 periods)

    Learners know the raw materials for a given product, the factors considered when selecting them, and how to use raw materials in production. Groups select a product, agree its raw materials and selection factors, produce it where possible, and build a table of raw products and their uses.

    7.5 Machinery, Equipment and Tools Used in Production (3 periods)

    Learners understand the factors considered when selecting machinery, equipment and tools for production, and they select and use the appropriate ones. A field visit identifies them in the community, learners argue for and against their use, and research how machines and tools have changed.

    Topic 8: Marketing in a Small and Medium Business Enterprise (Term 2)

    Topic 8 fills Term 2 under Business Management with 18 periods. Its competency is: “The learner markets and sells products.” Five sub-topics run from marketing through research, distribution, promotion and consumer protection.

    Sub-topicTitlePeriods
    8.1Introduction to Marketing3
    8.2Market Research4
    8.3Channels of Distribution4
    8.4Advertisement and Sales Promotion4
    8.5Consumer Protection3
    Total18
    Table 5: Topic 8 Marketing sub-topics and their period allocations.

    8.1 Introduction to Marketing (3 periods)

    Learners understand the differences between marketing and selling, create a simple marketing plan, appreciate the importance of marketing, and understand its challenges. The class discusses recent purchases, then groups plan, market and sell a product at a local fete and evaluate the challenges.

    8.2 Market Research (4 periods)

    Learners understand the importance of market research, design a market survey tool for a selected product, carry out research, and write a market research report. Pairs review research documents, groups design and run a survey, and present a summary report to the class.

    8.3 Channels of Distribution (4 periods)

    Learners understand the channels of distribution, the factors considered when selecting one, and how to select the most appropriate channel for a product. Pairs identify channels in their community, share findings on Uganda and Eastern Africa, and write a field-study report.

    8.4 Advertisement and Sales Promotion (4 periods)

    Learners understand the importance of advertising and sales promotion, use the correct methods for both, and promote different products. Groups study advertisements, list and rank methods, role play sales promotion, and design a poster to advertise a given product.

    8.5 Consumer Protection (3 periods)

    Learners understand the importance of consumer protection, the methods of protecting consumers, the agents involved, and the challenges of enforcing it in Uganda and other countries. Groups study case studies, hear a guest speaker, and write a report on the main challenges.

    Topic 9: Money and Financial Institutions (Term 3)

    Topic 9 opens Term 3 under Business Support and runs for 20 periods. Its competency is: “The learner appreciates the importance of money and financial institutions in conducting business.” Six sub-topics run from money to electronic banking.

    Sub-topicTitlePeriods
    9.1Money3
    9.2The Central Bank4
    9.3Commercial Banks4
    9.4Types of Bank Accounts3
    9.5Microfinance Institutions3
    9.6Electronic Banking3
    Total20
    Table 6: Topic 9 Money and Financial Institutions sub-topics and their period allocations.

    9.1 Money (3 periods)

    Learners understand the evolution of money, the advantages and disadvantages of barter exchange, the meaning, forms and functions of money, and saving to develop a banking culture. A banking visitor explains money’s origins, learners role play barter scenarios, and they explore forms of money in Africa.

    9.2 The Central Bank (4 periods)

    Learners understand the meaning of a central bank and its functions. Groups read a text on the central bank, compare its role to local banks and community saving schemes, investigate its origins, and produce a diagram of its key functions.

    9.3 Commercial Banks (4 periods)

    Learners know commercial banks and understand their role. Groups describe the banks they know and what makes them commercial, compare them to other banks, and research how the role is the same and different across Uganda and Africa.

    9.4 Types of Bank Accounts (3 periods)

    Learners distinguish between the types of bank accounts, their features and the difference between investment and savings, and they use a cheque for cash deposit and withdrawal and know how to open an account. Groups demonstrate a cheque and slips, and produce a leaflet encouraging a family to open an account.

    9.5 Microfinance Institutions (3 periods)

    Learners understand the meaning of microfinance institutions and their types. Groups discuss their role to small businesses, list types with examples from across Uganda, and write about how microfinance gives opportunities that larger banks cannot offer.

    9.6 Electronic Banking (3 periods)

    Learners understand electronic banking, identify electronic banking products, and know the benefits and challenges of e-banking. A guest speaker describes modern banking trends, groups present a case for e-banking, list products, and produce a poster or infographic.

    Topic 10: Taxation (Term 3)

    Topic 10 closes the year with six periods under Business Support. It is printed as a single block with six learning outcomes and no numbered sub-topics, and the detail page prints no competency statement for it.

    • understand what taxation is and its origin (v, u)
    • distinguish key terms used in taxation (u)
    • know the types of taxes (k)
    • know the advantages and disadvantages of direct and indirect taxes (u, s)
    • know the rights of a taxpayer (u, gs)
    • understand the obligations of a taxpayer (k)

    Learners read a text on the origin of taxation, for example in the Bible, the Quran and the historical background in Uganda, then debate how taxation has changed over time. Groups study articles on the types of taxes, discuss the advantages and disadvantages of direct and indirect taxes, and research the rights and obligations of a taxpayer.

    Assessment includes a short paragraph on how taxes work in the community and interview questions for taxpayers in local businesses. The O-Level Entrepreneurship Education textbook expands on this content.

    What do the learning-outcome codes (k), (u), (s), (v) and (gs) mean?

    The codes tag each learning outcome by type: (k) knowledge, (u) understanding, (s) skills, (v) values and (gs) generic skills. They appear in parentheses after outcomes so teachers can see at a glance whether an outcome targets knowing, doing or valuing, and how to assess it.

    CodeMeaning
    (k)Knowledge
    (u)Understanding
    (s)Skills
    (v)Values
    (gs)Generic skills
    Table 7: The five learning-outcome codes used across the syllabus.

    A knowledge outcome is tested differently from a skills outcome, and a values outcome is observed rather than marked.

    Why does 9.1 Money carry an unnumbered banks-and-banking block?

    The syllabus prints a block of banks-and-banking outcomes and activities between 9.1 Money and 9.2 The Central Bank, but it carries no sub-topic number. It cannot be a seventh sub-topic, because the six numbered sub-topics already total 20 periods, so it appears to be a print artefact rather than extra content.

    The block lists outcomes on banks and banking, types of banks, challenges faced by banks in Uganda, solutions and customer rights. Sitting inside the 9.1 Money pages without a number, it reads as supporting material, not a separate sub-topic.

    Sub-topicPeriods
    9.1 Money3
    9.2 The Central Bank4
    9.3 Commercial Banks4
    9.4 Types of Bank Accounts3
    9.5 Microfinance Institutions3
    9.6 Electronic Banking3
    Total20
    Table 8: The six numbered sub-topics of Topic 9 total exactly 20 periods.

    The planner’s 20 periods for Money and Financial Institutions match this total, confirming the block is not an extra sub-topic.

    What is the term-by-term sequence for Senior 2?

    The Senior 2 Entrepreneurship topics run term by term as follows. Term 1 covers Legal Forms of Business Ownership and Production in Business across 28 periods, Term 2 covers Marketing in a Small and Medium Business Enterprise across 18 periods, and Term 3 covers Money and Financial Institutions and Taxation across 26 periods.

    1. Term 1 — Business Management: Topic 6 (14 periods) and Topic 7 (14 periods) = 28 periods.
    2. Term 2 — Business Management: Topic 8 Marketing (18 periods) = 18 periods.
    3. Term 3 — Business Support: Topic 9 (20 periods) and Topic 10 (6 periods) = 26 periods.
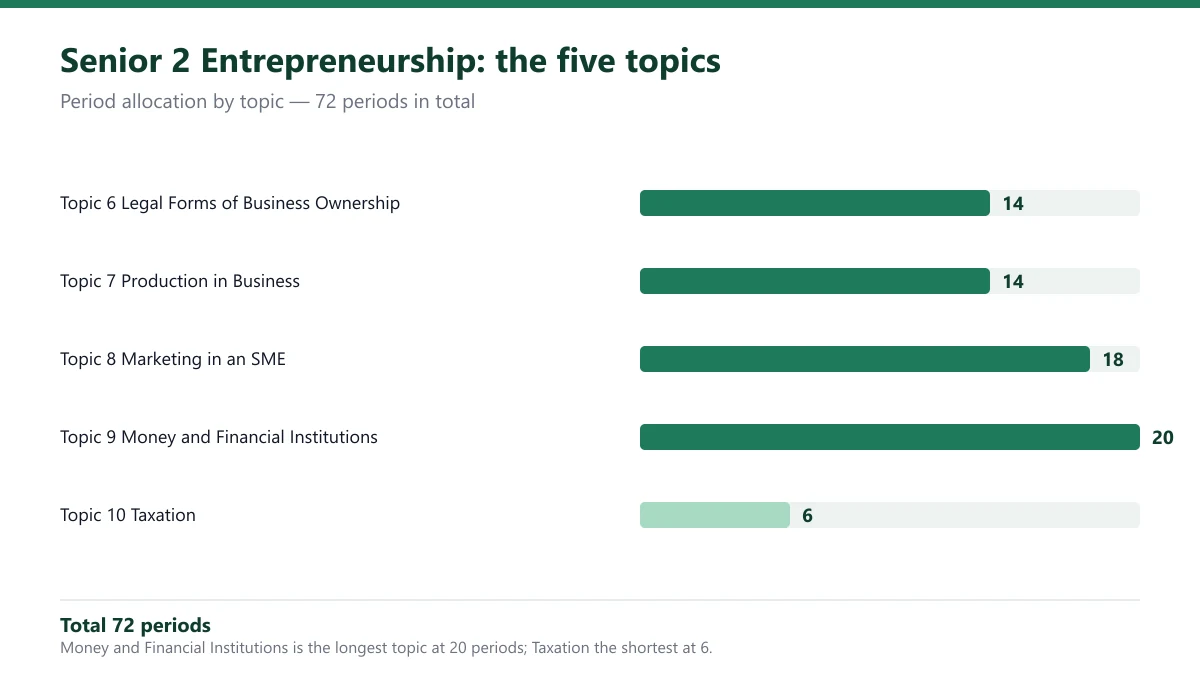
    Bar chart of the five Senior 2 topics: 14, 14, 18, 20 and 6 periods
    Money and Financial Institutions is the longest topic at 20 periods; Taxation is the shortest at 6.

    The sequence is cumulative: ownership first, then production, then marketing, then money, financial institutions and taxation. After Senior 2, the subject continues into Senior 3 with Business Planning and Introduction to Principles of Accounting — read our Senior 3 Entrepreneurship syllabus breakdown to see what follows.

    Whether you are a teacher writing termly schemes or a parent checking what your learner covers, the Senior 2 Entrepreneurship topics are compact enough to hold in one view: five topics, twenty sub-topics and 72 periods.

    Frequently asked questions about Senior 2 Entrepreneurship

    Teachers should base their lesson plans on the Learning Outcomes, using the Suggested Learning Activities as a guide.

    How many Senior 2 Entrepreneurship topics are there?

    Senior 2 Entrepreneurship has five topics: Legal Forms of Business Ownership, Production in Business, Marketing in a Small and Medium Business Enterprise, Money and Financial Institutions, and Taxation. Together these five topics total 72 periods across the three terms, with two in Term 1, one in Term 2 and two in Term 3.

    What is the longest topic in Senior 2 Entrepreneurship?

    Money and Financial Institutions is the longest topic, at 20 periods in Term 3. Marketing in a Small and Medium Business Enterprise is second at 18 periods, while Legal Forms of Business Ownership and Production in Business take 14 periods each and Taxation takes 6.

    What is the Legal Forms of Business Ownership competency?

    The Topic 6 competency is: “The learner compares the forms of business ownership and selects a suitable one.” It frames the four sub-topics, from knowing the legal forms and limited companies through formalising a business, cooperatives in Uganda and SACCOs.

    What is the Marketing competency in Senior 2?

    The Topic 8 competency is: “The learner markets and sells products.” It runs through all five marketing sub-topics, from the difference between marketing and selling through market research, distribution channels, advertising and sales promotion, and consumer protection, across 18 periods in Term 2.

    What is the Money and Financial Institutions competency?

    The Topic 9 competency is: “The learner appreciates the importance of money and financial institutions in conducting business.” It covers money, the central bank, commercial banks, bank accounts, microfinance institutions and electronic banking across 20 periods, the longest topic of the Senior 2 year.

    Which Senior 2 Entrepreneurship topics fall under Business Support?

    Money and Financial Institutions and Taxation fall under Business Support, both in Term 3. The other three topics — Legal Forms of Business Ownership, Production in Business and Marketing in a Small and Medium Business Enterprise — sit under Business Management in Terms 1 and 2.

    Where can I read the official Senior 2 Entrepreneurship topics?

    Uganda’s National Curriculum Development Centre (NCDC) publishes the lower secondary Entrepreneurship syllabus that sets this structure. This page summarises its Senior 2 content — every sub-topic, its exact period count and its learning-outcome codes — alongside the NCDC Curriculum Framework.

    For more subject breakdowns, browse the Remedial Corner blog, and read about Remedial Corner to meet the team behind these guides.

    Sources and further reading

    The sources behind this article, and where to read further.

  • Senior 1 Entrepreneurship topics: full topic breakdown

    Senior 1 Entrepreneurship topics: full topic breakdown

    Senior 1 Entrepreneurship topics cover five units across 72 periods: Introduction to Entrepreneurship Education, Businesses in Uganda, Business Ideas and Opportunities, Business Start-up Process, and Introduction to Government Revenue. The year opens by building entrepreneurial awareness, then moves to scanning the environment and finally to the start-up process. This guide lists every sub-topic, its exact period count and its learning outcomes.

    • 72 periods total — 24 in Term 1 and 24 in each of Terms 2 and 3.
    • Five topics — from Introduction to Entrepreneurship Education to Introduction to Government Revenue.
    • Two periods a week — compulsory in Senior 1 and Senior 2.
    • Three themes — Creating an Entrepreneurial Awareness, Scanning the Environment, and the Start-up Process.
    • 13 numbered sub-topics — each with its own period allocation.
    • Outcome codes — (k), (u), (s), (v) and (gs) tag every learning outcome.

    What is Senior 1 Entrepreneurship?

    Senior 1 Entrepreneurship topics make up the first-year lower secondary Entrepreneurship course in Uganda’s O-level. They introduce learners to entrepreneurial thinking before they scan the business environment and learn the start-up process. The subject is compulsory in Senior 1 and Senior 2 and is taught for two periods a week.

    The subject sits in Uganda’s competency-based lower secondary curriculum, published by the National Curriculum Development Centre (NCDC). It is an experiential course built around doing rather than only reading about business.

    • Discuss ideas and definitions in their own words.
    • Make and evaluate products from local resources.
    • Interview successful entrepreneurs in the community.
    • Run simple market surveys in the nearby trading centre.

    This guide is published by Remedial Corner, a Ugandan inclusive-education and revision platform. The period counts and competencies below follow the NCDC Curriculum Framework, the official source for the lower secondary curriculum.

    How many periods is Senior 1 Entrepreneurship?

    Senior 1 Entrepreneurship is allocated 72 periods across the full year. The programme planner splits these evenly: 24 periods in Term 1, 24 periods in Term 2, and 24 periods in Term 3. At two periods a week, the 72 periods carry five topics over the three terms.

    TermThemeTopicPeriods
    Term 1Creating an Entrepreneurial AwarenessIntroduction to Entrepreneurship Education24
    Term 2Scanning the EnvironmentBusinesses in Uganda12
    Term 2Scanning the EnvironmentBusiness Ideas and Opportunities12
    Term 3Start-up ProcessBusiness Start-up Process18
    Term 3Start-up ProcessIntroduction to Government Revenue6
    Total72
    Table 1: The Senior 1 programme planner, showing period allocation by term and theme.

    Term 1 holds one topic, Terms 2 and 3 hold two apiece, so the Senior 1 Entrepreneurship topics total exactly 72 periods.

    What themes organise the Senior 1 Entrepreneurship syllabus?

    Three themes organise the Senior 1 syllabus: Creating an Entrepreneurial Awareness (Term 1), Scanning the Environment (Term 2), and the Start-up Process (Term 3). Each theme groups the topics learners meet that term, so the year reads as one progression from awareness to action.

    1. Creating an Entrepreneurial Awareness — Term 1, the mindset that opens the year.
    2. Scanning the Environment — Term 2, reading the market and opportunities around the learner.
    3. Start-up Process — Term 3, turning an idea into a business.

    Every one of the Senior 1 Entrepreneurship topics sits under one of the three themes, so Term 1 builds attitude, Term 2 builds observation, and Term 3 builds action.

    What topics are taught in Senior 1 Entrepreneurship?

    The Senior 1 Entrepreneurship topics are five: Introduction to Entrepreneurship Education (24 periods), Businesses in Uganda (12), Business Ideas and Opportunities (12), Business Start-up Process (18), and Introduction to Government Revenue (6). Together they total 72 periods across the three terms.

    #TopicThemePeriods
    1Introduction to Entrepreneurship EducationCreating an Entrepreneurial Awareness24
    2Businesses in UgandaScanning the Environment12
    3Business Ideas and OpportunitiesScanning the Environment12
    4Business Start-up ProcessStart-up Process18
    5Introduction to Government RevenueStart-up Process6
    Total72
    Table 2: The five Senior 1 topics, their themes and their period allocations.
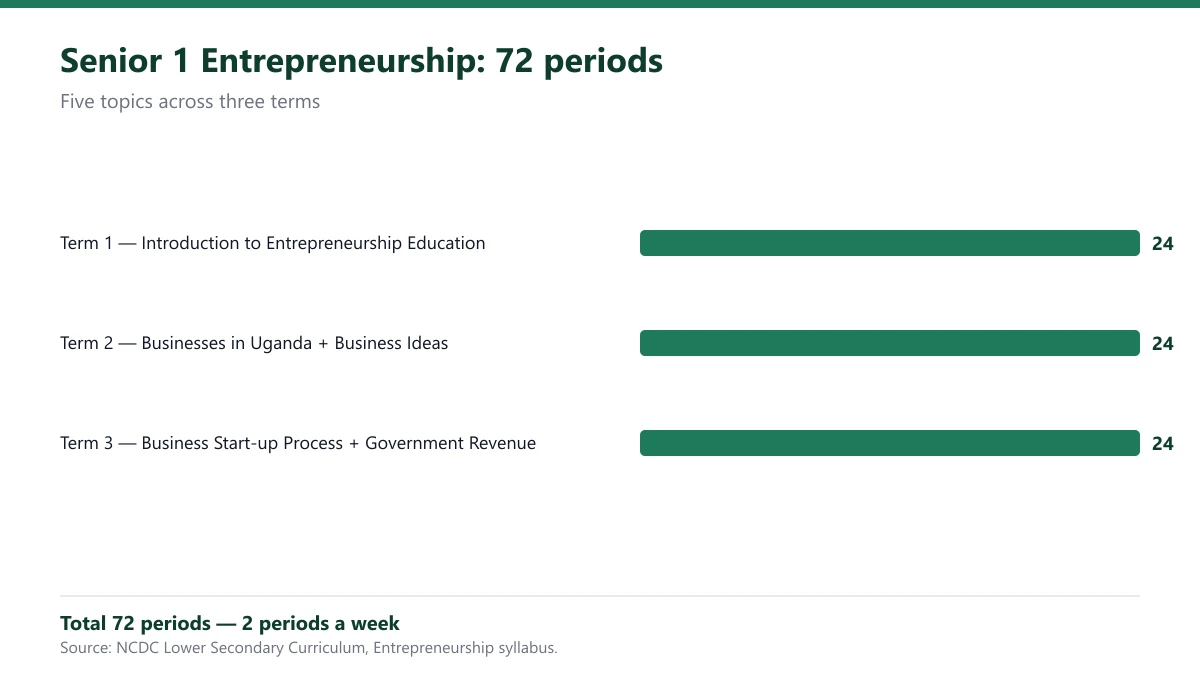
    Term-by-term breakdown of the five Senior 1 Entrepreneurship topics across 72 periods
    The five Senior 1 topics run across three terms: 24 periods in Term 1, then 24 and 24 in Terms 2 and 3.

    The topics are cumulative: awareness first, then reading the environment, then starting up and government revenue.

    Topic 1: Introduction to Entrepreneurship Education (Term 1, 24 periods)

    Topic 1 runs for 24 periods across Term 1, under the theme Creating an Entrepreneurial Awareness. Its competency is: “The learner appreciates the importance of studying Entrepreneurship Education and demonstrates characteristics of an Entrepreneur.” That one statement frames the four sub-topics that follow.

    Sub-topicTitlePeriods
    1.1The Entrepreneur5
    1.2Creativity and Innovation7
    1.3Risks in Business7
    1.4Technology and Business5
    Total24
    Table 3: Topic 1 sub-topics and their period allocations.
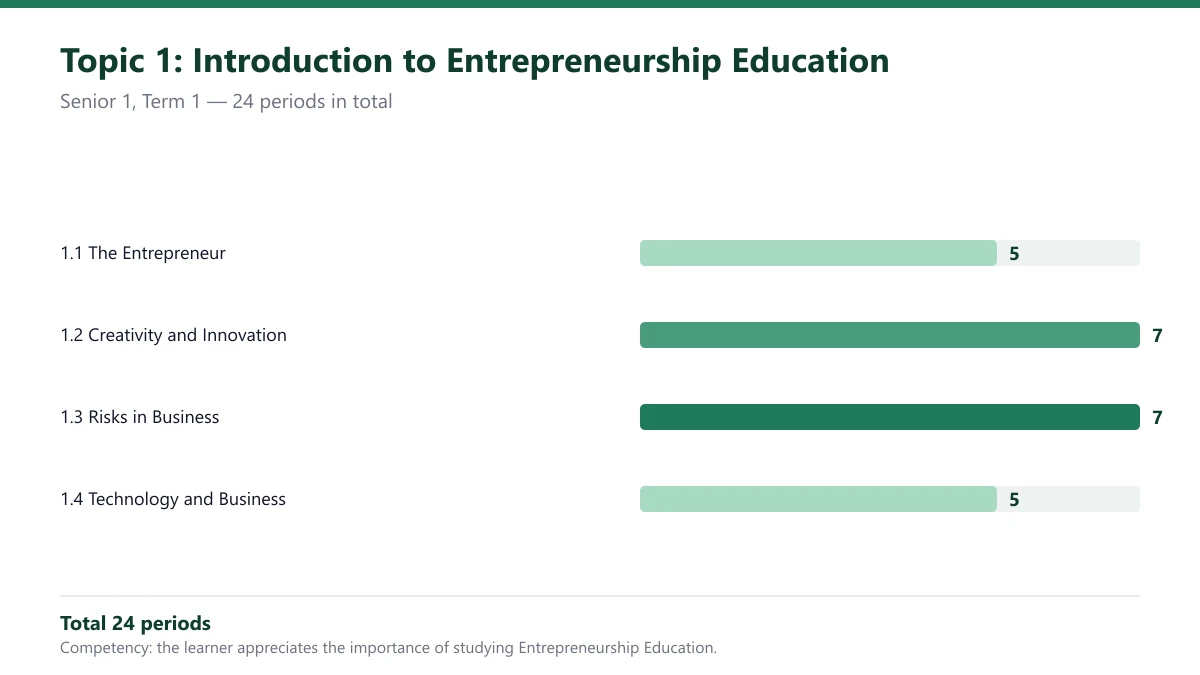
    Bar chart of Topic 1 sub-topic periods: 5, 7, 7 and 5, totalling 24
    Topic 1 splits its 24 periods across four sub-topics: The Entrepreneur (5), Creativity and Innovation (7), Risks in Business (7), and Technology and Business (5).

    1.1 The Entrepreneur (5 periods)

    Learners understand the purpose of Entrepreneurship Education, identify the key characteristics of an entrepreneur, and assess the benefits of an entrepreneur. Activities include a mind-map of the subject’s purpose, a poster advertising why students should study it, and a list of key characteristics. Learners then identify entrepreneurs in their community, and the teacher invites successful male and female entrepreneurs to class for questioning.

    1.2 Creativity and Innovation (7 periods)

    Learners understand creativity and innovation, then design, make and evaluate a product. They generate ideas for a product, such as a bridge-making simulation game using locally available resources, and plan the actions they will take. They then communicate design ideas in different ways and demonstrate how to make products to the class.

    1.3 Risks in Business (7 periods)

    Learners know risks in business and assess risks in business. They study case studies illustrating different risks, listen to accounts from business people, and identify the risks in each study, agreeing explanations and ways of minimising them. They present findings using ICT and play risk-taking simulation games to distinguish types of risk.

    1.4 Technology and Business (5 periods)

    Learners understand the role of technology in businesses. They consider the statement “Technology in business is a necessity”, think through the benefits and challenges of e-business, and identify examples of businesses in Uganda that use technology. Assessment weighs contrasting examples of technology in large businesses across Africa.

    Topic 2: Businesses in Uganda (Term 2, 12 periods)

    Topic 2 runs for 12 periods in Term 2, under the theme Scanning the Environment. Its competency is: “The learner participates in business operations in Uganda.” Two sub-topics follow, each with six periods.

    Sub-topicTitlePeriods
    2.1Types of Businesses6
    2.2Success in Business6
    Total12
    Table 4: Topic 2 sub-topics and their period allocations.

    2.1 Types of Businesses (6 periods)

    Learners understand the various types of businesses in Uganda and appreciate the importance of businesses to the community. Each group chooses a different business and records its type, key characteristics and the benefits it provides to the country, then shares its recording with another group. Learners also list the key features of a local business they know.

    2.2 Success in Business (6 periods)

    Learners know what makes a business successful, evaluate what causes a business to fail, and understand ways of reviving a failing business. They study successful and unsuccessful businesses, identify indicators of success and causes of failure, and role-play reviving an unsuccessful business.

    Topic 3: Business Ideas and Opportunities (Term 2, 12 periods)

    Topic 3 also runs in Term 2 for 12 periods, under Scanning the Environment. Its competency is: “The learner selects a business opportunity from the environment and conducts a market survey.” Three sub-topics of four periods each follow.

    Sub-topicTitlePeriods
    3.1Business Ideas4
    3.2Business Opportunities4
    3.3Market Survey4
    Total12
    Table 5: Topic 3 sub-topics and their period allocations.

    3.1 Business Ideas (4 periods)

    Learners demonstrate how to generate a business idea from the environment, generate an idea, and select a good business idea. They brainstorm sources of ideas, walk to a nearby trading centre to observe the environment, and discuss the factors that make a good idea. They also build a decision tree from a dilemma or probing question.

    3.2 Business Opportunities (4 periods)

    Learners understand the difference between a business idea and a business opportunity, and appreciate the characteristics of a good business opportunity. They differentiate the two, think of an example of each, and role-play conversations between business people as an opportunity was first explored.

    3.3 Market Survey (4 periods)

    Learners understand the importance of a market survey and carry one out. They study a good example of an effective survey, learn the steps to follow, and plan and conduct a simple market survey in the nearby community, considering customers, price, raw materials, location and competition.

    Topic 4: Business Start-up Process (Term 3, 18 periods)

    Topic 4 runs for 18 periods in Term 3, under the theme Start-up Process. Its competency is: “The learner follows the steps involved in starting a business, saves money and invests in a profitable venture.” Four sub-topics follow.

    Sub-topicTitlePeriods
    4.1Steps in Starting a Business4
    4.2Sources of Business Finance5
    4.3Savings and Investments5
    4.4Location of a Business4
    Total18
    Table 6: Topic 4 sub-topics and their period allocations.

    One print slip is worth flagging: the detail pages for sub-topics 4.3 and 4.4 are each headed “Topic 5: Business Start-up Process”, when their sub-topic numbers (4.3, 4.4) show they belong to Topic 4.

    4.1 Steps in Starting a Business (4 periods)

    Learners know the factors that enable an individual to start a business, including basic principles of effective record keeping, follow the correct steps, and prepare a budget. They brainstorm factors that enhance start-ups, listen to a prominent entrepreneur from the community, and practise preparing a budget.

    4.2 Sources of Business Finance (5 periods)

    Learners know the different sources of business finance and assess the benefits and challenges of each source. They discuss the sources, read case studies on their benefits and challenges, and identify the benefit and challenge of each source.

    4.3 Savings and Investments (5 periods)

    Learners know the factors that determine saving and investment, appreciate the reasons for and forms of saving, and prepare a savings plan using spreadsheets, books and calculators. They agree definitions, form a savings group or SACCO and start saving, and agree one investment plan.

    4.4 Location of a Business (4 periods)

    Learners know the factors considered when locating a business. They discuss the factors that influence location, examine contrasting locations, and design a guide for entrepreneurs choosing a location.

    Topic 5: Introduction to Government Revenue (Term 3, 6 periods)

    Topic 5 closes the year with six periods in Term 3, under the Start-up Process theme. Unlike Topics 1 to 4, it has no numbered sub-topics: the whole six periods sit under the one heading, Introduction to Government Revenue.

    Learners understand government revenue and why the government needs revenue, and they know the sources of government revenue. They begin by discussing “Where does the government get its money from?”, thinking of local, national and international examples.

    • Compare two sources of government revenue in detail using a diagram.
    • Discuss why governments need revenue and how it is distributed, comparing Uganda with neighbouring countries.
    • Debate an example where government revenue has or has not benefited the community.
    • Field study: identify facilities the government has provided around the school.
    • Write a letter to local government outlining funds needed to improve the community.

    The detail page for Topic 5 lists its learning outcomes without the competency line that Topics 1 to 4 carry. The O-Level Entrepreneurship Education textbook expands on this content.

    Do the Senior 1 planner totals match the detail pages?

    Yes. The planner and the detail pages reconcile exactly: Topic 1’s four sub-topics sum to 24 periods, Topic 2’s two sub-topics sum to 12, Topic 3’s three sum to 12, Topic 4’s four sum to 18, and Topic 5 adds 6 — a 72-period total.

    • Planner totals reconcile: 24 + 12 + 12 + 18 + 6 = 72 periods.
    • Sub-topics 4.3 and 4.4 are misprinted as “Topic 5” on their detail pages.
    • Topic 5’s detail page omits the competency line that Topics 1 to 4 include.

    What do the learning-outcome codes (k), (u), (s), (v) and (gs) mean?

    The codes tag each learning outcome by type: (k) knowledge, (u) understanding, (s) skills, (v) values, and (gs) generic skills. They sit in parentheses after outcomes so a teacher can see at a glance whether an outcome targets knowing, doing or valuing.

    CodeMeaning
    (k)Knowledge
    (u)Understanding
    (s)Skills
    (v)Values
    (gs)Generic skills
    Table 7: The five learning-outcome codes used across the syllabus.

    Many outcomes carry more than one code. For example, the purpose outcome in sub-topic 1.1 is tagged (u, v) — understanding plus values — while the risk assessment in 1.3 is tagged (s, gs) — skills plus generic skills.

    How should teachers plan lessons from the three-column layout?

    The syllabus sets each topic out in three columns: Learning Outcomes, Suggested Learning Activities, and Sample Assessment Strategy. Teachers base lesson plans on the Learning Outcomes and treat the activities as a guide, because the syllabus says they are not the only possible activities.

    These are not the only possible learning activities; teachers are encouraged to extend these and devise their own that are appropriate to the needs of their class.

    The three columns map onto a lesson: outcomes are the objectives, activities are the lesson body, and the assessment strategy shows how to check understanding. In an inclusive classroom, a teacher can adapt any activity to mixed abilities without changing the learning outcome.

    What is the term-by-term sequence for Senior 1?

    Term 1 covers Topic 1, Introduction to Entrepreneurship Education, across 24 periods. Term 2 covers Businesses in Uganda and Business Ideas and Opportunities, 12 periods each. Term 3 covers Business Start-up Process (18 periods) and Introduction to Government Revenue (6), for 72 periods overall.

    After Senior 1, the subject continues into Senior 2 with five more topics, listed below. These build directly on the Senior 1 Entrepreneurship topics covered here.

    • Legal Forms of Business Ownership — 14 periods.
    • Production in Business — 14 periods.
    • Marketing in a Small Business Enterprise — 18 periods.
    • Money and Financial Institutions — 20 periods.
    • Taxation — 6 periods.

    For the accounting-heavy later years, see the Senior 3 Entrepreneurship syllabus breakdown.

    Frequently asked questions about the S1 topics

    Is Entrepreneurship compulsory in Senior 1?

    Yes. Entrepreneurship is compulsory in Senior 1 and Senior 2, where it is studied for two periods a week, and it becomes an elective in Senior 3 and Senior 4. A Senior 1 learner covers the full 72-period syllabus across the three terms.

    How many periods a week is Entrepreneurship taught in Senior 1?

    Entrepreneurship is taught for two periods a week in Senior 1 and Senior 2. By comparison, Senior 3 and Senior 4 allocate four periods a week. Across the full year, the Senior 1 timetable totals 72 periods for the subject.

    How many topics are in Senior 1 Entrepreneurship?

    Senior 1 Entrepreneurship has five topics: Introduction to Entrepreneurship Education (24 periods), Businesses in Uganda (12), Business Ideas and Opportunities (12), Business Start-up Process (18), and Introduction to Government Revenue (6). Together these five topics total 72 periods across the year.

    What is the Introduction to Entrepreneurship Education competency?

    The Topic 1 competency is: “The learner appreciates the importance of studying Entrepreneurship Education and demonstrates characteristics of an Entrepreneur.” This one statement frames all four sub-topics — the entrepreneur, creativity and innovation, risks in business, and technology and business.

    Does Senior 1 Entrepreneurship include Government Revenue?

    Yes. Introduction to Government Revenue is Topic 5 in Senior 1, allocated 6 periods in Term 3 under the Start-up Process theme. It covers what government revenue is, why the government needs revenue, and the sources of government revenue in Uganda.

    What topics follow Senior 1 Entrepreneurship in Senior 2?

    Senior 2 continues with five topics: Legal Forms of Business Ownership (14 periods), Production in Business (14), Marketing in a Small Business Enterprise (18), Money and Financial Institutions (20), and Taxation (6). These five topics total 72 periods across the Senior 2 year.

    Where can I read the official Senior 1 Entrepreneurship syllabus?

    Uganda’s National Curriculum Development Centre (NCDC) publishes the lower secondary Entrepreneurship syllabus that sets this structure. This page summarises the Senior 1 Entrepreneurship topics in one place — every sub-topic, its exact period count and its learning-outcome codes — alongside the NCDC Curriculum Framework.

    Remember the arithmetic: 24 + 12 + 12 + 18 + 6 equals 72 periods — the whole of Senior 1 Entrepreneurship.

    For more subject breakdowns, browse the Remedial Corner blog, and read about Remedial Corner to meet the team behind these guides.

    Sources and further reading

    The sources behind this article, and where to read further.

  • Senior 3 Entrepreneurship syllabus: full topic breakdown

    Senior 3 Entrepreneurship syllabus: full topic breakdown

    The Senior 3 Entrepreneurship syllabus covers two topics across 144 periods: Business Planning in Term 1, and Introduction to Principles of Accounting across Terms 2 and 3. Tax Administration closes the year as a 14-period unit. The breakdown below covers every sub-topic, its period allocation and its learning outcomes.

    • 144 periods total — 48 in Term 1 and 96 across Terms 2 and 3.
    • Two topics — Business Planning, then Introduction to Principles of Accounting.
    • Four periods a week in Senior 3 and Senior 4.
    • Elective in S3–S4, compulsory in S1–S2.
    • Outcome codes (k), (u), (s), (v) and (gs) tag every learning outcome.

    What is Senior Three Entrepreneurship?

    Senior Three Entrepreneurship is the lower secondary Entrepreneurship subject taken in the third year of Uganda’s O-level. It builds on the S1 and S2 topics by teaching learners to plan a business and then to record and report its finances through basic accounting.

    The subject sits in Uganda’s competency-based lower secondary curriculum, published by the National Curriculum Development Centre (NCDC). It is an experiential course aimed at deeper understanding: learners develop business ideas, plan a specific enterprise, and then learn the bookkeeping and financial statements a real business needs.

    The rationale ties the subject to Uganda’s Vision 2040 and the National Development Plan, building the ability to use emerging and traditional technologies and to extract value from them. The teacher’s role is to build on learners’ existing knowledge and experience, then extend it by posing problems. Learners are expected to think for themselves and become critical thinkers.

    Senior 2 leads into this with Legal Forms of Business Ownership, Production in Business, Marketing in an SME, Money and Financial Institutions, and Taxation, so learners arrive in Senior 3 already familiar with business basics.

    This guide is published by Remedial Corner, a Ugandan inclusive-education and revision platform. The period counts and competencies below follow the NCDC Curriculum Framework, the official source for the lower secondary curriculum.

    How many periods is Senior 3 Entrepreneurship?

    Senior 3 Entrepreneurship is allocated 144 periods in total. The planner splits these as 48 periods for Business Planning in Term 1, 48 and 34 periods for Introduction to Principles of Accounting across Terms 2 and 3, and 14 periods for Tax Administration in Term 3.

    The Senior 3 Entrepreneurship programme planner sets out the year in four rows. Term 1 belongs entirely to Business Planning, while Terms 2 and 3 carry Accounting and then Tax Administration. The table below shows the exact split.

    TermTopicPeriods
    Term 1Business Planning48
    Term 2Introduction to Principles of Accounting48
    Term 3Introduction to Principles of Accounting34
    Term 3Tax Administration in Uganda14
    Total144
    Table 1: The Senior 3 programme planner, showing period allocation by term.

    At four periods a week, the year divides naturally across the three terms. The subject doubles its weekly load compared with Senior 1 and Senior 2, which allocate two periods a week.

    What topics are taught in Senior 3 Entrepreneurship?

    Senior 3 Entrepreneurship teaches two topics: Topic 11, Business Planning, in Term 1, and Topic 12, Introduction to Principles of Accounting, in Terms 2 and 3. A shorter Tax Administration unit closes Term 3, but it sits inside Topic 12 as sub-topic 12.8.

    The subject moves in one clean arc: first the learner plans a business, then the learner learns to keep its books. Everything in Terms 2 and 3 depends on the planning work done in Term 1, which is why the Senior 3 Entrepreneurship syllabus sequences them in that order.

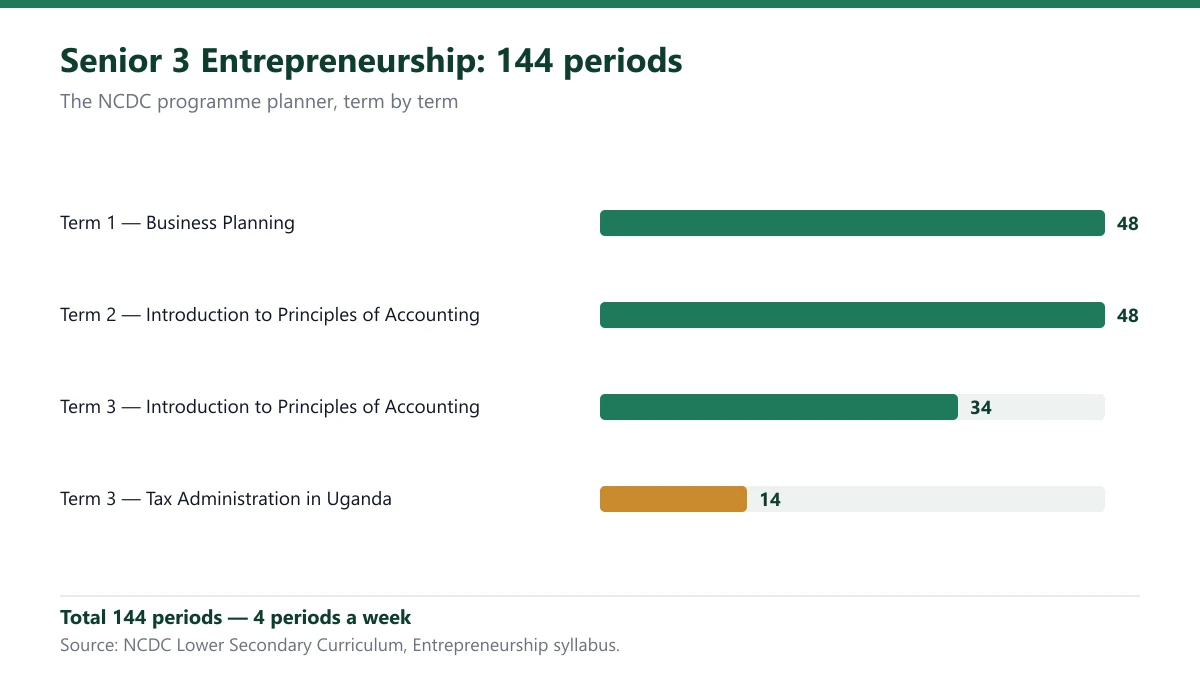
    Term-by-term period allocation for Senior 3 Entrepreneurship totalling 144 periods
    The official programme planner: 48 periods in Term 1, then 48 and 34 for Accounting, plus 14 for Tax Administration in Uganda.

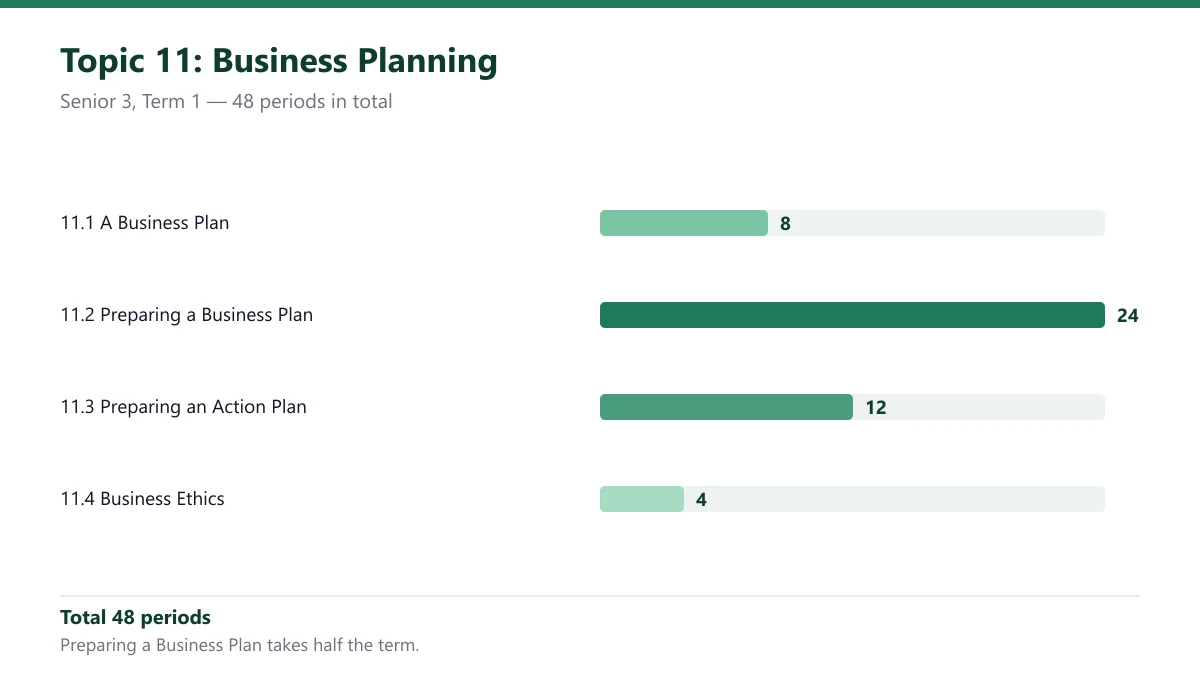
    Topic 11: Business Planning (Term 1)

    Topic 11 runs for 48 periods across Term 1, under the theme Business Planning. Its competency is: “The learner prepares a business plan for a selected business.” That single statement frames all four sub-topics that follow.

    What are the sub-topics of Business Planning?

    Business Planning has four sub-topics: 11.1 A Business Plan (8 periods), 11.2 Preparing a Business Plan (24 periods), 11.3 Preparing an Action Plan (12 periods), and 11.4 Business Ethics (4 periods). Together they total 48 periods, which is the whole of Term 1.

    Sub-topicTitlePeriods
    11.1A Business Plan8
    11.2Preparing a Business Plan24
    11.3Preparing an Action Plan12
    11.4Business Ethics4
    Total48
    Table 2: Topic 11 Business Planning sub-topics and their period allocations.
    Bar chart of Business Planning sub-topic periods: 8, 24, 12 and 4, totalling 48
    Preparing a Business Plan takes 24 of the 48 Term 1 periods — half the term on one sub-topic.

    11.1 A Business Plan (8 periods)

    Learners here understand the purpose of a business plan and use one to plan a business and share it with different stakeholders. They also use the Internet purposefully to browse information about business plans.

    Activities include reviewing business plans in groups to identify what makes an effective plan, discussing the term stakeholder, and identifying which stakeholder each plan was written for. Learners also research networking opportunities in Uganda from local to national and formal to informal, and discuss networking etiquette.

    11.2 Preparing a Business Plan (24 periods)

    This is the largest single sub-topic in the Senior 3 Entrepreneurship syllabus. Learners understand the steps in preparing a business plan and the importance of cash flow in processing and manufacturing.

    Learners evaluate each step and relate it to cash flow, research a business that suffered from cash-flow problems, and identify when it should have sought support. They compare two business opportunities with a simple SWOT (Strengths, Weaknesses, Opportunities, Threats) analysis. Assessment has learners prepare a business plan for a selected opportunity.

    11.3 Preparing an Action Plan (12 periods)

    Learners appreciate the importance of an action plan and its relation to a business plan, and they prepare an action plan of their own. They also practise making presentations with objects and animation.

    Activities include studying a sample action plan, discussing the importance of clear targets and aims, and producing an action plan for one key aim. Learners present their business plan to an audience using relevant technology, with animation and objects.

    11.4 Business Ethics (4 periods)

    Learners appreciate the principles of good business ethics and understand acceptable business behaviour towards customers, employees, society and government. They also cover customer attraction, customer care and customer retention.

    Activities include reviewing case studies of ethical and unethical practice and producing an ethics charter for a local business. Role play illustrates good and bad behaviour towards customers, and learners agree acceptable behaviour towards employees, society and government.

    Topic 12: Introduction to Principles of Accounting (Terms 2–3)

    Topic 12 carries the second half of the Senior 3 Entrepreneurship syllabus across Terms 2 and 3, under the theme Business Management. Its competency is: “The learner uses relevant books of original entry to process financial information gathered from source documents.”

    What are the sub-topics of Introduction to Principles of Accounting?

    Introduction to Principles of Accounting has eight sub-topics: Bookkeeping (5), Source Documents (5), Books of Original Entry (13), The Ledger (15), Trial Balance (14), Statement of Profit or Loss and Other Comprehensive Income (15), Statement of Financial Position (15), and Tax Administration in Uganda (14).

    Sub-topicTitlePeriods
    12.1Bookkeeping5
    12.2Source Documents5
    12.3Books of Original Entry13
    12.4The Ledger15
    12.5Trial Balance14
    12.6Statement of Profit or Loss and Other Comprehensive Income15
    12.7Statement of Financial Position15
    12.8Tax Administration in Uganda14
    Total96
    Table 3: Topic 12 sub-topics and their period allocations, including Tax Administration.
    Bar chart of eight accounting sub-topic periods, from Bookkeeping at 5 to Tax Administration at 14
    Eight sub-topics carry Senior 3 Accounting. Sub-topics 12.1 to 12.7 total 82 periods; Tax Administration adds 14.

    The accounting sub-topics 12.1 to 12.7 add up to 82 periods, and Tax Administration adds 14 more for a full-topic total of 96. The planner splits Accounting itself as 48 periods in Term 2 and 34 in Term 3, which matches the 82.

    Bookkeeping and Source Documents

    12.1 Bookkeeping (5 periods) has learners understand bookkeeping and related accounts, appreciate its importance, and demonstrate cost accounting using spreadsheets. They record a company’s transactions, produce their own ledger, and build a spreadsheet of “a day in the life of a local store”.

    12.2 Source Documents (5 periods) has learners know and prepare the source documents used in bookkeeping. They contrast examples from familiar businesses, practise preparing documents for a range of business types, and sort documents into groups by agreed criteria.

    Books of Original Entry and the Ledger

    12.3 Books of Original Entry (13 periods) has learners know and prepare the books of original entry. They examine a range of accounting journals, discuss how transactions are recorded, and design books of original entry in pairs.

    12.4 The Ledger (15 periods) has learners know a ledger, appreciate the different types of ledgers, and prepare ledger accounts. They post journal entries to a ledger using the double entry system and explain the posting process to a partner.

    Trial Balance

    12.5 Trial Balance (14 periods) has learners know a trial balance, understand its uses, and prepare one. They also identify and correct errors. Activities include preparing an accurate and an inaccurate trial balance and challenging each other to spot which is which.

    Statement of Profit or Loss and Other Comprehensive Income

    12.6 Statement of Profit or Loss and Other Comprehensive Income (15 periods) has learners know and prepare the statement. Using their trial balances, they discuss at what point profit should lead to further investment and prepare solutions for when a loss appears.

    Statement of Financial Position

    12.7 Statement of Financial Position (15 periods), also called the Balance Sheet, has learners understand its key components and how spreadsheets support them. They learn the accounting equation, list the assets and liabilities of their school, and prepare a balance sheet using spreadsheets and a calculator.

    Tax Administration in Uganda

    Tax Administration in Uganda is sub-topic 12.8, allocated 14 periods in Term 3. On its detail page the syllabus misprints the sub-topic number as “12.1” rather than 12.8.

    Learners know tax administration and appreciate the role of the Uganda Revenue Authority (URA) in tax administration. They learn the taxes URA collects, the taxes and duties collected by Local Government Authorities, and the non-tax revenue collected by other government agencies.

    Activities include preparing questions for a guest speaker on URA’s role and preparing an information report on tax administration in Uganda. Learners examine how URA is organised and create a list of non-tax revenue types. The O-Level Entrepreneurship Education textbook expands on this content.

    What do the learning-outcome codes (k), (u), (s), (v) and (gs) mean?

    The codes tag each learning outcome by type: (k) knowledge, (u) understanding, (s) skills, (v) values, and (gs) generic skills. They appear in parentheses after outcomes so teachers can see at a glance whether an outcome targets knowing, doing or valuing.

    CodeMeaning
    (k)Knowledge
    (u)Understanding
    (s)Skills
    (v)Values
    (gs)Generic skills
    Table 4: The five learning-outcome codes used across the syllabus.
    Diagram of the five NCDC learning-outcome codes: k, u, s, v and gs
    Every learning outcome is tagged (k), (u), (s), (v) or (gs), so you can see at a glance whether it targets knowing, doing or valuing.

    Because a single outcome can be tagged with more than one code, the letters tell a teacher how to assess it. A knowledge outcome is tested differently from a skills outcome, and a values outcome is observed rather than marked.

    Which cross-cutting issues run through the S3 syllabus?

    Six cross-cutting issues run through the lower secondary Entrepreneurship syllabus: environmental awareness, health awareness, mixed abilities and involvement, life skills, socio-economic challenges, and citizenship and patriotism. The Senior 3 topics embed these in activities such as ethics charters and tax discussions.

    • Environmental awareness
    • Health awareness
    • Mixed abilities and involvement
    • Life skills
    • Socio-economic challenges
    • Citizenship and patriotism

    The mixed abilities and involvement issue matters most to inclusive-education platforms like Remedial Corner: it asks teachers to plan activities every learner can join, including learners with special needs.

    Teachers fold these issues into a lesson without adding new periods. A tax lesson on URA doubles as a citizenship and patriotism discussion, while a business-ethics role play doubles as a life-skills exercise on customer care.

    How should teachers plan lessons from the three-column layout?

    The syllabus presents each topic in three columns: Learning Outcomes, Suggested Learning Activities, and Sample Assessment Strategy. Teachers must base lesson plans on the Learning Outcomes and treat the activities as guidance only, because the syllabus says they are not the only possible activities.

    The three columns map cleanly onto a lesson: the Learning Outcomes are the objectives, the Suggested Learning Activities are ideas for the lesson body, and the Sample Assessment Strategy shows how to check understanding. Teachers are encouraged to extend the activities and devise their own.

    The suggested learning activities are not the only possible learning activities; teachers are encouraged to extend these and devise their own.

    In practice, this means a teacher planning Topic 11.2 should write objectives from its learning outcomes first, then choose or adapt activities such as the SWOT comparison, and finally pick an assessment from the sample strategy column.

    The Sample Assessment Strategy column shows how the syllabus suggests checking each outcome. For 11.2 the sample strategy is a prepared business plan, while for 12.5 it is a corrected trial balance. Matching assessment to outcome keeps the three columns aligned.

    Because the activities are a guide, a teacher in an inclusive classroom can adapt each one to mixed abilities. A role play on customer care works for learners who struggle with writing, and a spoken question-and-answer can replace a written test without changing the Learning Outcome.

    Why does Topic 12 say 92 periods when the sub-topics total 82?

    The Topic 12 header prints 92 periods, but the seven accounting sub-topics (12.1 to 12.7) sum to 82, while the programme planner splits Accounting as 48 plus 34, which also gives 82. The 144 total reconciles as 48 + 82 + 14, so the printed 92 is a typo.

    This is a genuine print error in the syllabus, and it is easy to trip over. The accounting sub-topics 12.1 through 12.7 sum to 82, and Tax Administration adds 14, giving a true Topic 12 total of 96. The header’s “92” matches neither figure.

    ComponentPeriods
    Topic 11 Business Planning48
    Topic 12 accounting sub-topics (12.1–12.7)82
    Tax Administration in Uganda (12.8)14
    Full-year total144
    Table 5: How the Senior 3 total of 144 periods reconciles as 48 + 82 + 14.

    Because the planner’s own split (48 + 34 = 82 for Accounting, plus 14 for tax) matches the sub-topic sums, the 144 total is consistent. Only the printed “92” on the Topic 12 header is out of step.

    What is the term-by-term sequence for Senior 3?

    Term 1 covers Topic 11, Business Planning, across 48 periods. Term 2 opens Topic 12 with 48 periods of Introduction to Principles of Accounting. Term 3 finishes Topic 12 with 34 periods of Accounting, then closes with 14 periods of Tax Administration in Uganda, for 144 periods overall.

    The sequence is deliberately cumulative. A learner who can plan a business in Term 1 is ready to record its transactions in Term 2, and to finish its financial statements and tax obligations in Term 3.

    After Senior 3, the subject continues into Senior 4 with Topic 13 Insurance (48 periods in Term 1), Topic 14 International Trade (48 periods in Term 2) and Topic 15 Tax Compliance (40 periods in Term 3). These build directly on the planning and accounting foundations set in the Senior 3 Entrepreneurship syllabus.

    Whether you are a teacher writing termly schemes or a parent checking what your learner covers, the Senior 3 Entrepreneurship syllabus is compact enough to hold in one view: two topics, twelve sub-topics, and 144 periods. Bookmark this breakdown as your quick reference.

    Frequently asked questions about the S3 syllabus

    Is Entrepreneurship compulsory in Senior 3?

    No. Entrepreneurship is compulsory in Senior 1 and Senior 2, and it becomes an elective in Senior 3 and Senior 4. A learner in Senior 3 studies it for four periods a week, but only if they choose the subject as one of their electives.

    How many periods a week is Entrepreneurship taught in Senior 3?

    Entrepreneurship is taught for four periods a week in Senior 3 and Senior 4. By comparison, Senior 1 and Senior 2 allocate two periods a week. Across the full year, the Senior 3 timetable totals 144 periods for the subject.

    What is the Business Planning competency in Senior 3?

    The Topic 11 competency is: “The learner prepares a business plan for a selected business.” This single statement frames all four sub-topics, from understanding the purpose of a business plan through preparing it, preparing an action plan, and applying business ethics.

    What is the Introduction to Principles of Accounting competency in Senior 3?

    The Topic 12 competency is: “The learner uses relevant books of original entry to process financial information gathered from source documents.” It links the source documents that record transactions to the journals, ledger, trial balance and financial statements that follow.

    Does the Senior 3 syllabus include Tax Administration?

    Yes. Tax Administration in Uganda is sub-topic 12.8 in the Entrepreneurship syllabus for Senior 3, allocated 14 periods in Term 3. It covers the role of the Uganda Revenue Authority, the taxes URA and local government collect, and non-tax revenue.

    What topics follow Senior 3 Entrepreneurship in Senior 4?

    Senior 4 continues with three topics: Topic 13 Insurance (48 periods in Term 1), Topic 14 International Trade (48 periods in Term 2), and Topic 15 Tax Compliance (40 periods in Term 3). These build directly on the planning and accounting foundations set in Senior 3.

    Where can I read the official Senior 3 Entrepreneurship syllabus?

    Uganda’s National Curriculum Development Centre (NCDC) publishes the lower secondary Entrepreneurship syllabus that sets this structure. This page summarises its Senior 3 content in one place — every sub-topic, its exact period count and its learning-outcome codes — alongside the NCDC Curriculum Framework that governs the subject’s status and period allocation.

    For more subject breakdowns, browse the Remedial Corner blog, and read about Remedial Corner to meet the team behind these guides.

    Sources and further reading

    The sources behind this article, and where to read further.

  • Turning Ideas into Action: How to Write an Execution Plan for Your Business

    Turning Ideas into Action: How to Write an Execution Plan for Your Business

    Introduction

    Every business begins with an idea. But ideas alone don’t generate revenue, build teams, or create market impact. The bridge between a brilliant concept and tangible results is a robust execution plan. An execution plan transforms vision into actionable steps, ensuring that every team member understands their role, deadlines are met, and resources are allocated efficiently. This comprehensive guide will teach you how to prepare an action plan that drives success. We will explore the critical differences between a business plan vs action plan, delve into business execution strategy, and provide tools for setting clear business targets and measurable business aims. Additionally, we will outline an operational action plan that keeps your business on track. By the end of this article, you will have a complete framework to turn your ideas into action.

    Understanding the Execution Plan

    An execution plan is a detailed roadmap that outlines the specific steps required to achieve a business goal. It goes beyond high-level strategy by breaking down objectives into actionable tasks, assigning responsibilities, setting timelines, and defining metrics for success. Unlike a business plan, which provides an overarching vision and financial projections, an execution plan focuses on the ‘how’ and ‘when’ of implementation. It is a living document that guides daily operations and ensures alignment across the organization. For entrepreneurs and managers, mastering the art of execution planning is essential for turning ideas into measurable outcomes.

    Business Plan vs Action Plan: Key Differences

    Understanding the distinction between a business plan vs action plan is crucial for effective management. A business plan is a comprehensive document that outlines the company’s vision, mission, market analysis, financial forecasts, and long-term strategy. It is typically used to secure funding and guide overall direction. In contrast, an action plan is a tactical tool that breaks down specific goals into concrete steps. While a business plan asks ‘what’ and ‘why,’ an action plan answers ‘who,’ ‘what,’ ‘when,’ and ‘how much.’ for instance, a business plan might state a goal to increase market share by 20% in two years. An action plan would detail the marketing campaigns, sales targets, resource allocation, and weekly check-ins required to achieve that goal. Both documents are essential, but they serve different purposes. An execution plan bridges the gap between strategy and daily operations.

    Aspect Business Plan Action Plan
    Purpose Strategic direction and fundraising Tactical implementation
    Timeframe 1–5 years Weeks to months
    Detail Level High-level overview Granular tasks and deadlines
    Audience Investors, board, executives Project teams, managers
    Flexibility Annual updates Regular revisions

    Business Execution Strategy: The Foundation

    A solid business execution strategy is the backbone of any successful execution plan. It involves aligning resources, processes, and people to achieve strategic objectives. Key components include clear communication of goals, accountability structures, performance metrics, and continuous improvement mechanisms. To develop an effective execution strategy, start by defining your strategic priorities. What are the three to five most critical objectives for the next quarter? Then, cascade these priorities down to departmental and individual levels. Ensure that every team member understands how their work contributes to the bigger picture. Regularly review progress and adjust tactics as needed. Remember, execution isn’t a one-time event but an ongoing discipline.

    Setting Clear Business Targets

    Without clear business targets, execution plans lack direction. Targets should be specific, measurable, achievable, relevant, and time-bound (SMART). For instance, instead of saying ‘increase sales,’ a clear target is ‘increase monthly recurring revenue by 15% by Q3 2025.’ When setting targets, involve key stakeholders to ensure buy-in and realism. Use historical data and market research to inform your goals. Break down annual targets into quarterly, monthly, and weekly milestones. This granularity makes progress trackable and allows for early course correction. Remember, clear business targets serve as the North Star for your execution plan.

    Measurable Business Aims: Defining Success

    Measurable business aims translate targets into quantifiable indicators. These are the key performance indicators (KPIs) that tell you whether you are on track. Examples include customer acquisition cost, net promoter score, conversion rate, and gross margin. When defining measurable aims, ensure they are directly linked to your strategic objectives. For each aim, establish a baseline, target value, and measurement frequency. Use dashboards and reporting tools to monitor progress in real time. Measurable business aims also facilitate accountability; when everyone knows the numbers, it is easier to identify gaps and celebrate wins. Incorporate both leading indicators (predictive) and lagging indicators (outcome-based) for a balanced view.

    Operational Action Plan: Daily Execution

    An operational action plan details the day-to-day activities required to achieve your targets. It includes task lists, resource assignments, timelines, and dependencies. To create an effective operational plan, start by mapping out the major phases of your project or initiative. Then, break each phase into specific tasks. For each task, assign a responsible person, set a deadline, and identify necessary resources. Use project management tools like Asana, Trello, or Jira to track progress. Regularly hold stand-up meetings or check-ins to address blockers. An operational action plan should be flexible enough to accommodate changes while maintaining focus on the end goal. It is the engine that drives execution.

    How to Prepare an Action Plan: Step-by-Step

    Learning how to prepare an action plan is a critical skill for any business leader. Follow these steps to create a robust action plan:

    1. Define the Goal: Clearly articulate what you want to achieve. Use SMART criteria.
    2. Identify Tasks: Break the goal into smaller, manageable tasks. List everything that needs to happen.
    3. Assign Responsibilities: For each task, designate a person or team accountable for completion.
    4. Set Deadlines: Establish realistic timelines for each task, including start and end dates.
    5. Allocate Resources: Determine the budget, tools, and personnel required.
    6. Establish Metrics: Define how you will measure success for each task and the overall goal.
    7. Create a Communication Plan: Specify how progress will be reported and to whom.
    8. Review and Adjust: Schedule regular reviews to assess progress and make necessary adjustments.

    By following these steps, you create a clear path from idea to execution.

    Aligning Team Roles and Responsibilities

    Execution plans succeed or fail based on the people involved. Clearly defining roles and responsibilities prevents confusion and ensures accountability. Use a RACI matrix (Responsible, Accountable, Consulted, Informed) to map out who does what. For each task, identify one person who is ultimately accountable for completion. Empower team members with the authority and resources they need to execute. Foster a culture of ownership where individuals feel responsible for outcomes. Regular one-on-one meetings can help address challenges and maintain motivation. When roles are clear, execution becomes smoother and more efficient.

    Resource Allocation and Budgeting

    No execution plan can succeed without adequate resources. Resource allocation involves distributing financial, human, and material resources to support the action plan. Start by estimating the cost of each task, including labor, materials, and overhead. Then, prioritize tasks based on their impact on strategic goals. Use zero-based budgeting to justify every expense. Monitor resource usage against the plan and adjust as needed. Be prepared to reallocate resources if certain tasks require more support. Effective resource management ensures that your execution plan is feasible and sustainable.

    Timeline and Milestones

    Creating a realistic timeline is essential for execution. Break the overall goal into phases and set milestones for each phase. Milestones are significant checkpoints that indicate progress. for instance, a milestone might be ‘complete product prototype’ or ‘launch marketing campaign.’ Use Gantt charts or project scheduling software to visualize dependencies and deadlines. Build in buffer time for unexpected delays. Regularly review the timeline and update it as the project evolves. Timelines keep the team focused and provide a sense of urgency.

    Risk Management in Execution

    Every execution plan faces risks. Proactive risk management identifies potential obstacles and develops mitigation strategies. Start by conducting a risk assessment: list possible risks (e.g., supply chain disruptions, staff turnover, budget overruns) and rate their likelihood and impact. For high-priority risks, create contingency plans. for instance, if a key supplier might fail, identify alternative suppliers in advance. Regularly monitor risk indicators and update your risk register. By anticipating challenges, you can respond quickly and keep your execution on track.

    Monitoring Progress and KPIs

    Monitoring progress is crucial to ensure your execution plan stays on course. Define key performance indicators (KPIs) for each major task and overall goal. Use dashboards to visualize data in real time. Schedule regular progress reviews—weekly for tactical issues, monthly for strategic alignment. During reviews, compare actual performance against targets. Identify variances and root causes. Celebrate achievements and address shortcomings. Use data to make informed decisions about resource reallocation or timeline adjustments. Continuous monitoring turns your execution plan into a dynamic tool for success.

    Communication and Reporting

    Effective communication ensures that everyone stays informed and aligned. Develop a communication plan that specifies what information is shared, with whom, and how often. Use status reports, team meetings, and email updates. Tailor communication to different audiences: executives may need high-level summaries, while team members require detailed task updates. Encourage open feedback and create a culture where issues are raised early. Transparent communication builds trust and facilitates collaboration. Remember, a well-communicated execution plan is more likely to succeed.

    Common Pitfalls and How to Avoid Them

    Even the best execution plans can fail due to common pitfalls. These include lack of clarity, unrealistic timelines, insufficient resources, poor communication, and resistance to change. To avoid these, involve stakeholders in planning, set achievable deadlines, secure commitment for resources, and maintain open channels of communication. Regularly review and adapt the plan. Learn from past failures and incorporate lessons learned. By anticipating these pitfalls, you can build a more resilient execution plan.

    Case Study: Successful Execution in Action

    Consider a tech startup that aimed to launch a new app within six months. They created an execution plan with clear targets, assigned roles, and weekly sprints. They used Agile methodology to adapt quickly. By setting measurable aims like user acquisition and retention rates, they could pivot features based on feedback. Their operational action plan included daily stand-ups and a risk register. Despite initial delays, they launched on time and exceeded their first-month user target by 20%. This case illustrates the power of a well-structured execution plan.

    Conclusion

    Turning ideas into action requires more than enthusiasm; it demands a disciplined execution plan. By understanding the differences between a business plan vs action plan, developing a robust business execution strategy, setting clear business targets, defining measurable business aims, and creating an operational action plan, you can bridge the gap between vision and reality. Remember, execution is an ongoing process of learning and adaptation. Use the tools and frameworks provided in this guide to write your own execution plan and watch your business thrive. Start today—your ideas deserve to become action.

    Frequently Asked Questions

    What is the difference between a business plan and an action plan?

    A business plan is a strategic document outlining long-term goals, market analysis, and financial projections. An action plan is a tactical tool that breaks down specific goals into actionable steps with deadlines and responsibilities. While a business plan provides the ‘why,’ an action plan provides the ‘how.’

    How do I set clear business targets?

    Use the SMART framework: Specific, Measurable, Achievable, Relevant, Time-bound. Involve stakeholders, use historical data, and break annual targets into quarterly and monthly milestones. Ensure targets align with your overall business strategy.

    What are measurable business aims?

    Measurable business aims are quantifiable KPIs that track progress toward goals. Examples include revenue growth, customer satisfaction scores, conversion rates, and operational efficiency metrics. They provide objective evidence of success.

    What is an operational action plan?

    An operational action plan details the daily tasks, resources, timelines, and responsibilities needed to execute a project or initiative. It is a granular plan that guides team members on what to do and when.

    How often should I review my execution plan?

    Review your execution plan regularly—weekly for tactical tasks and monthly for strategic alignment. Use progress data to make adjustments. Frequent reviews keep the plan relevant and responsive to changes.

    Advanced Techniques for Execution Planning

    To elevate your execution plan beyond the basics, incorporate advanced techniques such as OKRs (Objectives and Key Results), Agile project management, and Lean principles. OKRs align team efforts with strategic goals by setting ambitious objectives and tracking measurable key results. for instance, an objective might be ‘Become the market leader in customer satisfaction,’ with key results like ‘Achieve NPS of 70+ by Q4’ and ‘Reduce average response time to under 2 hours.’ Agile methodologies, originally from software development, emphasize iterative progress, flexibility, and cross-functional collaboration. Apply Agile to non-tech projects by breaking work into sprints (typically 2–4 weeks) with daily stand-up meetings and sprint retrospectives. Lean principles focus on eliminating waste and maximizing value. Use value stream mapping to identify bottlenecks in your execution process. These techniques transform your execution plan into a dynamic, responsive system.

    Integrating Technology for Execution

    Modern execution relies heavily on technology. Project management software like Asana, Trello, Monday.com, and Jira provide platforms for task assignment, timeline tracking, and collaboration. Use these tools to create Gantt charts, Kanban boards, and dashboards. Automate repetitive tasks with workflows and integrations. for instance, automatically create tasks from incoming emails or trigger notifications when deadlines approach. Data analytics tools like Tableau or Power BI help visualize KPIs and trends. Communication platforms like Slack or Microsoft Teams keep teams connected. Choose tools that fit your team’s size and complexity. Integrating technology streamlines execution, reduces manual errors, and provides real-time visibility.

    Building a Culture of Accountability

    Accountability is the cornerstone of successful execution. Without it, plans become wishlists. Foster a culture where individuals take ownership of their tasks and outcomes. Start by setting clear expectations during the planning phase. Use regular check-ins, such as weekly one-on-ones, to review progress and address challenges. Implement a performance management system that rewards accountability and addresses underperformance. Encourage transparency by sharing progress openly in team meetings. When mistakes happen, focus on learning rather than blame. A culture of accountability empowers team members to take initiative and drive results.

    Managing Change During Execution

    Execution often requires organizational change, which can meet resistance. Effective change management is essential. Start by communicating the ‘why’ behind the execution plan. Explain how it benefits the team and the company. Involve stakeholders early to gain buy-in. Use Kotter’s 8-Step Change Model: create urgency, form a powerful coalition, create a vision for change, communicate the vision, remove obstacles, create short-term wins, build on the change, and anchor it in corporate culture. Provide training and support to help employees adapt. Celebrate small victories to maintain momentum. By managing change proactively, you reduce resistance and increase the likelihood of successful execution.

    Scaling Execution as Your Business Grows

    As your business expands, execution plans become more complex. Scaling requires standardized processes, delegation, and a strong leadership team. Document your execution playbook so that new team members can quickly understand workflows. Implement scalable project management tools that can handle multiple projects and teams. Develop middle managers who can oversee execution in their departments. Use portfolio management to prioritize initiatives across the organization. Regularly reassess your execution capacity—do you have enough resources to meet growing demands? Scaling execution isn’t just about doing more; it’s about doing more efficiently without sacrificing quality.

    Case Study: Execution in a Non-Profit Organization

    Consider a non-profit aiming to raise $1 million for a community project. They created an execution plan with clear targets: secure 50 corporate sponsors, host three fundraising events, and launch a social media campaign. They assigned roles to volunteers, set monthly milestones, and tracked donations weekly. By using a simple CRM and regular check-ins, they exceeded their goal by 15%. This case highlights that execution principles apply across sectors. The key was breaking down a large goal into manageable tasks and maintaining accountability.

    Common Execution Mistakes and How to Fix Them

    Even experienced leaders make mistakes. Common errors include overcomplicating the plan, setting too many priorities, neglecting to communicate, and failing to adapt. To fix these, simplify your plan by focusing on the top three priorities. Use the Eisenhower Matrix to distinguish urgent vs. important tasks. Communicate the plan repeatedly through multiple channels. Build flexibility into your timeline and budget. Conduct post-mortems after each project to identify what worked and what didn’t. Learning from mistakes turns failures into stepping stones for future success.

    Tools and Templates for Execution Plans

    To get started quickly, use templates and tools. A basic execution plan template includes sections for goal, tasks, owner, deadline, resources, status, and notes. Many project management tools offer pre-built templates for action plans, Gantt charts, and RACI matrices. You can also find free templates online from sources like Smartsheet or Monday.com. Customize these templates to fit your specific needs. Remember, the tool is only as good as the discipline to use it. Invest time in training your team on the chosen tools.

    Measuring Success: Beyond KPIs

    While KPIs are essential, success also includes qualitative factors like team morale, customer satisfaction, and learning outcomes. Use employee engagement surveys, customer feedback, and retrospective meetings to gauge these softer metrics. Balanced Scorecard approach combines financial, customer, internal process, and learning perspectives. for instance, a successful execution plan not only meets revenue targets but also improves team skills and customer loyalty. Celebrate both quantitative and qualitative achievements to motivate your team.

    The Role of Leadership in Execution

    Leaders set the tone for execution. Effective leaders model accountability, communicate vision, and remove obstacles. They empower teams by delegating authority and providing resources. They also stay visible and engaged, attending progress reviews and celebrating wins. Leadership isn’t about micromanaging but about creating an environment where execution can thrive. Invest in leadership development to build a pipeline of capable managers. Strong leadership is the catalyst that turns plans into results.

    Sustaining Momentum Over Time

    Execution is a marathon, not a sprint. To sustain momentum, avoid burnout by pacing your team. Use periodic breaks, celebrate milestones, and rotate challenging tasks. Keep the team motivated by connecting daily work to the larger mission. Regularly revisit the ‘why’ behind the plan. Use visual progress trackers, like a ‘burn-down chart’ or ‘goal thermometer,’ to maintain visibility. Encourage innovation by allowing team members to suggest improvements. Sustained momentum requires continuous energy and focus, but the payoff is consistent progress toward your goals.

    Global and Remote Execution Challenges

    In today’s globalized world, execution often involves remote or distributed teams. Challenges include time zone differences, cultural barriers, and communication gaps. Overcome these by establishing clear communication protocols, using asynchronous tools (e.g., shared documents, recorded updates), and scheduling overlapping work hours. Foster an inclusive culture where all voices are heard. Use video conferencing for important meetings to build rapport. Provide clear documentation and standard operating procedures to ensure consistency. Remote execution requires extra discipline but can be highly effective with the right strategies.

    Continuous Improvement: The Kaizen Approach

    Execution plans should evolve through continuous improvement. The Japanese concept of Kaizen emphasizes small, incremental changes. After each project phase or milestone, conduct a ‘plus/delta’ exercise: what went well (plus) and what could be improved (delta). Implement one or two improvements immediately. Encourage all team members to suggest enhancements. Over time, these small changes compound into significant efficiency gains. Continuous improvement keeps your execution plan fresh and responsive to changing conditions.

    Conclusion: Turning Ideas into Action

    Mastering the art of execution is a lifelong journey. By understanding how to prepare an action plan, distinguishing between a business plan vs action plan, developing a robust business execution strategy, setting clear business targets, defining measurable business aims, and creating an operational action plan, you have the tools to turn any idea into reality. Remember, execution isn’t about perfection; it’s about progress. Start with a solid plan, adapt as you learn, and keep moving forward. Your business success depends on your ability to execute. Now, go make it happen.

    Advanced Execution Metrics and Analytics

    To truly master execution, you must go beyond basic KPIs and embrace advanced metrics and analytics. Leading indicators, such as weekly active users or pipeline velocity, predict future performance. Lagging indicators, like quarterly revenue, confirm outcomes. Use cohort analysis to track behavior over time, and funnel analysis to identify drop-off points in your processes. for instance, in a sales execution plan, track conversion rates at each stage: lead to opportunity, opportunity to proposal, proposal to close. Implement A/B testing to optimize tactics. Use predictive analytics to forecast outcomes and adjust plans proactively. By leveraging data, you can make informed decisions that enhance execution effectiveness.

    Aligning Execution with Company Culture

    Company culture profoundly impacts execution. A culture that values speed, accountability, and collaboration will execute faster. Conversely, a bureaucratic or risk-averse culture can hinder progress. Assess your current culture using surveys or focus groups. Identify cultural barriers to execution, such as silos, fear of failure, or lack of trust. Then, intentionally shape culture through leadership behavior, recognition programs, and communication. For instance, celebrate ‘smart failures’ that resulted in learning. Encourage cross-functional teamwork. When culture aligns with execution goals, employees are naturally motivated to deliver results.

    Execution in Different Business Stages

    Execution plans vary by business lifecycle. In a startup, speed and adaptability are paramount. Plans are often short-term and pivot frequently. Use lean startup methods: build-measure-learn loops, minimum viable products, and rapid experimentation. In a growth-stage company, focus on scaling processes, hiring the right talent, and maintaining quality. Execution plans become more structured with standardized workflows. In mature companies, execution emphasizes efficiency, cost control, and incremental innovation. Use Six Sigma or total quality management. Tailor your execution approach to your stage to maximize effectiveness.

    Legal and Compliance Considerations

    Execution plans must account for legal and regulatory requirements. Depending on your industry, you may need to comply with data protection laws (GDPR, CCPA), labor laws, environmental regulations, or financial reporting standards. Failure to do so can derail execution and lead to fines. Include compliance checks in your task list. Assign a compliance officer or legal counsel to review the plan. for instance, if your execution plan involves launching a new product, ensure it meets safety standards and intellectual property laws. Proactive compliance prevents costly delays and reputational damage.

    Psychological Factors in Execution

    Human psychology plays a significant role in execution. Cognitive biases, such as optimism bias (underestimating time and costs) and confirmation bias (ignoring contrary evidence), can distort planning. To counter these, use reference class forecasting—base estimates on similar past projects. Encourage devil’s advocate perspectives in planning meetings. Motivation factors, like autonomy, mastery, and purpose (as per Daniel Pink’s theory), drive execution. Design tasks that give employees control, opportunities to learn, and a clear sense of purpose. Address fear of failure by creating psychological safety. Understanding psychology helps you design execution plans that people can and want to execute.

    Resource Optimization and Lean Execution

    Lean execution focuses on maximizing value while minimizing waste. Apply the 5S methodology (Sort, Set in Order, Shine, Standardize, Sustain) to organize workspaces and processes. Use value stream mapping to identify non-value-added activities and eliminate them. Implement just-in-time (JIT) principles to reduce inventory and waiting times. for instance, in a manufacturing execution plan, JIT ensures materials arrive exactly when needed, reducing storage costs. In service industries, streamline workflows to reduce handoffs and delays. Lean execution increases efficiency and frees up resources for high-impact activities.

    Case Study: Execution in a Retail Chain

    A retail chain with 200 stores wanted to improve customer satisfaction scores by 10% in one year. Their execution plan included training staff on new service protocols, implementing a feedback system, and rewarding top performers. They set clear targets for each store, assigned regional managers as accountability owners, and tracked scores monthly. By using a centralized dashboard and holding weekly review calls, they achieved a 12% improvement. The key success factors were consistent communication, real-time data, and recognition. This demonstrates how structured execution drives measurable results.

    Handling Execution Failure

    Not all execution plans succeed. When a plan fails, it’s crucial to analyze why without assigning blame. Conduct a post-mortem: what were the goals? what actually happened? what were the root causes? Common reasons include unrealistic timelines, insufficient resources, poor communication, or external shocks. Document lessons learned and update your planning process. for instance, if a product launch failed due to lack of market research, incorporate more customer validation steps in future plans. Failure is a learning opportunity. By handling it constructively, you build resilience and improve future execution.

    Cross-Functional Execution Teams

    Complex execution often requires cross-functional teams. These teams bring together diverse skills—marketing, sales, product, engineering, finance—to achieve a common goal. but, they also face challenges like conflicting priorities and communication gaps. To make cross-functional execution work, establish a clear charter with shared objectives. Use a RACI matrix to clarify roles. Hold regular alignment meetings. Appoint a project manager or scrum master to facilitate. Foster a culture of collaboration by recognizing team achievements rather than individual silo successes. When cross-functional teams execute well, they produce innovative and integrated results.

    Execution Plan Documentation and Version Control

    Documenting your execution plan is critical for consistency and learning. Create a central repository (e.g., shared drive, wiki, or project management tool) where all plan documents are stored. Use version control to track changes. Include a change log that records who made changes, when, and why. This ensures transparency and helps new team members get up to speed. Regularly review and update documentation. Good documentation turns your execution plan into a reusable asset for future projects.

    Training and Development for Execution

    Invest in training to enhance execution capabilities. Offer courses on project management, time management, communication, and problem-solving. Provide on-the-job training through mentoring and shadowing. Develop a ‘execution toolkit’ with templates, checklists, and best practices. for instance, train employees on how to write SMART goals or how to conduct effective stand-up meetings. When your team has the skills to execute, they work more efficiently and confidently. Continuous learning keeps execution sharp.

    Customer-Centric Execution

    Ultimately, execution should serve the customer. Align your execution plan with customer needs and feedback. Use tools like customer journey mapping to identify touchpoints where execution impacts experience. For instance, if your execution plan involves a new website launch, ensure it improves user experience based on usability testing. Gather customer feedback during execution through surveys or beta testing. Adjust your plan based on insights. Customer-centric execution not only meets goals but also builds loyalty and advocacy.

    Environmental and Social Responsibility in Execution

    Modern businesses must consider environmental and social impacts in their execution plans. Incorporate sustainability goals, such as reducing carbon footprint or using eco-friendly materials. Ensure fair labor practices and community engagement. for instance, if your execution plan involves sourcing raw materials, choose suppliers with ethical practices. Communicate your commitment to stakeholders. Responsible execution enhances brand reputation and mitigates risks. It also aligns with growing consumer expectations.

    The Future of Execution: AI and Automation

    Emerging technologies like artificial intelligence and automation are transforming execution. AI can predict project risks, optimize resource allocation, and automate routine tasks. for instance, AI-powered tools can analyze historical data to recommend realistic timelines. Chatbots can handle status updates and reminders. Robotic process automation (RPA) can handle data entry and reporting. Embrace these technologies to augment human capabilities. but, ensure that AI is used ethically and that human oversight remains. The future of execution is human-AI collaboration.

    Final Thoughts: The Execution Mindset

    Execution isn’t just a set of tools; it’s a mindset. Cultivate a bias for action, discipline, and resilience. Prioritize doing over perfecting. Learn from each cycle and keep improving. Surround yourself with people who share this mindset. Remember, every great achievement started with an idea, but it was execution that made it real. By mastering the art of execution, you can turn your business dreams into tangible success. Start your execution plan today, and take the first step toward turning ideas into action.

  • A Simple Guide to SWOT Analysis for Testing New Business Ideas

    A Simple Guide to SWOT Analysis for Testing New Business Ideas

    Introduction

    Before launching any new business idea, it’s crucial to evaluate its potential for success. One of the most effective frameworks for this evaluation is SWOT analysis—a strategic tool that examines Strengths, Weaknesses, Opportunities, and Threats. This guide provides a comprehensive, step-by-step approach to using SWOT analysis for beginners, helping you assess business strengths and weaknesses, identify market threats and opportunities, and ultimately test the viability of your project. Whether you’re an entrepreneur, a student, or a business professional, mastering SWOT analysis will empower you to make informed decisions and increase your chances of success.

    What is SWOT Analysis?

    SWOT analysis is a structured planning method used to evaluate the Strengths, Weaknesses, Opportunities, and Threats involved in a project or business venture. It involves specifying the objective of the business venture and identifying the internal and external factors that are favorable and unfavorable to achieving that objective. The technique is credited to Albert Humphrey, who led a research project at Stanford University in the 1960s and 1970s using data from Fortune 500 companies.

    Internal vs. External Factors

    Internal factors are the strengths and weaknesses inherent to the business or idea. These include resources, capabilities, brand reputation, intellectual property, and operational processes. External factors are opportunities and threats that arise from the market environment, such as economic trends, competition, regulatory changes, and technological advancements. Understanding this distinction is key to conducting a meaningful analysis.

    Why Use SWOT for Testing Business Ideas?

    Using SWOT analysis for testing business ideas helps you systematically evaluate the potential of a concept before committing significant resources. It forces you to consider both the positive and negative aspects, ensuring a balanced perspective. By identifying strengths and opportunities, you can leverage them for competitive advantage. Conversely, recognizing weaknesses and threats allows you to develop mitigation strategies, reducing the risk of failure.

    SWOT Analysis for Beginners

    If you’re new to SWOT analysis, this section will walk you through the basics. The acronym stands for Strengths, Weaknesses, Opportunities, and Threats. Strengths and weaknesses are internal factors within your control, while opportunities and threats are external factors in the market environment. The goal is to identify these four elements for your business idea and then use the insights to make strategic decisions.

    Step 1: Define Your Objective

    Before starting, clearly state the objective of your analysis. for instance, “Evaluate the viability of launching an online tutoring platform.” This objective will guide your data collection and ensure the analysis remains focused.

    Step 2: Gather Information

    Collect data on your business idea, target market, competitors, and industry trends. Use primary research (surveys, interviews) and secondary research (reports, articles). The more accurate your data, the more reliable your SWOT analysis.

    Step 3: Brainstorm Each Category

    List strengths, weaknesses, opportunities, and threats. Be honest and objective. Involve team members or mentors to get diverse perspectives. Use prompts like: What advantages does your idea have? What could be improved? What market trends can you capitalize on? What obstacles do you face?

    Step 4: Analyze and Prioritize

    Review your lists and identify the most critical factors. Prioritize items based on their potential impact and likelihood. This step helps you focus on what matters most.

    Step 5: Develop Strategies

    Use the SWOT matrix to create actionable strategies. for instance, leverage strengths to exploit opportunities (SO strategies), use strengths to overcome threats (ST strategies), address weaknesses to pursue opportunities (WO strategies), and mitigate weaknesses to avoid threats (WT strategies).

    Evaluating Business Opportunities with SWOT

    SWOT analysis is particularly valuable for evaluating business opportunities because it provides a systematic framework to assess the potential of a new venture. By examining both internal and external factors, you can gauge whether an opportunity is worth pursuing.

    Identifying Opportunities

    Opportunities are external factors that could give your business a competitive advantage. Examples include emerging markets, changes in consumer behavior, technological advancements, or favorable regulations. For instance, the rise of remote work created opportunities for online collaboration tools. To identify opportunities, analyze market trends, competitor weaknesses, and customer pain points.

    Assessing Feasibility

    Once you’ve identified opportunities, evaluate whether your business idea can realistically capture them. Consider your resources, capabilities, and market position. A SWOT analysis helps you see if your strengths align with the opportunity or if weaknesses need to be addressed first.

    Case Study: Evaluating a Food Delivery App

    Imagine you’re considering launching a food delivery app focused on healthy meals. Using SWOT, you might identify: Strengths: unique recipe curation, experienced chef team; Weaknesses: limited funding, no brand recognition; Opportunities: growing health-conscious population, partnerships with gyms; Threats: established competitors like Uber Eats, regulatory hurdles. This analysis reveals that while the opportunity exists, you need to address funding and branding weaknesses through strategic partnerships or niche marketing.

    Business Strengths and Weaknesses

    Understanding your business strengths and weaknesses is crucial for strategic planning. Strengths are internal attributes that give you an advantage over competitors, such as a strong brand, loyal customer base, proprietary technology, or skilled workforce. Weaknesses are internal limitations that hinder your performance, such as lack of capital, outdated equipment, or poor location.

    Conducting an Internal Audit

    To identify strengths and weaknesses, perform an internal audit of your business. Evaluate resources (financial, human, intellectual), capabilities (production, marketing, R&D), and processes (efficiency, quality control). Use tools like the VRIO framework (Value, Rarity, Imitability, Organization) to assess whether your resources are sources of sustained competitive advantage.

    Leveraging Strengths

    Once identified, leverage your strengths to maximize opportunities and mitigate threats. for instance, if your strength is a highly skilled R&D team, invest in innovation to stay ahead of competitors. Communicate your strengths in marketing to attract customers and investors.

    Addressing Weaknesses

    Weaknesses should be acknowledged and addressed. Develop action plans to improve or compensate. For instance, if lack of online presence is a weakness, invest in digital marketing. If you have high employee turnover, improve HR practices. Sometimes weaknesses can be turned into strengths through strategic initiatives.

    Market Threats and Opportunities

    Market threats and opportunities are external factors that can impact your business. Opportunities are positive trends that you can exploit, while threats are negative trends that could harm your business. Identifying these factors helps you proactively adapt to the market environment.

    Analyzing the External Environment

    Use PESTLE analysis (Political, Economic, Social, Technological, Legal, Environmental) to systematically scan the macro-environment. for instance, a new data privacy regulation (legal) could be a threat if your business relies on customer data, but an opportunity if you offer compliance solutions. Monitor industry reports, news, and expert opinions to stay informed.

    Responding to Threats

    Once threats are identified, develop contingency plans. for instance, if a new competitor enters the market, consider differentiating your product, improving customer service, or forming strategic alliances. Regularly review threats as the market evolves.

    Capitalizing on Opportunities

    Opportunities should be seized quickly. Allocate resources to projects that align with your strengths and have high potential. for instance, if there’s a growing demand for sustainable products, and your business has eco-friendly practices, launch a green product line. Use first-mover advantage to establish market leadership.

    Testing Business Ideas with SWOT

    Testing business ideas is a critical step before full-scale launch. SWOT analysis provides a structured way to evaluate the viability of your concept by examining internal and external factors. It helps you identify potential pitfalls and refine your idea.

    Creating a SWOT Matrix

    Draw a 2×2 grid with four quadrants: Strengths, Weaknesses, Opportunities, Threats. List your findings in each quadrant. This visual representation makes it easy to see relationships. for instance, a strength in technology can be paired with an opportunity in digital transformation.

    Validating Assumptions

    Your SWOT analysis is only as good as the assumptions behind it. Test your assumptions through market research, prototyping, or minimum viable product (MVP) launches. For instance, if you assume a strength is your unique feature, validate it with customer feedback. Adjust your SWOT accordingly.

    Refining Your Idea

    Based on your SWOT analysis, refine your business idea. If weaknesses are too severe, consider pivoting. If opportunities are large, double down. for instance, if your idea has strong opportunities but weak execution capability, partner with a more experienced team. The goal is to create a viable business model that maximizes strengths and opportunities while minimizing weaknesses and threats.

    Project Viability Assessment

    Project viability assessment determines whether a business idea is worth pursuing. SWOT analysis is a key component of this assessment, but it should be complemented with other tools like financial projections, market analysis, and risk assessment.

    Financial Viability

    Evaluate the financial feasibility of your project. Estimate startup costs, revenue streams, break-even point, and return on investment. Use your SWOT to identify potential cost advantages (strengths) or financial risks (weaknesses). for instance, if you have strong supplier relationships, you may get better pricing.

    Market Viability

    Assess market demand, size, and growth potential. Use SWOT opportunities to gauge market attractiveness. For instance, if your idea targets a niche market with high growth, it’s more viable. Conversely, if the market is saturated (threat), you need a strong differentiation.

    Operational Viability

    Consider whether you have the operational capability to execute the idea. This includes technology, talent, and processes. Use SWOT strengths and weaknesses to evaluate. If you lack key skills, consider hiring or outsourcing. If your operations are efficient, that’s a strength.

    Strategic Planning with SWOT

    SWOT analysis isn’t just for evaluation; it’s a strategic planning tool. Once you have your SWOT, you can develop strategies that align with your goals. The SWOT matrix helps generate four types of strategies: SO (strengths-opportunities), WO (weaknesses-opportunities), ST (strengths-threats), and WT (weaknesses-threats).

    SO Strategies

    Leverage internal strengths to capitalize on external opportunities. Example: If your strength is a strong brand and the opportunity is a growing market, launch a new product under your brand. This is the most favorable strategy.

    WO Strategies

    Improve weaknesses to pursue opportunities. Example: If you lack digital marketing skills (weakness) but there’s a growing online market (opportunity), invest in training or hire a specialist.

    ST Strategies

    Use strengths to mitigate threats. Example: If a competitor lowers prices (threat) and you have superior customer service (strength), emphasize service quality to retain customers.

    WT Strategies

    Minimize weaknesses and avoid threats. Example: If you have high debt (weakness) and an economic downturn (threat), focus on cost-cutting and debt reduction. This is a defensive strategy.

    Common Mistakes in SWOT Analysis

    Even experienced professionals can make mistakes when conducting SWOT analysis. Being aware of these pitfalls will help you produce a more accurate and useful analysis.

    Overly Broad Lists

    Listing too many items without prioritization dilutes focus. Limit each quadrant to 5-10 key factors. Use criteria like impact and likelihood to prioritize. for instance, instead of listing “good customer service” generically, specify “24/7 live chat support with 95% satisfaction rate.”

    Confusing Internal and External Factors

    Strengths and weaknesses are internal; opportunities and threats are external. A common mistake is listing a strength as an opportunity. For instance, “growing market” is an opportunity, not a strength. Keep categories distinct.

    Lack of Evidence

    SWOT should be based on data, not gut feelings. Support each item with evidence. for instance, if you claim a strength is “low cost structure,” provide data on your cost per unit compared to competitors.

    Ignoring Interconnections

    Factors in one quadrant can affect others. for instance, a strength (strong brand) can help you exploit an opportunity (new market). A weakness (lack of capital) can make you vulnerable to a threat (economic downturn). Analyze these interactions.

    Real-World Examples of SWOT Analysis

    To illustrate the practical application of SWOT analysis, let’s examine two real-world examples: a startup and an established company. These examples show how SWOT can be used for testing business ideas and strategic planning.

    Example 1: A Tech Startup (Uber)

    When Uber was testing its business idea, a SWOT analysis might have looked like this: Strengths: innovative technology, first-mover advantage, strong network effects; Weaknesses: regulatory challenges, negative press, high driver turnover; Opportunities: growing gig economy, urbanization, smartphone penetration; Threats: established taxi industry, legal battles, competition from Lyft. Uber leveraged its strengths (technology, network effects) to exploit opportunities (urbanization) and used strategies like lobbying to address threats.

    Example 2: A Retail Company (Target)

    Target’s SWOT analysis: Strengths: strong brand, exclusive designer partnerships, efficient supply chain; Weaknesses: higher prices compared to Walmart, limited international presence; Opportunities: e-commerce growth, sustainability trends, expansion into Canada (though later exited); Threats: Amazon’s dominance, economic downturns, changing consumer preferences. Target used its strengths (brand, partnerships) to pursue opportunities (e-commerce) and addressed weaknesses by improving online offerings.

    Advanced SWOT Techniques

    For deeper analysis, consider advanced variations of SWOT. These techniques add layers of insight and can be particularly useful for complex business ideas.

    TOWS Analysis

    TOWS is a variant that emphasizes the external environment first. You list opportunities and threats, then identify strengths and weaknesses that can be used to address them. This approach is more proactive and market-oriented.

    Weighted SWOT

    Assign weights to each factor based on importance (e.g., 1-5) and rate your performance (e.g., 1-5). Multiply weight by rating to get a score. This quantifies the analysis and helps prioritize. for instance, a strength with high weight and high rating is critical to leverage.

    Dynamic SWOT

    Recognize that SWOT factors change over time. Create a timeline for your analysis: current state, 1-year, 3-year. This helps anticipate future opportunities and threats. For instance, a threat like new regulation may not be imminent but could become significant later.

    Integrating SWOT with Other Tools

    SWOT analysis is most powerful when combined with other strategic frameworks. Integration provides a more holistic view of your business idea’s viability.

    Porter’s Five Forces

    Use Porter’s Five Forces to analyze industry competition: threat of new entrants, bargaining power of buyers, bargaining power of suppliers, threat of substitutes, and industry rivalry. Combine with SWOT to see how your strengths and weaknesses affect these forces. for instance, if you have a strong brand (strength), it reduces buyer power.

    PESTLE Analysis

    PESTLE examines Political, Economic, Social, Technological, Legal, and Environmental factors. Use it to identify opportunities and threats in the macro-environment. Then, use SWOT to see how your internal factors align. For instance, a technological advancement (opportunity) can be exploited if you have strong R&D (strength).

    Business Model Canvas

    The Business Model Canvas describes how a company creates, delivers, and captures value. Use SWOT to evaluate each building block (e.g., value proposition, customer segments). for instance, if your value proposition is strong (strength), but customer segments are shrinking (threat), you may need to pivot.

    SWOT Analysis Template

    To help you get started, here’s a simple SWOT analysis template. Fill in each quadrant with your findings. Use the questions below as prompts.

    Strengths Weaknesses
    What do you do well?
    What unique resources do you have?
    What do others see as your strengths?
    What could you improve?
    Where do you have fewer resources?
    What are others likely to see as weaknesses?
    Opportunities Threats
    What opportunities are open to you?
    What trends can you take advantage of?
    How can you turn strengths into opportunities?
    What threats could harm you?
    What is your competition doing?
    What threats do your weaknesses expose you to?

    Frequently Asked Questions

    What is the main purpose of SWOT analysis?

    The main purpose is to help organizations and individuals identify internal strengths and weaknesses, and external opportunities and threats, to make informed strategic decisions. It provides a clear framework for evaluating a project or business idea’s potential.

    How often should I update my SWOT analysis?

    SWOT analysis should be updated regularly, at least annually or whenever there are significant changes in your internal or external environment. For dynamic industries, consider quarterly updates to stay responsive.

    Can SWOT analysis be used for personal development?

    Yes, SWOT analysis is versatile and can be applied to personal career planning, skill assessment, and goal setting. for instance, you can analyze your personal strengths (e.g., communication skills), weaknesses (e.g., public speaking), opportunities (e.g., industry growth), and threats (e.g., automation).

    What are the limitations of SWOT analysis?

    SWOT analysis can be subjective if not based on data. It may oversimplify complex situations and doesn’t prioritize factors. It also doesn’t provide solutions; it only identifies factors. so, it should be used with other analytical tools.

    How do I prioritize factors in SWOT?

    Prioritize based on impact and likelihood. Use a scoring system (e.g., 1-5 for impact and probability) and multiply to get a priority score. Focus on factors with the highest scores. Also consider urgency and alignment with your objectives.

    Conclusion

    SWOT analysis is an invaluable tool for testing new business ideas. By systematically evaluating strengths, weaknesses, opportunities, and threats, you can gain a comprehensive understanding of your venture’s potential. This guide has provided a thorough overview, from basic concepts to advanced techniques, ensuring you have the knowledge to apply SWOT effectively. Remember to base your analysis on solid data, avoid common pitfalls, and integrate SWOT with other strategic frameworks. Whether you’re a beginner or an experienced entrepreneur, mastering SWOT analysis will enhance your decision-making and increase your chances of success. Start your SWOT analysis today and unlock the full potential of your business ideas.

    In this continuation, we dive deeper into advanced applications, real-world case studies, and practical exercises to ensure you can master SWOT analysis for testing business ideas. The following sections expand on the foundational knowledge provided earlier, offering additional depth and actionable insights.

    Conducting a Competitive SWOT Analysis

    Competitive SWOT analysis involves evaluating your competitors’ strengths, weaknesses, opportunities, and threats to gain a strategic advantage. By understanding the competitive landscape, you can identify gaps in the market and position your business idea more effectively. Start by selecting key competitors and gathering information on their products, market share, customer reviews, and financial performance. Then, create a SWOT matrix for each competitor. for instance, if a competitor has strong brand loyalty (strength) but poor customer service (weakness), you can exploit that weakness by offering superior support. Additionally, look for opportunities that competitors are missing, such as underserved customer segments or emerging technologies. Threats from competitors include price wars, patent filings, or aggressive marketing campaigns. Use this analysis to refine your own SWOT and develop strategies that capitalize on competitors’ vulnerabilities while defending against their strengths.

    Analyzing Competitor Strengths

    Competitor strengths are internal attributes that give them an advantage. These could include a well-known brand, proprietary technology, economies of scale, or a loyal customer base. For instance, Apple’s strength lies in its ecosystem and brand prestige. When evaluating your business idea, consider how your strengths compare. If your competitor has a strong patent portfolio, you may need to innovate around it or seek licensing. Use tools like benchmarking to measure your performance against theirs. Remember that strengths are relative; a competitor’s strength can become a weakness if it makes them complacent or slow to adapt.

    Exploiting Competitor Weaknesses

    Competitor weaknesses are areas where they underperform. Common weaknesses include poor customer service, outdated technology, limited product range, or high prices. for instance, if a competitor has a reputation for late deliveries, you can emphasize your reliable shipping. Conduct mystery shopping or read online reviews to uncover weaknesses. Then, adjust your value proposition to highlight how you address these pain points. Be careful not to overstate your own capabilities; ensure you can deliver on your promises.

    Identifying Market Gaps

    Market gaps are opportunities that competitors have overlooked. These could be unmet customer needs, underserved geographic areas, or new use cases for existing products. For instance, while many coffee shops focus on urban areas, a gap may exist in suburban neighborhoods. Use your competitive SWOT to spot such gaps. If competitors are all targeting millennials, consider Gen Z or older demographics. Validate these gaps through surveys or pilot tests. A successful business idea often fills a gap that competitors have ignored.

    SWOT Analysis for Service-Based Businesses

    Service-based businesses, such as consulting firms, salons, or cleaning services, have unique characteristics that influence SWOT analysis. Unlike product-based businesses, services are intangible, perishable, and often require direct interaction with customers. Strengths might include a highly skilled team, excellent reputation, or personalized service. Weaknesses could be dependence on key employees, difficulty scaling, or variable quality. Opportunities may arise from trends like remote services (e.g., virtual consulting) or niche specialization. Threats include new entrants with lower prices, technological disruption (e.g., AI replacing certain services), or regulatory changes. When testing a service business idea, focus on the customer experience and operational consistency. for instance, a mobile dog grooming service might list strengths as convenience and low overhead, weaknesses as weather dependency, opportunities as pet humanization trends, and threats as established brick-and-mortar groomers. Use these insights to design a service that stands out.

    Importance of Customer Feedback

    For service businesses, customer feedback is a vital source of SWOT data. Positive reviews highlight strengths, while complaints reveal weaknesses. Encourage feedback through surveys, follow-up emails, or online platforms. Analyze patterns: if multiple customers mention slow response times, that’s a weakness to address. Also, monitor feedback about competitors to identify opportunities. For instance, if customers complain about impersonal service from competitors, you can emphasize a personal touch.

    Managing Intangible Assets

    Service businesses rely heavily on intangible assets like reputation, expertise, and relationships. These are difficult to quantify but crucial for SWOT. Strengths like a strong brand or trusted advisors can be leveraged. Weaknesses like lack of online presence can be improved through digital marketing. Opportunities might involve building thought leadership through content marketing. Threats include negative reviews spreading quickly on social media. Develop strategies to protect and enhance your intangible assets.

    SWOT Analysis for Product-Based Businesses

    Product-based businesses, such as manufacturing or retail, focus on tangible goods. Their SWOT analysis often emphasizes supply chain, inventory, and product differentiation. Strengths might include proprietary technology, efficient production, or strong distribution channels. Weaknesses could be high production costs, reliance on a single supplier, or seasonality. Opportunities may come from new materials, e-commerce growth, or customization trends. Threats include commodity price fluctuations, copycat products, or changing consumer preferences. for instance, a startup making eco-friendly water bottles might have strengths in sustainable materials and design, weaknesses in higher price point and limited production capacity, opportunities in growing environmental awareness and corporate partnerships, and threats from established brands like Nalgene. Testing such an idea requires prototyping, cost analysis, and market testing.

    Supply Chain Considerations

    Supply chain factors are critical in product SWOT. Strengths include reliable suppliers, just-in-time inventory, or vertical integration. Weaknesses might be single-source dependencies or long lead times. Opportunities could involve nearshoring to reduce costs or adopting blockchain for traceability. Threats include trade tariffs, natural disasters, or supplier bankruptcies. Map your supply chain and identify vulnerabilities. For instance, if your product relies on a rare mineral, consider alternative materials or stockpiling.

    Product Lifecycle Management

    Products go through lifecycle stages: introduction, growth, maturity, decline. Each stage presents different SWOT factors. In introduction, strengths might be innovation, weaknesses are lack of awareness, opportunities are early adopters, threats are imitators. In maturity, strengths are brand loyalty, weaknesses are market saturation, opportunities are line extensions, threats are price competition. Tailor your SWOT to the stage of your product idea. For a new product, focus on building awareness and distribution.

    Using SWOT for Risk Management

    SWOT analysis is an effective risk management tool. By identifying threats and weaknesses, you can develop mitigation strategies. Begin by listing all potential risks from your SWOT. For each risk, assess its likelihood and impact. Then, create a risk matrix. For high-likelihood, high-impact risks, develop contingency plans. for instance, if a threat is a new regulation that could ban your product, plan to adapt your product or diversify into other markets. If a weakness is lack of funding, seek investors or reduce costs. Opportunities can also be risk mitigators; for instance, a partnership opportunity could provide resources to counter a threat. Regularly review your risk management plan as conditions change.

    Identifying Critical Weaknesses

    Critical weaknesses are those that could cause business failure if not addressed. Examples include cash flow problems, lack of intellectual property protection, or key person dependency. Use SWOT to flag these. For each critical weakness, develop a specific action plan. For instance, if you lack patent protection, file provisional patents or use trade secrets. If you depend on one founder, cross-train employees or create standard operating procedures.

    Monitoring Threats

    Threats evolve, so continuous monitoring is essential. Set up alerts for industry news, competitor moves, and regulatory changes. Use tools like Google Alerts or subscription services. for instance, if a threat is a potential trade war, monitor tariff announcements. Create a threat register that logs each threat, its status, and response actions. Update your SWOT accordingly. Being proactive reduces surprises.

    SWOT Analysis for Digital Products

    Digital products, such as apps, software, or online courses, have unique SWOT considerations. Strengths might include low marginal cost, global reach, and data analytics capabilities. Weaknesses could be high initial development cost, rapid obsolescence, or cybersecurity vulnerabilities. Opportunities include platform ecosystems (e.g., app stores), freemium models, and AI integration. Threats include piracy, platform dependency (e.g., Apple’s App Store policies), and intense competition. for instance, a meditation app idea might have strengths in unique content and user experience, weaknesses in high churn rates, opportunities in corporate wellness programs, and threats from established apps like Headspace. Testing a digital product often involves building a minimum viable product (MVP) and measuring user engagement.

    User Acquisition Strategies

    Digital products rely on user acquisition. SWOT helps identify effective channels. Strengths might include viral features or strong SEO. Weaknesses could be low brand awareness. Opportunities include influencer partnerships or app store optimization. Threats include changes in algorithms or ad costs. Use your SWOT to choose channels that leverage strengths and opportunities. For instance, if your strength is engaging content, invest in content marketing.

    Monetization Models

    Choose a monetization model that aligns with your SWOT. Subscription models provide recurring revenue but require high value to retain users. Freemium models attract users but need conversion strategies. Advertising models rely on scale. Assess each model’s fit: if your strength is a large user base, advertising might work; if your weakness is low retention, subscriptions may fail. Opportunities like in-app purchases can be tested. Threats include user resistance to ads or subscription fatigue.

    SWOT Analysis for Social Enterprises

    Social enterprises aim to achieve social or environmental goals while being financially sustainable. Their SWOT analysis includes both business and mission-related factors. Strengths might include a compelling mission, community support, or grant funding. Weaknesses could be limited business expertise, dependence on volunteers, or mission drift. Opportunities include impact investing, corporate partnerships, or government contracts. Threats include economic downturns affecting donations, competition from for-profits, or regulatory changes in non-profit status. for instance, a social enterprise selling upcycled products might have strengths in storytelling and sustainability, weaknesses in higher costs, opportunities in eco-conscious consumer trends, and threats from cheap fast fashion. Testing such an idea requires balancing mission and margin.

    Measuring Impact

    Social enterprises must measure both financial and social returns. Use SWOT to identify impact metrics that align with strengths. For instance, if your strength is community engagement, measure volunteer hours or local jobs created. Weaknesses might be lack of data collection systems. Opportunities include using technology for impact tracking. Threats include greenwashing accusations. Develop a theory of change that links activities to outcomes.

    Funding Strategies

    Funding for social enterprises comes from grants, impact investors, or earned revenue. SWOT helps choose the right mix. Strengths like a strong track record can attract grants. Weaknesses like small scale may limit investor interest. Opportunities include crowdfunding or social impact bonds. Threats include donor fatigue or changes in government priorities. Diversify funding sources to reduce risk.

    Case Study: Airbnb’s SWOT Analysis

    Airbnb disrupted the hospitality industry. A retrospective SWOT analysis reveals key factors. Strengths: unique inventory (homes), trust-building features (reviews), and global network effects. Weaknesses: regulatory challenges, inconsistent quality, and dependence on hosts. Opportunities: expansion into experiences, business travel, and luxury rentals. Threats: hotel industry backlash, local regulations, and competition from Booking.com. Airbnb leveraged its strengths to exploit opportunities (e.g., launching Experiences) and addressed weaknesses through host education and insurance programs. This case shows how SWOT can guide strategic decisions even for established companies.

    Lessons for Startups

    From Airbnb, startups learn to: embrace unique strengths (peer-to-peer model), anticipate regulatory threats, and continuously innovate to stay ahead. Use SWOT to identify your own unique value proposition and potential obstacles. Test assumptions early; Airbnb tested their concept by renting air mattresses during a conference.

    Case Study: Tesla’s SWOT Analysis

    Tesla’s SWOT shows a company with immense strengths but significant threats. Strengths: innovative technology, brand as a sustainability leader, and vertical integration (batteries, software). Weaknesses: production bottlenecks, high vehicle prices, and CEO dependency. Opportunities: energy storage market, autonomous driving, and expansion into mass market (Model 3). Threats: established automakers entering EV space, battery supply constraints, and regulatory changes. Tesla used its strengths (technology) to pursue opportunities (energy) and addressed weaknesses by building Gigafactories. This analysis highlights the importance of balancing innovation with operational excellence.

    Key Takeaways

    Tesla’s example shows that SWOT must be dynamic. As the company grows, new weaknesses and threats emerge. Regularly update your SWOT and adapt strategies. For your business idea, consider how you can create a similar moat through technology or brand.

    Common Pitfalls in SWOT Analysis and How to Avoid Them

    Even with good intentions, SWOT analysis can go wrong. Here are common pitfalls and solutions.

    Pitfall: Confirmation Bias

    We tend to notice information that confirms our beliefs. To avoid, involve diverse perspectives and use objective data. Challenge assumptions by asking “What if we’re wrong?”

    Pitfall: Overlooking External Factors

    Focusing too much on internal factors can miss critical external changes. Use PESTLE to ensure comprehensive external analysis. Set aside dedicated time for environmental scanning.

    Pitfall: Lack of Action

    A SWOT is useless without action. After completing the analysis, immediately develop strategies and assign responsibilities. Create a timeline and review progress.

    Pitfall: Outdated Analysis

    Markets change quickly. Schedule regular SWOT reviews. For fast-moving industries, consider monthly updates. Use the analysis as a living document.

    Advanced Strategic Frameworks Using SWOT

    Combine SWOT with other frameworks for deeper insights.

    SOAR Analysis

    SOAR (Strengths, Opportunities, Aspirations, Results) is a positive alternative that focuses on strengths and opportunities. It avoids dwelling on weaknesses and threats. Use it when you want to inspire innovation and growth. for instance, instead of listing threats, focus on aspirations for the future.

    SWOT-PESTLE Integration

    Create a matrix that combines SWOT and PESTLE. For each PESTLE factor (Political, Economic, etc.), list corresponding opportunities and threats. Then, align internal strengths and weaknesses. This ensures a macro-micro view. For instance, a political change (e.g., new trade deal) may create opportunities that require specific strengths to exploit.

    SWOT for Scenario Planning

    Use SWOT to develop multiple scenarios. For each scenario, identify how your strengths and weaknesses play out. for instance, in a best-case scenario (strong economy, low competition), your strengths are amplified. In a worst-case scenario (recession, new competitor), your weaknesses become critical. Develop contingency plans for each scenario.

    Conclusion

    This extended guide has provided an in-depth exploration of SWOT analysis for testing new business ideas. From foundational concepts to advanced applications, you now have a comprehensive toolkit to evaluate your venture’s viability. Remember that SWOT isn’t a one-time exercise but an ongoing process. As you gather more data and market feedback, refine your analysis. Use the insights to make informed decisions, mitigate risks, and seize opportunities. Whether you’re a budding entrepreneur or a seasoned strategist, mastering SWOT analysis will significantly enhance your ability to test and launch successful business ideas. Start applying these principles today and turn your vision into reality.
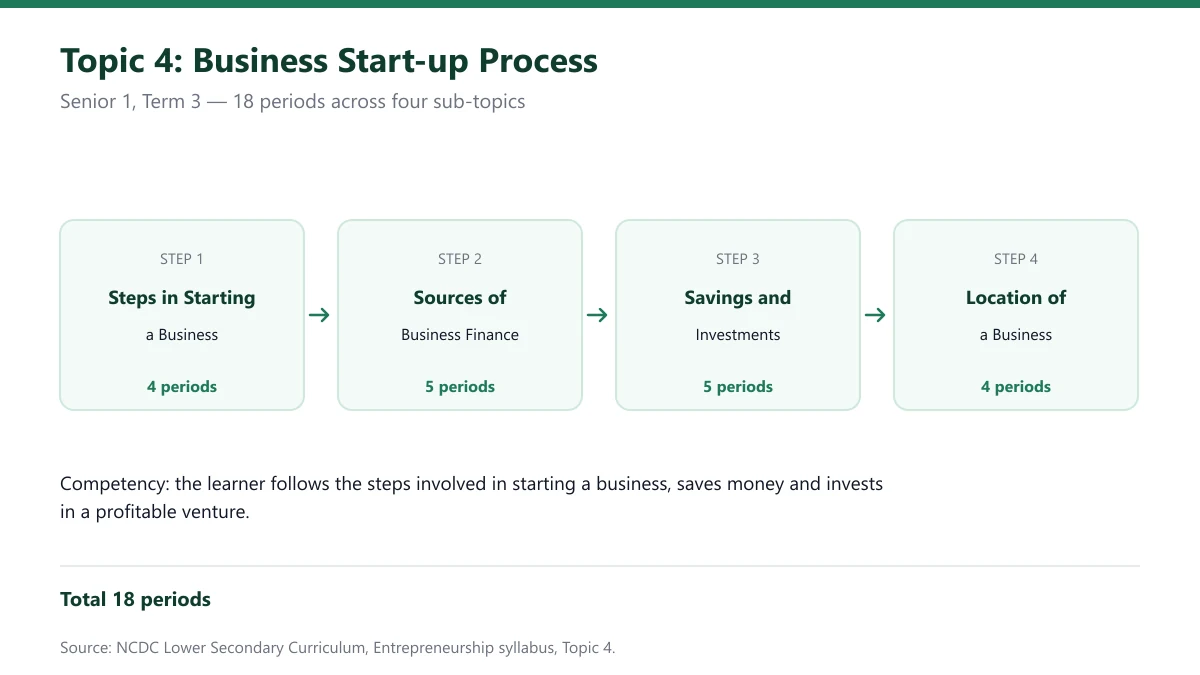
  • Knowing When to Seek External Support for Your Struggling Business: A Comprehensive Guide

    Knowing When to Seek External Support for Your Struggling Business: A Comprehensive Guide

    Introduction

    Every entrepreneur dreams of building a thriving, sustainable business. but, the reality is that many businesses face periods of struggle, whether due to market shifts, operational inefficiencies, or unexpected crises. The difference between a business that survives and one that fails often hinges on the ability to recognize when internal efforts are no longer enough and external support is needed. This comprehensive guide explores the critical juncture of knowing when to seek external support for your struggling business, delving into the signs of distress, the types of support available, and how to leverage them effectively. By understanding the role of business support systems, business advisory services, and entrepreneur mentorship, you can navigate your business back to stability and growth.

    Topic 1: Recognizing the Signs That Your Business Is Failing

    One of the most challenging aspects of running a business is objectively assessing its health. Many entrepreneurs fall into the trap of optimism bias, ignoring red flags until it’s too late. Recognizing the signs a business is failing is the first step toward seeking help. These signs often manifest in financial, operational, and cultural dimensions, and they require immediate attention.

    Financial Red Flags

    • Persistent Negative Cash Flow: If your business consistently spends more than it earns, it’s a clear indicator of trouble. Negative cash flow eats into reserves and can lead to insolvency. Monitoring cash flow statements monthly is crucial; if you see a pattern of deficits, it’s time to seek cash flow management support.
    • Declining Profit Margins: Even if revenue is stable or growing, shrinking margins suggest inefficiencies or pricing issues. This could be due to rising costs, increased competition, or poor cost control. A margin decline of more than 10% year-over-year warrants external analysis.
    • Increasing Debt Levels: Relying on credit cards, loans, or supplier credit to cover operational expenses is a dangerous spiral. High debt-to-equity ratios (above 2:1) indicate over-leverage and potential default risk.
    • Delayed Payments to Vendors and Employees: When you start stretching payables or missing payroll, your business is in crisis. This damages relationships and can lead to legal action or loss of key staff.
    • Inventory Buildup or Stockouts: Excess inventory ties up cash, while frequent stockouts indicate poor demand forecasting or supply chain issues. Both signal operational problems that require expert intervention.

    Operational and Strategic Indicators

    • Loss of Key Customers: If major clients are leaving or reducing orders, it’s a sign of dissatisfaction or market shift. Customer churn rates above 10% annually are concerning.
    • Employee Turnover and Low Morale: High turnover (above 15%) and disengaged employees often reflect poor leadership or financial instability. Talented staff leave first, leaving you with a weakened team.
    • Stagnant or Declining Sales: Flat or dropping sales despite market growth indicates competitive disadvantage or product-market fit issues. Analyze if your sales pipeline is shrinking.
    • Missed Targets and Strategic Drift: Consistently failing to meet budgets or strategic goals suggests planning flaws or execution gaps. If you’re constantly pivoting without clear direction, external guidance is needed.

    Psychological and Emotional Signs

    • Overwhelm and Decision Fatigue: When you feel exhausted by daily decisions and avoid strategic thinking, it’s a sign you need support. Entrepreneurship is lonely, and burnout can cloud judgment.
    • Isolation: If you’re reluctant to discuss business issues with peers or advisors, you may be in denial. Sharing struggles with a mentor can provide clarity.
    • Loss of Passion: When the business feels like a burden rather than a mission, it’s time to reassess. External support can reignite purpose and provide fresh perspective.

    “The most dangerous phrase in business is: ‘We’ve always done it this way.’” – Grace Hopper. Recognizing when your usual methods fail is the first step toward recovery.

    Topic 2: The Role of Business Support Systems

    Business support systems encompass a range of resources—from government programs to private networks—designed to help businesses overcome challenges. These systems provide infrastructure, funding, and expertise that individual entrepreneurs often lack. Understanding how to access and leverage these systems can be a lifeline for struggling businesses.

    Types of Business Support Systems

    Type Description Examples
    Government Agencies Offer grants, loans, and counseling SBA (US), Business Link (UK)
    Nonprofit Organizations Provide free or low-cost consulting SCORE, Small Business Development Centers
    Industry Associations Networking and best practices Chamber of Commerce, Trade Groups
    Incubators & Accelerators Structured programs for growth Y Combinator, Techstars
    Peer Networks Mastermind groups and forums EO, Vistage

    How Support Systems Help Struggling Businesses

    Support systems offer several benefits: they provide access to capital through grants or low-interest loans, offer educational resources on financial management, and create accountability structures. For instance, the SBA’s 7(a) loan program can help with cash flow, while SCORE mentors offer free advice on turnaround strategies. Engaging with these systems early can prevent bankruptcy and facilitate restructuring.

    Case Study: Using a Support System for Turnaround

    A small manufacturing firm facing declining sales joined a local business accelerator. Through the program, they received mentorship on lean operations, connected with a supply chain consultant, and secured a grant for technology upgrades. Within 18 months, they reduced costs by 20% and increased revenue by 15%. This demonstrates how structured support can reverse decline.

    Topic 3: Leveraging Business Advisory Services

    Business advisory services are professional consulting offerings that provide expert analysis and recommendations. Unlike generic support systems, advisors bring specialized knowledge in areas like finance, strategy, and operations. For a struggling business, hiring an advisor can be the most effective way to diagnose problems and implement solutions.

    When to Engage a Business Advisor

    • Financial Distress: If cash flow is critical, a financial advisor can help with debt restructuring, cost reduction, and cash flow forecasting.
    • Strategic Pivot: When your market is shrinking, a strategy advisor can help identify new opportunities or reposition your brand.
    • Operational Inefficiencies: An operations consultant can streamline processes, reduce waste, and improve productivity.
    • Leadership Gaps: If you lack certain skills (e.g., digital marketing, HR), an advisor can fill the gap temporarily.
    • Preparing for Sale or Investment: Advisors can help clean up financials and improve valuation.

    How to Choose the Right Advisor

    Selecting an advisor requires due diligence. Look for experience in your industry, a track record of turnarounds, and references. Ensure they have expertise in cash flow management support if that’s your primary need. Avoid advisors who promise quick fixes; sustainable recovery takes time. Also, consider their communication style and cultural fit.

    Cost vs. Benefit Analysis

    While advisors charge fees (hourly or project-based), the return on investment can be substantial. A good advisor can identify savings that far exceed their cost. for instance, a consultant might find that renegotiating supplier contracts saves $50,000 annually, while their fee is $10,000. but, if your business is barely surviving, some advisors offer deferred payment or equity arrangements.

    Topic 4: The Power of Entrepreneur Mentorship

    Entrepreneur mentorship involves a more experienced business owner guiding you through challenges. Unlike advisory services, mentorship is often relationship-based, ongoing, and holistic. A mentor can provide emotional support, accountability, and practical wisdom that textbooks don’t teach.

    Benefits of Mentorship for Struggling Businesses

    • Objective Perspective: Mentors see blind spots you miss. They can challenge assumptions and offer alternative strategies.
    • Emotional Resilience: Running a struggling business is stressful. A mentor who has been through similar crises can normalize your experience and boost morale.
    • Network Access: Mentors often introduce you to potential investors, partners, or customers, opening doors that were closed.
    • Accountability: Regular check-ins ensure you follow through on action plans. This is crucial when you’re overwhelmed.
    • Skill Development: Mentors can teach you negotiation, leadership, and financial skills in real-time.

    Finding the Right Mentor

    Look for mentors who have successfully navigated a business crisis. They should be willing to be candid and committed to your success. Platforms like SCORE, MicroMentor, and industry associations can connect you. Also, consider peer mentorship groups like Vistage, where you get multiple perspectives.

    Mentorship vs. Consulting: A Comparison

    Aspect Mentorship Consulting
    Relationship Long-term, informal Short-term, formal
    Focus Personal and professional growth Specific problem-solving
    Cost Often free or low-cost Paid, often high
    Depth Holistic Specialized
    Accountability Voluntary Contractual

    Topic 5: Cash Flow Management Support

    Cash flow is the lifeblood of any business, and mismanagement is a leading cause of failure. Cash flow management support involves strategies and tools to monitor, forecast, and optimize cash inflows and outflows. External support in this area can be transformative.

    Key Cash Flow Challenges

    • Late Payments: Customers delaying invoices creates cash gaps. Support can include invoice factoring or automated reminders.
    • Overinvestment in Inventory: Tying up cash in slow-moving stock. Support helps with just-in-time inventory systems.
    • High Overhead: Fixed costs that don’t align with revenue. Support identifies cost-cutting opportunities.
    • Seasonal Fluctuations: Uneven revenue cycles. Support provides line of credit or revenue smoothing strategies.

    External Support Options for Cash Flow

    Financial advisors can create 13-week cash flow forecasts to predict shortfalls. They can also negotiate with lenders for loan modifications or with suppliers for extended terms. Additionally, business support systems like the SBA offer microloans and disaster assistance. Technology solutions, such as QuickBooks or Xero, can automate tracking, but expert setup ensures accuracy.

    Implementing a Cash Flow Turnaround

    A step-by-step approach: (1) Conduct a cash flow audit to identify leaks. (2) Prioritize receivables: offer discounts for early payment. (3) Reduce expenses: renegotiate rent, cut non-essential services. (4) Secure short-term financing if needed. (5) Monitor weekly. External support can guide this process and keep you on track.

    Topic 6: Strategic Planning for Business Recovery

    When a business is struggling, it’s tempting to react impulsively. but, a structured strategic plan is essential for recovery. External support can help you create a realistic turnaround plan that addresses root causes.

    Elements of a Turnaround Plan

    • Situation Analysis: SWOT analysis to identify strengths, weaknesses, opportunities, and threats.
    • Financial Restructuring: Debt consolidation, cost reduction, and revenue enhancement.
    • Operational Improvements: Process reengineering, technology adoption.
    • Marketing and Sales: Refocus on profitable customer segments.
    • Milestones and Metrics: Clear KPIs to track progress.

    Role of External Advisors in Planning

    Advisors bring objectivity and experience. They can facilitate planning sessions, challenge assumptions, and provide templates. They also help with scenario planning—what if sales drop further? What if a new competitor enters? This prepares you for uncertainties.

    Topic 7: Legal and Financial Restructuring

    Sometimes, a struggling business needs legal intervention to survive. This includes debt restructuring, bankruptcy alternatives, or changes in ownership. External support from lawyers, accountants, and financial advisors is critical.

    Debt Restructuring Options

    • Debt Consolidation: Combining multiple debts into one with lower interest.
    • Debt Forgiveness: Negotiating with creditors to accept less than owed.
    • Equity Financing: Selling a stake in the business to raise capital.
    • Chapter 11 Bankruptcy (US): Reorganization under court protection.

    When to Seek Legal Advice

    If you’re facing lawsuits, creditor pressure, or insolvency, consult a business attorney immediately. They can advise on the best course of action and protect your personal assets. Many offer free initial consultations.

    Topic 8: Building Resilience Through External Support

    Seeking external support isn’t a sign of weakness; it’s a strategic move. Businesses that leverage business advisory services, entrepreneur mentorship, and business support systems are more likely to survive and thrive. The key is to act early, before the crisis deepens.

    Developing a Support Network

    Create a personal board of advisors: a mentor, a financial expert, a marketing guru, and a peer. Meet regularly to review progress. Also, join industry groups and online communities. This network provides diverse perspectives and resources.

    Measuring the Impact of Support

    Track metrics like cash flow, profit margins, employee satisfaction, and customer retention before and after engaging support. This quantifies the value and helps you decide when to adjust or end the engagement.

    Topic 9: Case Studies of Successful Turnarounds

    Real-world examples illustrate the power of external support. Consider a restaurant chain that was losing money due to high food costs. They hired a business advisory service that renegotiated supplier contracts and redesigned the menu, resulting in a 25% cost reduction. Another example: a tech startup with cash flow issues joined an accelerator, received mentorship, and pivoted to a subscription model, tripling revenue within a year.

    Lessons Learned

    • Act early: Don’t wait until you’re out of cash.
    • Be open to change: External support often requires uncomfortable shifts.
    • Commit to the process: Recovery takes time and effort.

    Topic 10: Overcoming the Stigma of Seeking Help

    Many entrepreneurs resist seeking help due to pride, fear of judgment, or loss of control. but, admitting you need support is a sign of strength. The most successful entrepreneurs have mentors and advisors. Reframe seeking help as a strategic investment, not a failure.

    Changing Your Mindset

    Understand that no one knows everything. External experts can fill gaps in your knowledge. Also, remember that your business’s survival is more important than your ego. Seek support early to avoid catastrophic failure.

    Topic 11: How to Approach Potential Advisors and Mentors

    When reaching out to potential supporters, be prepared. Clearly articulate your challenges, what you’ve tried, and what you need. Be respectful of their time. Offer something in return, like a testimonial or referral. Follow up with gratitude.

    Sample Email Template

    “Dear [Name], I’m the owner of [Business], a [describe business]. We’re facing [specific issue]. I’ve admired your work in [area]. Would you be open to a 30-minute call to discuss potential ways you could help? Thank you.”

    Topic 12: Integrating Support Systems into Daily Operations

    External support shouldn’t be a one-time fix. Integrate it into your operations by scheduling regular check-ins, implementing recommended tools, and fostering a culture of continuous improvement. for instance, use a dashboard to track KPIs shared with your mentor.

    Tools and Technologies

    Use project management software (e.g., Asana) to track action items from advisory sessions. Use financial software for real-time cash flow monitoring. Use communication tools (e.g., Slack) for ongoing dialogue with your support network.

    Topic 13: Evaluating the Effectiveness of External Support

    Periodically assess whether the support is yielding results. Set clear objectives at the outset. If after 3-6 months there’s no improvement, consider changing advisors or approaches. Be honest about what’s working and what’s not.

    Key Performance Indicators

    • Cash flow positive months
    • Revenue growth rate
    • Customer acquisition cost
    • Employee engagement scores

    Topic 14: Long-Term Strategies for Sustainable Success

    Once your business stabilizes, focus on building resilience. Continue using business support systems for ongoing education. Maintain relationships with mentors. Implement robust financial controls. Diversify revenue streams. This prevents future crises.

    Building a Culture of Support

    Encourage your team to seek external learning opportunities. Create an environment where asking for help is normalized. This strengthens the entire organization.

    Topic 15: Conclusion

    Knowing when to seek external support for your struggling business is a critical skill that can mean the difference between failure and recovery. By recognizing the signs of distress early, leveraging business support systems, engaging business advisory services, and embracing entrepreneur mentorship, you can access the expertise and resources needed to turn your business around. Remember, you don’t have to go it alone. The path to saving a struggling business is paved with collaboration, humility, and strategic action. Take the first step today—reach out for help and start your journey toward sustainable success.

    Frequently Asked Questions

    What are the first signs that my business is failing?

    Common signs include persistent negative cash flow, declining profit margins, increasing debt, loss of key customers, high employee turnover, and stagnant sales. If you notice these, it’s time to assess your business health and consider external support.

    How can business advisory services help my struggling business?

    Business advisory services provide expert analysis and recommendations in areas like finance, strategy, and operations. They can help with cash flow management, cost reduction, strategic pivots, and operational improvements, often leading to a turnaround.

    What is the difference between a mentor and a business advisor?

    A mentor is typically an experienced entrepreneur who provides long-term, holistic guidance and emotional support, often for free. A business advisor is a paid professional who offers specialized expertise for a specific project or period. Both are valuable, but they serve different needs.

    Where can I find cash flow management support?

    You can find cash flow management support through financial advisors, small business development centers, SCORE mentors, and online tools. Also, consider government programs like the SBA that offer loans and counseling.

    How do I choose the right external support for my business?

    First, identify your most pressing issues. Then, research potential advisors or mentors with experience in those areas. Check references, assess their communication style, and ensure they understand your industry. Start with a trial engagement to see if it’s a good fit.

    Can external support really save a struggling business?

    Yes, many businesses have been saved by timely external support. but, success depends on the severity of the issues, the quality of the support, and the willingness of the entrepreneur to implement changes. Early intervention increases the chances of recovery.

    What if I can’t afford external support?

    Many resources are available for free or low cost, such as SCORE mentors, small business development centers, and government programs. Also, some advisors offer deferred payment or equity arrangements. Don’t let cost deter you from seeking help.

    Topic 16: The Role of Technology in Business Turnaround

    In the modern business landscape, technology can be a powerful ally in turning around a struggling company. but, many entrepreneurs either underutilize or overcomplicate technology, leading to wasted resources. External support can help you identify and implement the right tech solutions to streamline operations, enhance customer experience, and improve financial management.

    Key Technology Areas for Recovery

    • Cloud-Based Accounting Software: Tools like QuickBooks Online or Xero provide real-time financial data, automated invoicing, and cash flow forecasting. This enables better cash flow management support and reduces manual errors.
    • Customer Relationship Management (CRM): Systems like Salesforce or HubSpot help track leads, manage sales pipelines, and improve customer retention. For a struggling business, focusing on existing customers is often more cost-effective than acquiring new ones.
    • Inventory Management Systems: Software like TradeGecko or Zoho Inventory optimizes stock levels, reduces carrying costs, and prevents stockouts. This frees up cash tied in inventory.
    • Project Management Tools: Asana, Trello, or Monday.com help teams collaborate efficiently, track tasks, and meet deadlines. Improved productivity can directly impact profitability.
    • E-commerce and Digital Marketing: If your business hasn’t embraced online sales, a website with e-commerce functionality can open new revenue streams. Digital marketing tools like Google Ads and social media analytics can target customers cost-effectively.

    Implementing Technology with External Guidance

    A business advisory service can conduct a technology audit to assess your current systems and identify gaps. They can recommend affordable solutions that align with your budget and goals. For instance, a struggling retail store might adopt a point-of-sale system that integrates with inventory and accounting, reducing manual work and errors. Advisors can also help with training to ensure your team adopts the new tools effectively.

    Case Study: Tech-Driven Turnaround

    A small manufacturing company with outdated systems was losing orders due to slow response times. They hired a technology consultant who implemented an ERP system that integrated sales, production, and inventory. Within six months, order processing time decreased by 40%, and customer satisfaction improved. The investment paid for itself within a year through increased sales and reduced waste.

    Topic 17: Marketing and Sales Strategies for Recovery

    When a business is struggling, marketing and sales are often the first areas to be cut, but they are also critical for generating revenue. External support can help you refine your value proposition, target the right customers, and optimize your sales funnel without breaking the bank.

    Low-Cost Marketing Tactics

    • Content Marketing: Create valuable blog posts, videos, or infographics that address customer pain points. This builds authority and attracts organic traffic.
    • Social Media Engagement: Focus on platforms where your customers are active. Engage authentically, share user-generated content, and run targeted ads with small budgets.
    • Email Marketing: Build an email list and send regular newsletters with promotions, tips, and updates. Email has a high ROI and can re-engage lapsed customers.
    • Referral Programs: Encourage existing customers to refer others by offering discounts or rewards. Word-of-mouth is powerful and inexpensive.
    • Partnerships: Collaborate with complementary businesses for cross-promotions. for instance, a bakery could partner with a coffee shop.

    Sales Process Optimization

    A business advisory service can analyze your sales process to identify bottlenecks. They might recommend implementing a CRM to track leads, training sales staff on consultative selling, or refining your pricing strategy. For instance, if you’re losing deals on price, an advisor might help you reposition your product to emphasize value rather than cost.

    Measuring Marketing ROI

    Track key metrics like customer acquisition cost (CAC), lifetime value (LTV), and conversion rates. External experts can help set up analytics and interpret data to ensure your marketing spend is effective. If CAC is too high, they can suggest more efficient channels.

    Topic 18: Human Resources and Team Management During Crisis

    A struggling business often faces low morale, high turnover, and skill gaps. External support can help you manage your team effectively, even with limited resources.

    Retaining Key Employees

    • Transparent Communication: Be honest about the challenges and involve employees in problem-solving. This builds trust and loyalty.
    • Non-Monetary Incentives: Offer flexible hours, remote work options, or additional vacation days. These can boost morale without cash outlay.
    • Recognition Programs: Celebrate small wins and acknowledge contributions publicly. This fosters a positive culture.

    Restructuring the Team

    Sometimes, you need to let go of underperformers or roles that are no longer essential. An HR consultant can help you do this legally and compassionately. They can also assist in redefining job roles to align with the turnaround strategy. for instance, combining marketing and sales responsibilities might be more efficient.

    Building a Resilient Culture

    Entrepreneur mentorship can be invaluable in developing leadership skills. A mentor can coach you on how to inspire your team during tough times. Additionally, consider bringing in a temporary executive (interim CEO or CFO) to provide experienced leadership without a long-term commitment.

    Topic 19: Managing Stakeholder Relationships

    When your business is struggling, stakeholders—including investors, lenders, suppliers, and customers—may become anxious. External support can help you manage these relationships to maintain trust and support.

    Communicating with Investors and Lenders

    Be proactive. Provide regular updates on your turnaround plan and progress. If you need additional funding or loan modifications, present a realistic proposal backed by data. A financial advisor can help you prepare these materials and negotiate on your behalf.

    Negotiating with Suppliers

    Suppliers may be willing to extend payment terms or offer discounts if you communicate openly. A business advisory service can help you identify which suppliers are critical and develop a negotiation strategy. for instance, you might offer a longer-term contract in exchange for better terms.

    Retaining Customer Trust

    Customers may notice if your service slips. Be transparent about any issues and communicate how you’re improving. Consider offering loyalty programs or guarantees to rebuild confidence. A marketing advisor can help craft messaging that reassures customers.

    Topic 20: Exit Strategies and Knowing When to Let Go

    Not every business can be saved, and sometimes the best decision is to exit gracefully. External support can help you evaluate your options and execute an exit strategy that maximizes value and minimizes damage.

    Assessing Viability

    An objective advisor can help you determine if your business is truly salvageable. They’ll analyze financials, market conditions, and your personal capacity. If the numbers don’t add up, they’ll advise on exit options.

    Exit Options

    • Sell the Business: Find a buyer who sees value in your customer base, intellectual property, or assets. A business broker can help.
    • Merge with a Competitor: Combining operations can reduce costs and create synergies.
    • Liquidate: Sell assets and pay off creditors. This is often the last resort.
    • Transfer Ownership: Pass the business to a family member or employee if they have the skills and desire.

    Emotional Support During Exit

    Letting go of a business is emotionally challenging. An entrepreneur mentorship can provide support and perspective. They can help you see that exiting isn’t a failure but a strategic decision. Many successful entrepreneurs have had previous ventures that didn’t work out.

    Topic 21: Building a Personal Support System for the Entrepreneur

    Entrepreneurs often neglect their own well-being during a crisis, but personal resilience is critical. External support should include resources for your mental and physical health.

    Stress Management Techniques

    • Mindfulness and Meditation: Apps like Headspace can reduce anxiety.
    • Exercise: Regular physical activity improves mood and energy.
    • Sleep Hygiene: Prioritize 7-8 hours of sleep for better decision-making.

    Professional Help

    Consider working with a business coach or therapist who specializes in entrepreneurial stress. Many business support systems offer counseling services. Also, join peer support groups where you can share experiences without judgment.

    Maintaining Perspective

    Remember that your business isn’t your identity. External mentors can remind you of your strengths and help you see the bigger picture. This perspective can be the difference between giving up and pushing through.

    Topic 22: The Importance of Continuous Learning and Adaptation

    Once you’ve stabilized your business, the journey isn’t over. Continuous learning and adaptation are essential for long-term success. External support can help you stay ahead of trends and avoid future crises.

    Staying Updated

    Subscribe to industry publications, attend webinars, and participate in workshops. Many business advisory services offer ongoing education. Also, consider joining a mastermind group for regular peer learning.

    Implementing Feedback Loops

    Create systems for gathering feedback from customers, employees, and advisors. Use this data to iterate on your products and processes. A culture of continuous improvement prevents stagnation.

    Scenario Planning

    Work with an advisor to conduct regular scenario planning—what if a new competitor enters? What if the economy slows? This prepares you to respond quickly and confidently.

    Topic 23: Legal and Ethical Considerations in Turnaround

    During a crisis, it’s tempting to cut corners, but legal and ethical missteps can be devastating. External support helps you navigate complex regulations and maintain integrity.

    Compliance Issues

    Ensure you’re meeting tax obligations, employment laws, and industry regulations. A legal advisor can review your practices and identify risks. for instance, if you’re considering layoffs, an employment lawyer can guide you through proper procedures.

    Ethical Decision-Making

    When struggling, you might face dilemmas like whether to delay payments to suppliers or misrepresent financials to investors. A mentor or advisor can provide an ethical compass. Remember, trust is hard to rebuild once lost.

    Protecting Intellectual Property

    If your business has valuable IP, ensure it’s properly protected. A patent attorney or IP consultant can help. This is especially important if you’re considering selling the business.

    Topic 24: Creating a Turnaround Budget and Financial Plan

    A detailed financial plan is the backbone of any recovery. External support can help you create realistic projections and allocate resources effectively.

    Components of a Turnaround Budget

    • Revenue Forecast: Based on historical data and realistic growth assumptions.
    • Expense Reduction Targets: Identify specific areas to cut, such as rent, marketing, or payroll.
    • Cash Flow Projection: Weekly or monthly cash flow statements to anticipate shortfalls.
    • Capital Requirements: Determine if you need additional funding and how much.

    Monitoring and Adjusting

    Review actuals against the budget weekly. If you’re off track, adjust quickly. A financial advisor can help you interpret variances and make informed decisions. for instance, if sales are lower than expected, you might accelerate cost-cutting measures.

    Topic 25: Final Thoughts and Action Plan

    Seeking external support isn’t a sign of weakness; it’s a strategic move that can save your business. The key is to act early, be open to change, and commit to the process. Here’s a summary action plan:

    1. Self-Assessment: Honestly evaluate your business health using the signs discussed.
    2. Identify Needs: Determine which areas need the most help (cash flow, strategy, operations).
    3. Research Resources: Explore business support systems, business advisory services, and entrepreneur mentorship options.
    4. Reach Out: Contact potential advisors or mentors with a clear request.
    5. Implement Changes: Act on recommendations and track progress.
    6. Review and Adapt: Regularly assess what’s working and adjust as needed.

    “The greatest glory in living lies not in never falling, but in rising every time we fall.” – Nelson Mandela. Your business can rise again with the right support.

    Remember, you aren’t alone. Thousands of entrepreneurs have faced similar challenges and emerged stronger. By leveraging external support, you gain the expertise, perspective, and encouragement needed to turn your struggling business around. Take the first step today.

  • Why Processing and Manufacturing Businesses Fail: The Critical Role of Cash Flow and Financial Planning

    Why Processing and Manufacturing Businesses Fail: The Critical Role of Cash Flow and Financial Planning

    Introduction

    Processing and manufacturing businesses are the backbone of the global economy, transforming raw materials into finished goods that drive commerce and daily life. but, despite their critical role, these industries face a disproportionately high failure rate. According to industry studies, nearly 60% of manufacturing startups fail within the first five years, and even established firms are vulnerable to sudden collapse. The root cause often lies not in product quality or market demand but in fundamental financial mismanagement, particularly the importance of cash flow. Unlike service-based businesses, manufacturing requires significant upfront investment in machinery, raw materials, and labor before revenue is realized. This creates unique cash flow in manufacturing challenges that, if not properly managed, can lead to rapid business financial failure. This comprehensive guide explores the multifaceted reasons behind these failures, with a special focus on processing business cash flow, and provides actionable strategies for managing cash flow and financial planning to ensure long-term sustainability.

    The Cash Flow Trap: Why Manufacturing Businesses Fail

    The most common and devastating reason for failure in processing and manufacturing is the cash flow trap. Unlike retail or service businesses that often receive payment at the point of sale, manufacturers operate on credit terms, paying suppliers before receiving payment from customers. This creates a constant business cash flow problems scenario where cash outflows exceed inflows for extended periods. The problem is exacerbated by the capital-intensive nature of the industry, where large sums are tied up in inventory, work-in-progress, and accounts receivable. Without rigorous financial planning, even profitable companies can run out of cash and be forced into bankruptcy.

    The Cash Conversion Cycle in Manufacturing

    The cash conversion cycle (CCC) measures the time between paying for raw materials and collecting cash from customers. In manufacturing, this cycle is often 60-90 days or more, compared to 30 days for many service businesses. A longer CCC means more cash is tied up, increasing the risk of business cash flow problems. for instance, a furniture manufacturer must buy lumber, pay workers to cut and assemble, store finished goods, and then wait 30-60 days for payment from retailers. During this period, the company must cover payroll, rent, and utilities without incoming cash. If the company experiences any delay—such as a supplier delivery issue or a customer paying late—the cash crunch can become severe.

    Fixed Costs and Operating Leverage

    Manufacturing businesses have high fixed costs, including rent for factory space, machinery leases, and salaried employees. These costs must be paid regardless of production volume. When demand drops, revenue declines but fixed costs remain, squeezing margins. This operating leverage amplifies the impact of sales fluctuations on cash flow. A 10% drop in sales can lead to a 50% drop in net income, and if cash reserves are insufficient, the business may fail. Proper financial planning involves building cash reserves to weather such downturns and using flexible cost structures where possible.

    Poor Financial Planning and Forecasting

    Many manufacturing failures stem from inadequate financial planning. Entrepreneurs often underestimate the capital required or overestimate future sales. Without accurate cash flow forecasts, they can’t anticipate funding gaps. Effective financial planning requires detailed projections that account for seasonality, payment terms, and potential disruptions. For instance, a food processing business must forecast not only sales but also raw material price volatility, which can significantly impact processing business cash flow. A failure to plan for such variables often leads to last-minute borrowing at high interest rates, further straining cash flow.

    Lack of Cash Flow Budgeting

    A cash flow budget is a critical tool for managing cash flow. It projects cash inflows and outflows on a weekly or monthly basis, helping managers identify potential shortfalls. Yet many small manufacturers operate without one, relying on intuition or bank balances. This reactive approach means they only realize there is a problem when checks bounce or payroll is missed. A proactive cash flow budget allows for early intervention, such as negotiating extended payment terms with suppliers or arranging a line of credit before the crisis hits.

    Overreliance on Debt Financing

    Debt is a double-edged sword for manufacturers. While it provides necessary capital for growth, excessive debt creates fixed interest payments that drain cash. Many failed businesses took on too much debt to purchase machinery or expand capacity, only to find that the expected sales growth did not materialize. The debt service then becomes a major business cash flow problems contributor. A healthier approach is to balance debt with equity financing and to ensure that debt payments are covered by projected cash flows, not just optimistic sales forecasts.

    Inventory Management Failures

    Inventory is often the largest asset on a manufacturer’s balance sheet, but it is also the most common source of cash flow problems. Too much inventory ties up cash that could be used for other purposes, while too little inventory leads to stockouts and lost sales. Effective managing cash flow requires optimizing inventory levels through techniques like Just-In-Time (JIT) or Economic Order Quantity (EOQ). but, JIT requires reliable suppliers and stable demand, which may not exist in all industries. A balanced approach, such as using a safety stock based on demand variability, is often more practical for small manufacturers.

    Obsolete and Slow-Moving Inventory

    In industries like electronics or fashion, inventory can become obsolete quickly. Holding obsolete inventory not only ties up cash but also incurs storage costs and risks write-offs. A manufacturer of smartphone components, for instance, must carefully manage inventory to avoid being left with parts that no longer fit new models. Regular inventory audits and markdowns can help convert slow-moving items to cash, albeit at a loss. The key is to recognize the importance of cash flow over gross margin; selling at a discount to generate cash is often better than holding inventory indefinitely.

    Raw Material Price Volatility

    Many processing businesses are exposed to volatile raw material prices. for instance, a metal fabricator may see steel prices fluctuate by 20% in a year. If they purchase inventory when prices are high and then sell finished goods when prices drop, margins are squeezed. Hedging strategies, such as futures contracts, can mitigate this risk, but they require expertise and capital. A simpler approach is to include price escalation clauses in customer contracts, passing some of the risk to buyers. This protects processing business cash flow from unexpected cost increases.

    Accounts Receivable Mismanagement

    Offering credit to customers is standard in manufacturing, but poor management of accounts receivable can cripple cash flow. Many manufacturers fail because they are too lenient with payment terms or don’t follow up on overdue invoices. The importance of cash flow can’t be overstated: if customers don’t pay on time, the business can’t pay its own bills. Effective managing cash flow includes implementing strict credit policies, conducting background checks on new customers, and using collection agencies for delinquent accounts. Offering discounts for early payment, such as 2/10 net 30, can also accelerate cash inflows.

    Customer Concentration Risk

    Relying on a few large customers is risky because if one customer delays payment or goes bankrupt, the manufacturer faces a severe cash crunch. Diversifying the customer base reduces this risk. for instance, a packaging manufacturer that serves only two major food companies is vulnerable to the financial health of those companies. If one experiences a downturn, the manufacturer’s business cash flow problems become acute. Spreading sales across multiple industries and geographies provides a buffer.

    Lack of Invoice Factoring or Financing

    Invoice factoring, where a company sells its accounts receivable to a third party at a discount, can provide immediate cash. but, many manufacturers avoid factoring due to the cost or stigma. Yet, when used strategically, factoring can bridge cash flow gaps during growth periods. For instance, a custom machine shop that lands a large contract may need cash to buy materials and pay overtime. Factoring the resulting invoices can provide the necessary liquidity without taking on additional debt. The key is to factor only when the cost is justified by the opportunity.

    Capital Expenditure Mismanagement

    Processing and manufacturing businesses require significant capital expenditures (CapEx) for machinery, equipment, and facilities. While investing in new technology can improve efficiency and competitiveness, poor CapEx decisions can destroy cash flow. Common mistakes include purchasing equipment that is underutilized, buying on credit without considering total cost of ownership, or investing in capacity that exceeds current demand. A disciplined financial planning process should evaluate each CapEx project based on its payback period and net present value, ensuring that the investment generates sufficient cash flow to service any debt and provide a return.

    Leasing vs. Buying Equipment

    Leasing equipment can preserve cash flow by avoiding large upfront payments, but it often has higher total costs over time. Conversely, buying equipment requires significant cash or debt but can be cheaper in the long run. The decision depends on the company’s cash position and growth stage. A startup might benefit from leasing to conserve cash, while an established firm with strong cash flow might prefer to buy. The importance of cash flow should guide this decision: if buying would deplete cash reserves and increase risk, leasing is preferable.

    Maintenance and Downtime Costs

    Unplanned equipment downtime can halt production, leading to lost revenue and idle labor costs. Many manufacturers fail to budget for maintenance, leading to breakdowns that drain cash. A preventive maintenance program, while requiring upfront expense, reduces the risk of catastrophic failures. Additionally, having a reserve fund for emergency repairs is part of sound financial planning. The cost of downtime often far exceeds the cost of maintenance, so prioritizing equipment health is a cash flow imperative.

    Pricing and Margin Erosion

    Intense competition often forces manufacturers to lower prices to win business, but if prices fall below total costs, the business loses money on every sale. Many companies fail because they don’t fully understand their costs, including overhead and indirect expenses. for instance, a plastic injection molder may quote a price based on material and labor costs but forget to include machine depreciation, utilities, and quality control. Over time, these hidden costs erode margins and create business cash flow problems. Accurate cost accounting and regular price reviews are essential for maintaining profitability.

    Commodity Pricing and Differentiation

    In commoditized industries, such as basic metal stamping or simple assembly, customers often choose based on price alone. This leads to a race to the bottom where margins disappear. To avoid this, manufacturers must differentiate through quality, lead time, or value-added services. for instance, a custom packaging manufacturer can offer design services and just-in-time delivery, allowing them to charge a premium. Differentiation protects processing business cash flow by reducing price sensitivity and increasing customer loyalty.

    Long-Term Contracts Without Price Escalation

    Locking into long-term fixed-price contracts can be disastrous if input costs rise. A food processor that agrees to supply a retailer at a fixed price for a year may find that raw material costs increase by 20% midway through the contract, wiping out profits. Including price escalation clauses tied to commodity indices or inflation protects margins. This is a critical aspect of financial planning for any processing business exposed to volatile inputs.

    Operational Inefficiencies and Waste

    Inefficient operations increase costs and reduce cash flow. Common issues include high scrap rates, rework, overtime, and excessive energy consumption. Lean manufacturing principles, such as Six Sigma and Kaizen, can identify and eliminate waste, improving cash flow. For instance, a metal fabrication shop that reduces scrap from 10% to 5% immediately saves material costs and reduces the cash tied up in wasted inventory. Continuous improvement should be a core part of managing cash flow.

    Labor Productivity and Training

    Labor is a major cost in manufacturing, and low productivity directly impacts cash flow. Inadequate training, poor scheduling, and high turnover lead to inefficiencies. Investing in employee training and cross-training can improve flexibility and output. for instance, a small electronics assembly plant that trains workers to perform multiple tasks can adjust production lines quickly to meet changing demand, reducing idle time and improving cash flow. While training costs money upfront, the long-term benefits in productivity and reduced errors are substantial.

    Energy and Utility Costs

    Energy is a significant expense for many manufacturers, especially those with energy-intensive processes like metal smelting or chemical processing. Fluctuating energy prices can create business cash flow problems if not managed. Implementing energy-efficient technologies, such as LED lighting, efficient motors, and heat recovery systems, can reduce costs. Additionally, negotiating fixed-rate energy contracts or participating in demand response programs can provide cost certainty, aiding financial planning.

    Supply Chain Disruptions

    Manufacturers rely on a complex web of suppliers for raw materials, components, and services. Disruptions—whether from natural disasters, geopolitical events, or supplier bankruptcies—can halt production and create cash flow crises. The COVID-19 pandemic highlighted this vulnerability, as many manufacturers faced shortages of critical inputs. Diversifying suppliers, maintaining safety stock, and developing relationships with backup suppliers are essential strategies. but, these strategies also require cash, so a balance must be struck. The importance of cash flow means that supply chain resilience must be built without overextending financially.

    Supplier Payment Terms

    Just as manufacturers extend credit to customers, they receive credit from suppliers. Negotiating favorable payment terms, such as net 60 or net 90, can improve cash flow. but, if suppliers are small or have their own cash constraints, they may demand shorter terms. Building strong relationships and paying on time can help secure better terms. Conversely, taking too long to pay suppliers can damage relationships and lead to supply disruptions, which harm processing business cash flow in the long run.

    Global Supply Chain Risks

    Many manufacturers source from low-cost countries to reduce material costs, but this exposes them to currency fluctuations, shipping delays, and customs issues. A sudden tariff increase or port strike can increase costs and delay receipts. for instance, a furniture manufacturer importing lumber from Brazil may face a 30% tariff, making its products uncompetitive. Hedging currency risk and having domestic backup sources can mitigate these issues. This adds complexity to financial planning but is necessary for survival.

    Regulatory and Compliance Costs

    Manufacturers must comply with a myriad of regulations, including environmental, safety, and labor laws. Non-compliance can result in fines, lawsuits, and shutdowns, all of which drain cash. The costs of compliance—such as installing pollution control equipment or conducting safety training—can be significant. A proactive approach is to budget for compliance as part of financial planning and to stay informed about regulatory changes. For instance, a chemical processor that anticipates stricter emissions standards can invest in cleaner technology gradually, rather than facing a sudden capital outlay.

    Environmental Liabilities

    Improper disposal of hazardous waste can lead to costly cleanup and legal liabilities. A small metal plating company that illegally dumps chemicals may face fines that exceed its annual profit. Environmental insurance can cover some risks, but prevention is cheaper. Implementing proper waste management and recycling programs not only reduces legal risk but can also generate revenue from scrap materials, improving processing business cash flow.

    Health and Safety Violations

    Workplace accidents lead to medical costs, workers’ compensation claims, and potential lawsuits. They also cause downtime and reduced morale. Investing in safety training and equipment reduces these risks. for instance, a food processing plant that installs machine guards and provides safety gear can prevent accidents that would otherwise cost thousands in claims and lost productivity. The return on investment in safety is often high, as it protects both employees and cash flow.

    Technology and Automation Failures

    Adopting new technology can improve efficiency, but it also carries risks. Implementation failures, such as software bugs or incompatible systems, can disrupt operations and waste cash. Many manufacturers fail because they invest in automation without properly training employees or integrating systems. A phased approach, starting with pilot projects, reduces risk. The importance of cash flow means that technology investments should be made with a clear ROI and a realistic timeline for payback.

    Outdated Equipment

    Conversely, failing to upgrade obsolete equipment can lead to high maintenance costs, low productivity, and quality issues. A machine that breaks down frequently not only costs money to repair but also delays production, leading to late deliveries and lost customers. Balancing the need for modernization with cash constraints is a constant challenge. A capital replacement plan, funded through depreciation and retained earnings, can ensure that equipment is replaced before it becomes a liability.

    Cybersecurity Risks

    As manufacturers become more connected through IoT and ERP systems, they become vulnerable to cyberattacks. A ransomware attack can shut down production for days, causing massive revenue loss and cash flow strain. Investing in cybersecurity measures, such as firewalls, employee training, and backup systems, is essential. While these costs may seem high, the potential cost of an attack is far greater. Including cybersecurity in financial planning is no longer optional.

    Human Resource Challenges

    Skilled labor shortages are a chronic issue in manufacturing. Difficulty finding and retaining qualified workers leads to higher recruitment costs, overtime, and turnover. These costs directly impact cash flow. Offering competitive wages, benefits, and training programs can help retain talent, but they also increase expenses. A comprehensive HR strategy that includes succession planning and cross-training can mitigate the impact of turnover. for instance, a precision machining shop that invests in apprenticeship programs can develop a pipeline of skilled workers, reducing reliance on expensive temporary labor.

    Payroll Management

    Payroll is often the largest expense and must be paid on time regardless of revenue. Mismanaging payroll—either by overstaffing or failing to budget for payroll taxes—can lead to penalties and cash shortages. Using a payroll service or software can ensure accuracy and compliance. Additionally, aligning pay periods with cash flow cycles, such as paying bi-weekly rather than weekly, can help smooth out cash needs. The importance of cash flow means that payroll should be a top priority in financial planning.

    Union Relations and Strikes

    Unionized manufacturers face the risk of strikes or work stoppages that can halt production and drain cash. Poor labor relations can lead to costly disputes. Maintaining open communication and fair treatment can reduce the likelihood of strikes. If a strike does occur, having a contingency plan, such as temporary workers or inventory buffers, can minimize cash flow damage.

    Market and Demand Fluctuations

    Manufacturers are vulnerable to economic cycles and changes in customer demand. A recession can cause a sharp drop in orders, while a boom can lead to overexpansion. Both scenarios create business cash flow problems. Diversifying product lines and customer segments can reduce dependence on any single market. for instance, a manufacturer of automotive parts might also produce components for medical devices, providing a hedge against downturns in the auto industry. Agile manufacturing practices, such as flexible production lines, allow companies to quickly adjust output to match demand, preserving cash flow.

    Seasonal Demand

    Many processing businesses, such as food canneries or holiday decoration manufacturers, face seasonal demand. They must build inventory before the peak season, requiring significant cash outlays months before revenue is realized. Without proper financial planning, this seasonal cash gap can be fatal. Options include securing a seasonal line of credit, negotiating extended payment terms with suppliers, or offering pre-season discounts to customers to encourage early orders. The key is to anticipate the cash needs and arrange financing in advance.

    Changing Consumer Preferences

    Consumer tastes can shift rapidly, rendering a manufacturer’s products obsolete. for instance, a textile mill that produces synthetic fabrics may suffer if demand shifts to natural fibers. Staying attuned to market trends and investing in R&D can help companies pivot. but, R&D itself requires cash, so a balance must be struck. A company that fails to innovate may see its cash flow dry up as sales decline. Continuous market research and flexible product development processes are essential for long-term survival.

    Conclusion

    The failure of processing and manufacturing businesses is rarely due to a single cause but rather a combination of interrelated factors, all of which revolve around the importance of cash flow. From the cash conversion cycle and inventory management to pricing strategies and supply chain disruptions, every aspect of the business impacts cash flow in manufacturing. Understanding and proactively managing processing business cash flow is the single most critical skill for survival. Entrepreneurs and managers must prioritize financial planning, create detailed cash flow budgets, and maintain discipline in capital expenditures and receivables management. By recognizing the common pitfalls outlined in this guide and implementing robust strategies for managing cash flow, manufacturers can avoid the tragic fate of business financial failure. The road is challenging, but with vigilance and sound financial practices, processing and manufacturing businesses can thrive even in turbulent times.

    Frequently Asked Questions

    Why is cash flow more important than profit in manufacturing?

    Profit is an accounting concept that includes non-cash items like depreciation, while cash flow is the actual money moving in and out of the business. A manufacturer can be profitable on paper but still fail if it can’t pay its bills on time. for instance, a company that makes a large sale on credit will record profit immediately but may not receive cash for 60 days. During that period, it must still pay suppliers and employees. If cash reserves are insufficient, the business may default on obligations and be forced into bankruptcy, despite being profitable. so, managing cash flow is essential for day-to-day survival.

    What are the first signs of cash flow problems in a manufacturing business?

    Early warning signs include: (1) Difficulty paying suppliers on time, leading to collection calls or credit holds; (2) Delaying payments to vendors or stretching accounts payable beyond terms; (3) Using credit cards or overdrafts to cover routine expenses; (4) Frequent requests for customer prepayments; (5) Inventory levels growing faster than sales; (6) Increasing accounts receivable days; (7) Missing payroll or borrowing to meet payroll. Recognizing these signs early allows management to take corrective action, such as negotiating better payment terms or securing a line of credit, before the situation becomes critical.

    How can a manufacturer improve cash flow quickly?

    Immediate steps include: (1) Accelerate accounts receivable by offering discounts for early payment, sending invoices promptly, and following up on overdue accounts; (2) Reduce inventory by selling slow-moving items at a discount, implementing JIT, or negotiating consignment agreements with suppliers; (3) Extend accounts payable by negotiating longer payment terms with key suppliers; (4) Cut discretionary expenses such as travel, marketing, or non-essential purchases; (5) Sell unused equipment or lease out excess capacity; (6) Consider short-term financing like invoice factoring or a line of credit. These actions can provide a quick cash injection while longer-term strategies are implemented.

    What is the role of financial planning in preventing manufacturing business failure?

    Financial planning provides a roadmap for managing cash flow, capital investments, and growth. It involves forecasting sales, expenses, and cash needs over different time horizons (weekly, monthly, annually). A robust financial plan helps identify potential cash shortfalls before they occur, allowing managers to arrange financing or adjust operations proactively. It also guides decisions about pricing, cost control, and investment. Without a plan, manufacturers operate reactively, often making decisions that worsen cash flow. Planning also helps in setting realistic growth targets and ensuring that expansion is funded appropriately, reducing the risk of overleveraging.

    How does inventory management affect processing business cash flow?

    Inventory ties up cash directly. Every dollar in inventory is a dollar that can’t be used for other purposes. Excess inventory increases storage costs, risk of obsolescence, and insurance premiums. Conversely, insufficient inventory leads to stockouts, lost sales, and rush orders that cost more. Effective inventory management balances these risks by optimizing order quantities, safety stock levels, and lead times. Techniques like ABC analysis (prioritizing high-value items) and cycle counting help maintain accurate records. For processing businesses, where raw materials are often perishable or volatile in price, inventory management is even more critical to processing business cash flow.

    What are common mistakes in financial planning for manufacturers?

    Common mistakes include: (1) Overly optimistic sales forecasts that ignore market cycles; (2) Underestimating the cash required for growth, such as inventory buildup and receivables; (3) Failing to plan for seasonal fluctuations; (4) Ignoring the impact of fixed costs on cash flow; (5) Not having a contingency plan for disruptions (e.g., supplier failure, equipment breakdown); (6) Using debt to fund operating expenses rather than growth; (7) Neglecting to update forecasts regularly. Avoiding these pitfalls requires realistic assumptions, conservative estimates, and continuous monitoring of actual performance against the plan.

    Can a manufacturer survive with negative cash flow?

    Yes, but only temporarily and with adequate financing. Negative cash flow means the business is spending more cash than it generates. If the negative cash flow is due to growth (e.g., investing in new equipment or building inventory for a large order), it can be financed through debt or equity. but, if negative cash flow persists due to operational losses, the business will eventually run out of cash and fail. The key is to have a clear plan to return to positive cash flow within a reasonable timeframe, and to secure funding that bridges the gap. Without a viable plan, negative cash flow is a death sentence.

    How does technology help in managing cash flow in manufacturing?

    Technology, such as ERP systems, provides real-time visibility into financial and operational data. It automates invoicing, tracks accounts receivable and payable, and generates cash flow forecasts. Advanced analytics can identify trends and warn of potential shortfalls. for instance, an ERP system can flag when a customer’s payment is overdue or when inventory levels exceed targets. Additionally, cloud-based solutions allow managers to monitor cash flow from anywhere, enabling faster decision-making. Automation reduces errors and frees up staff to focus on strategic tasks. Investing in the right technology can significantly improve managing cash flow.

    What is the biggest risk factor for small manufacturing businesses?

    The biggest risk factor is insufficient capitalization. Many small manufacturers start with minimal capital and rely on customer payments to fund operations. A single large customer paying late or a unexpected expense can trigger a crisis. Additionally, lack of access to affordable credit exacerbates cash flow problems. Without a cash reserve or a line of credit, small manufacturers have no buffer. The importance of cash flow can’t be overstated; a small business must prioritize building a cash reserve as part of its financial planning to weather inevitable shocks.

  • Choosing the Right Business Plan Structure: A Comprehensive Guide to Writing a Winning Plan

    Choosing the Right Business Plan Structure: A Comprehensive Guide to Writing a Winning Plan

    Introduction

    Writing a business plan is a critical step for any entrepreneur, but one of the most common challenges is choosing the right business plan structure. The structure you select can significantly impact how your plan is received by investors, lenders, and stakeholders. This comprehensive guide explores the various approaches to writing a business plan, examines business plan templates, and provides actionable insights for small vs large business plans, product business plans, and service business plans. By the end, you will be equipped with the knowledge to craft a plan that aligns with your business goals and audience expectations.

    The structure of a business plan isn’t one-size-fits-all. A startup seeking venture capital requires a different format than a small business applying for a bank loan. Similarly, a product-based business must highlight manufacturing and inventory, while a service-based business focuses on expertise and client acquisition. Understanding these nuances is essential for creating a compelling document that communicates your vision effectively.

    In this article, we will delve into the most effective business plan structures, provide real-world business plan examples, and discuss how to adapt your plan for different contexts. Whether you are a first-time entrepreneur or a seasoned business owner, this guide will help you make informed decisions about your business plan format.

    Understanding the Structure of a Business Plan

    A business plan is a formal document that outlines your business goals, strategies, target market, and financial projections. The structure of a business plan typically includes several key sections: executive summary, company description, market analysis, organization and management, product or service line, marketing and sales, funding request, financial projections, and appendix. but, the order and depth of these sections can vary based on your audience and purpose.

    for instance, a lean startup plan may condense these sections into a single page, while a traditional plan for a bank loan may require extensive detail. The structure should be logical and easy to navigate, with clear headings and subheadings. Investors often skim the executive summary first, so placing it at the beginning is non-negotiable.

    When choosing the right structure, consider the following factors: the stage of your business (startup vs. established), the type of business (product vs. service), the size of the business (small vs. large), and the intended audience (investors, lenders, or internal use). Each factor influences the emphasis on certain sections.

    Approaches to Writing a Business Plan

    There are several approaches to writing a business plan, each suited to different needs. The traditional business plan is comprehensive and detailed, often running 20-30 pages. It is ideal for seeking significant funding or for complex businesses. The lean startup plan is a shorter, more agile version that focuses on key assumptions and metrics. It is popular among startups that need to iterate quickly.

    Another approach is the one-page business plan, which condenses the entire plan into a single page. This is useful for internal communication or as a quick reference. but, it lacks the depth required for formal funding applications. The business model canvas is a visual tool that maps out nine key components of a business, such as value proposition, customer segments, and revenue streams. It is often used as a precursor to a full business plan.

    Choosing the right approach depends on your goals. If you need to convince investors of your market opportunity, a traditional plan with detailed market analysis is best. If you are testing a new idea, a lean plan allows for flexibility. Many successful entrepreneurs use a combination: a one-page plan for internal alignment and a traditional plan for external stakeholders.

    Business Plan Templates: A Starting Point

    Business plan templates provide a structured framework that saves time and ensures you don’t miss critical sections. Templates are available from various sources, including the Small Business Administration (SBA), SCORE, and online platforms like LivePlan. They come in different formats, such as Word documents, PDFs, and interactive software.

    Using a template can help you understand the structure of a business plan and provide prompts for each section. but, templates should be customized to reflect your unique business. Avoid simply filling in the blanks; instead, use the template as a guide to tell your story. for instance, a template may have a generic market analysis section, but you should tailor it with specific data about your industry and target market.

    There are specialized templates for different business types. A product business plan template will emphasize manufacturing and supply chain, while a service business plan template focuses on expertise and client management. Similarly, templates for small businesses may be simpler than those for large corporations. Choose a template that matches your business model and scale.

    Small vs Large Business Plan: Key Differences

    The size of your business influences the complexity of your business plan. A small business plan is often shorter and more focused on immediate goals, such as securing a loan or managing cash flow. It may include a simple financial forecast and a basic marketing strategy. Small business owners typically have limited time, so the plan should be concise yet complete.

    In contrast, a large business plan is more detailed and strategic. It covers multiple departments, long-term goals, and complex financial projections. Large companies may use the plan to align internal teams, attract investors for expansion, or enter new markets. The structure of a business plan for a large enterprise often includes sections on corporate governance, risk management, and global market analysis.

    For small businesses, the key is to demonstrate viability and repayment ability. For large businesses, the focus is on scalability, competitive advantage, and return on investment. When choosing the right structure, consider the resources available for writing and reviewing the plan. A small business may benefit from a lean plan, while a large business requires a comprehensive document.

    Product Business Plan: Key Elements

    A product business plan centers on a tangible item that you manufacture or sell. The structure should highlight product development, manufacturing processes, supply chain management, and inventory control. Key sections include product description, production plan, and quality assurance. The market analysis should focus on product demand, competition, and distribution channels.

    for instance, a business plan for a new electronic gadget would include details on design, prototyping, sourcing components, assembly, and shipping. Financial projections must account for production costs, economies of scale, and pricing strategies. Investors in product businesses often look for a clear path to manufacturing and a defensible intellectual property strategy.

    Product business plans also need to address regulatory requirements, such as safety standards or patents. The plan should demonstrate that you can produce the product efficiently and at a competitive cost. Using a product-specific template can help ensure you cover all critical aspects.

    Service Business Plan: Key Elements

    A service business plan focuses on intangible offerings, such as consulting, healthcare, or software as a service (SaaS). The structure emphasizes expertise, client acquisition, and delivery processes. Key sections include service description, client engagement model, and quality control. The market analysis should identify target clients, their pain points, and how your service solves them.

    For instance, a business plan for a marketing agency would detail the services offered (e.g., SEO, social media management), the team’s expertise, and the process for onboarding clients. Financial projections should consider billable hours, retainer fees, and client lifetime value. Investors in service businesses often look for a strong team, repeatable sales process, and scalable delivery.

    Service business plans should also highlight customer testimonials or case studies to build credibility. Since services are intangible, the plan must convincingly demonstrate value and differentiation. A service-specific template can guide you in structuring these elements effectively.

    Business Plan Examples: Learning from Real Plans

    Reviewing business plan examples can provide inspiration and practical guidance. Many successful companies have published their business plans, such as the original plan for Airbnb or the one for Uber. These examples show how to structure a compelling narrative, present financial data, and address investor concerns.

    For small businesses, the SBA offers sample plans for various industries, including retail, restaurant, and consulting. These examples illustrate the typical structure of a business plan and the level of detail expected. By studying them, you can learn how to write a clear executive summary, conduct market research, and create realistic financial projections.

    When using examples, adapt them to your context. don’t copy verbatim; instead, use them as a reference for tone, format, and content. Pay attention to how they handle sensitive sections like funding request and risk analysis. Good examples show how to be transparent without oversharing.

    How to Choose the Right Structure for Your Business

    Choosing the right business plan structure involves evaluating your audience, purpose, and business type. Start by asking: Who will read this plan? Investors expect a detailed plan with a strong executive summary and financials. Lenders want to see cash flow projections and collateral. For internal use, a lean plan may suffice.

    Next, consider your business stage. A startup needs to explain the opportunity and team, while an existing business should highlight traction and growth. For product businesses, emphasize production and supply chain; for service businesses, focus on expertise and client acquisition. The size of your business also matters: small businesses should keep it simple, while large businesses need comprehensive coverage.

    Finally, test your structure with a mock audience. Get feedback from mentors or advisors. They can tell you if the plan is too long, missing key sections, or confusing. Iterate based on feedback until the structure feels right. Remember, the goal is to communicate your vision clearly and persuasively.

    Common Mistakes in Business Plan Structure

    One common mistake is using a generic structure without customizing it for the business. for instance, a service business using a product-focused template may miss critical elements like client retention strategies. Another mistake is burying the executive summary with too much detail; it should be concise and compelling.

    Another error is inconsistent formatting or lack of visual elements. Tables, charts, and bullet points improve readability. Avoid long paragraphs; break them into shorter ones. Also, ensure that financial projections are realistic and supported by assumptions. Overly optimistic numbers can harm credibility.

    Finally, neglecting the appendix is a missed opportunity. Include supporting documents like market research, patents, or resumes of key team members. This adds depth without cluttering the main sections. By avoiding these mistakes, you can create a professional business plan that stands out.

    Leveraging Technology for Business Plan Structure

    Technology can simplify the process of choosing and implementing a business plan structure. Software like LivePlan, Enloop, and BizPlanBuilder offer templates, financial forecasting tools, and collaboration features. These platforms guide you through each section and ensure consistency.

    for instance, LivePlan provides a step-by-step wizard that asks about your business type and audience, then suggests a structure. It also generates charts and graphs automatically. Enloop uses artificial intelligence to analyze your inputs and provide feedback on strengths and weaknesses.

    Using technology can save time and improve quality, but it shouldn’t replace critical thinking. Customize the output to reflect your unique story. Also, ensure that the final document is in a format that your audience prefers, such as PDF for investors or a printed copy for lenders.

    Financial Projections in Different Structures

    Financial projections are a critical part of any business plan, but their presentation varies by structure. In a traditional plan, you include detailed income statements, balance sheets, and cash flow statements for three to five years. For a lean plan, you might only have a one-year forecast and key metrics like customer acquisition cost.

    For product businesses, financial projections should include cost of goods sold, inventory turnover, and breakeven analysis. For service businesses, focus on billable hours, utilization rates, and client acquisition costs. Large businesses may need to show consolidated financials for multiple divisions.

    When presenting financials, use tables and charts to make data digestible. Include assumptions for each line item, such as growth rates and pricing. Investors will scrutinize these numbers, so ensure they are realistic and tied to market research. A well-structured financial section builds credibility.

    Tailoring the Executive Summary

    The executive summary is the most important section of a business plan, as it often determines whether the reader continues. Its structure should be tailored to your audience and business type. For investors, highlight the problem, solution, market size, and financial highlights. For lenders, emphasize repayment ability and collateral.

    For a product business, the executive summary should mention the product’s unique features and competitive advantage. For a service business, focus on the team’s expertise and client results. Keep it to one or two pages, using bullet points for key metrics. Write it last, after you have completed the other sections, so you can summarize effectively.

    A strong executive summary captures the essence of your business and entices the reader to learn more. It should be clear, concise, and compelling. Avoid jargon and focus on the value proposition. Remember, you have only a few seconds to grab attention.

    Market Analysis: Depth vs. Brevity

    The market analysis section should demonstrate a deep understanding of your industry, target market, and competition. The depth required depends on your business plan structure. For a traditional plan, include detailed market segmentation, trends, and competitive analysis using tools like SWOT or Porter’s Five Forces.

    For a lean plan, a shorter market analysis with key statistics and customer personas may suffice. Product businesses should analyze supply chain and distribution channels, while service businesses should focus on client demographics and buying behavior. Large businesses may need global market analysis.

    Use tables to compare competitors or show market share. Cite sources for data to add credibility. The goal is to convince readers that there is a viable market for your offering and that you understand how to reach it. Avoid vague statements; be specific with numbers and examples.

    Organization and Management Structure

    This section outlines your business’s legal structure, management team, and organizational hierarchy. The structure you choose (sole proprietorship, LLC, corporation) impacts liability and taxes. For a small business, a simple chart may suffice; for a large business, include details on board of directors and advisory board.

    Product businesses may highlight the team’s experience in manufacturing or engineering. Service businesses should emphasize credentials and client relationships. Include resumes of key team members in the appendix. Investors invest in people, so this section is critical.

    Also, describe your hiring plan and company culture. This shows that you have thought about growth and team dynamics. A well-structured management section builds confidence in your ability to execute the plan.

    Marketing and Sales Strategy

    The marketing and sales strategy section should detail how you will attract and retain customers. The structure varies by business type. For product businesses, focus on distribution channels, advertising, and promotions. For service businesses, emphasize networking, referrals, and content marketing.

    Include specific tactics, such as SEO, social media, or trade shows. For each tactic, provide expected costs and conversion rates. Use a table to compare marketing channels or show a sales funnel. Financial projections should align with marketing spend.

    Large businesses may have a more complex strategy involving multiple segments and channels. Small businesses should focus on cost-effective tactics. The key is to show a clear path to revenue. Investors want to see that you have a realistic and scalable marketing plan.

    Funding Request and Use of Funds

    If you are seeking funding, this section specifies the amount needed and how it will be used. The structure should be clear and justified. Break down the use of funds into categories like product development, marketing, and working capital. Include a timeline for when the funds will be used.

    For product businesses, a significant portion may go to manufacturing and inventory. For service businesses, funds may be used for hiring and sales. Large businesses may need funds for expansion or acquisitions. Provide a repayment plan or exit strategy for investors.

    Use a table to show the allocation of funds. Be realistic about how much you need and why. Overfunding can be as problematic as underfunding. This section should tie directly to your financial projections and business goals.

    Conclusion

    Choosing the right business plan structure is a strategic decision that can influence the success of your funding efforts and business growth. By understanding the different approaches to writing a business plan, leveraging business plan templates, and tailoring your plan for small vs large, product vs service businesses, you can create a document that resonates with your audience. Remember that the structure of a business plan should be flexible and adapted to your unique context.

    Use business plan examples as inspiration, but ensure your plan reflects your vision and data. Avoid common mistakes like generic content or overly optimistic projections. Leverage technology to streamline the process, but maintain a personal touch. With the right structure, your business plan will be a powerful tool to communicate your value and secure the resources you need.

    Finally, revisit your plan regularly. As your business evolves, the structure may need to change. A good business plan is a living document that guides your decisions and adapts to new opportunities. By mastering the art of choosing the right structure, you set your business up for long-term success.

    Frequently Asked Questions (FAQs)

    What is the best business plan structure for a startup?

    The best structure for a startup often combines elements of a lean plan and a traditional plan. Start with a one-page canvas to clarify your business model, then expand into a full plan with detailed market analysis and financial projections. Focus on the problem, solution, and team. Investors appreciate a clear story and realistic numbers.

    How long should a business plan be?

    The length depends on the audience and purpose. A traditional business plan for investors is typically 20-30 pages. A lean startup plan can be 5-10 pages. A one-page plan is exactly one page. For bank loans, aim for 15-20 pages with detailed financials. Always prioritize quality over length.

    Can I use a template for my business plan?

    Yes, templates are a great starting point, but they must be customized. Use a template that matches your business type (product or service) and size. Fill in the sections with your unique data and story. Avoid generic language. The best templates come from reputable sources like the SBA or SCORE.

    What is the difference between a product business plan and a service business plan?

    A product business plan emphasizes manufacturing, supply chain, and inventory management. It includes details on product development, production costs, and distribution. A service business plan focuses on expertise, client acquisition, and delivery processes. It highlights team qualifications, client case studies, and billing models.

    How do I choose between a traditional and a lean business plan?

    Choose a traditional plan if you need external funding from investors or banks, or if your business is complex. Choose a lean plan if you are testing a new idea, have limited time, or need a flexible document for internal use. Many entrepreneurs start with a lean plan and later expand it.

    Appendix: Supporting Documents

    The appendix is often the most overlooked section of a business plan, yet it can significantly enhance your credibility. This section should include supporting documents that validate the claims made in the main body. For product businesses, include patents, trademarks, or product schematics. For service businesses, include client contracts, testimonials, or case studies. Large businesses may include organizational charts, market research reports, or audited financial statements.

    When structuring the appendix, organize it with clear tabs or sections. Refer to each appendix item in the main text (e.g., “See Appendix A for detailed financial projections”). This keeps the main narrative clean while providing depth for interested readers. Remember that investors and lenders may not read the appendix in detail, but its presence signals thoroughness.

    For small businesses, the appendix can be simpler—include resumes of key team members, letters of intent from customers, or lease agreements. The goal is to provide evidence that your plan is grounded in reality. Avoid including irrelevant documents; each item should serve a purpose. A well-organized appendix can be the deciding factor in a funding decision.

    Executive Summary Revisited: Crafting a Hook

    While we covered the executive summary earlier, it deserves deeper analysis because it is the most read section. The structure of your executive summary should follow a logical flow: hook, problem, solution, market, traction, team, and ask. The hook is a compelling statement that grabs attention. for instance, “Our software reduces energy costs by 30% for commercial buildings.”

    For product businesses, the hook might highlight a unique feature or innovation. For service businesses, it could be a client success story. Use specific numbers and avoid hype. The problem section should clearly define the pain point your business addresses. The solution should be concise and explain how your product or service solves it.

    The market section should include total addressable market (TAM), serviceable available market (SAM), and serviceable obtainable market (SOM). Traction shows any early sales, partnerships, or user growth. The team section highlights your expertise and why you are the right people to execute. Finally, the ask states how much funding you need and what you will achieve with it. Keep the executive summary to one page if possible.

    Risk Analysis and Mitigation

    Every business plan should include a risk analysis section to demonstrate that you have considered potential challenges. The structure should list major risks (market, operational, financial, regulatory) and for each, describe the likelihood and impact. Then, provide mitigation strategies. For product businesses, risks may include supply chain disruptions or product defects. For service businesses, risks may include client concentration or key person dependency.

    Use a table to present risks and mitigations clearly. for instance:

    Risk Likelihood Impact Mitigation
    Supply chain delay Medium High Dual sourcing suppliers
    Loss of key employee Low High Cross-training, retention bonuses

    Large businesses may have more complex risks, such as currency fluctuations or geopolitical issues. Small businesses should focus on risks that are most relevant to their stage. Being honest about risks shows maturity and builds trust with investors. Avoid downplaying risks; instead, show that you have a plan to manage them.

    Exit Strategy

    While not always required, including an exit strategy can be important for investors. The structure should outline potential exit options, such as acquisition, initial public offering (IPO), or management buyout. For product businesses, acquisition by a larger company in the same industry is common. For service businesses, a merger or sale to a private equity firm might be more likely.

    Provide a timeline and expected valuation based on industry multiples. for instance, if similar companies have sold for 5-10 times EBITDA, mention that. Small businesses may not need a detailed exit strategy, but for venture-backed startups, it is essential. Investors want to know how they will get a return on their investment.

    Even if you plan to run the business indefinitely, you can mention that you will consider strategic opportunities. The key is to show that you have thought about the long-term value creation. A well-defined exit strategy can make your business plan more attractive to investors.

    Business Plan for Different Audiences

    The structure of your business plan should be tailored to your audience. For banks and traditional lenders, emphasize cash flow, collateral, and repayment ability. Include detailed financial statements and a clear use of funds. For venture capitalists, focus on market opportunity, scalability, and the team. Use a leaner structure with a strong executive summary and traction metrics.

    For angel investors, highlight the personal connection and your passion. They often invest in people first. For strategic partners, emphasize synergies and mutual benefits. For internal use, a lean plan with key milestones and budgets is sufficient. Always research your audience before writing.

    for instance, a product business seeking a bank loan might structure the plan with a heavy emphasis on assets and inventory. A service business seeking venture capital might focus on customer acquisition cost and lifetime value. Adapting your structure shows that you understand your audience’s priorities.

    Review and Revision Process

    Writing a business plan is an iterative process. After drafting, review the structure for consistency and flow. Ensure that each section logically leads to the next. Check that financial projections align with the narrative. for instance, if you claim a 20% market share in the marketing section, the financials should support that growth.

    Get feedback from multiple sources: mentors, industry experts, and potential investors. Ask them to focus on the structure—is it easy to follow? Are there gaps? Use their input to revise. Small businesses may benefit from free resources like SCORE mentors. Large businesses may hire professional business plan writers.

    Finally, proofread for grammar and formatting errors. A polished plan reflects professionalism. Use consistent fonts, headings, and spacing. Include page numbers and a table of contents for longer plans. The revision process can take several weeks, but it is worth the effort. A well-structured business plan is a powerful tool.

    Conclusion: Final Thoughts on Structure

    Choosing the right business plan structure isn’t a one-time decision; it evolves with your business. As you grow, you may need to update your plan for new funding rounds or strategic shifts. The key is to remain flexible and audience-focused. Whether you use a traditional, lean, or one-page structure, ensure that it communicates your value proposition clearly.

    Remember that the structure of a business plan is a framework, not a cage. Feel free to reorder sections if it makes sense for your story. for instance, if your team is your strongest asset, put that section earlier. The goal is to engage the reader and persuade them to act.

    We have covered approaches to writing a business plan, business plan templates, small vs large business plans, product and service business plans, and provided business plan examples. By applying these insights, you can create a plan that stands out. Now, take the next step: start writing, get feedback, and refine. Your business deserves a plan that reflects its potential.

  • How to Pitch Your Business Plan to Banks and Investors: A Comprehensive Guide

    How to Pitch Your Business Plan to Banks and Investors: A Comprehensive Guide

    Introduction

    Pitching your business plan to banks and investors is a critical skill for any entrepreneur seeking funding. Whether you’re approaching a traditional bank for a loan or presenting to venture capitalists, your ability to communicate your vision, financial projections, and market opportunity can make or break your funding success. This guide provides a deep dive into the nuances of pitching to different business plan stakeholders, including how to tailor your approach when sharing a business plan with lenders versus equity investors. You’ll learn the essential components of a bank loan business plan, strategies for pitching to investors, and actionable business pitch tips to deliver a professional business presentation. By understanding your stakeholder audience, you can craft a compelling narrative that addresses their specific concerns and motivations.

    Understanding Your Stakeholder Audience

    Before you even begin crafting your pitch, you must understand who you are presenting to. Banks and investors have fundamentally different goals, risk tolerances, and decision-making criteria. A one-size-fits-all approach will fail. Instead, you need to segment your stakeholder audience and tailor your message accordingly.

    Banks: The Risk-Averse Lenders

    Banks are primarily concerned with repayment. They want to see a clear path to generating enough cash flow to cover loan payments, plus interest. Their focus is on collateral, credit history, and financial stability. When sharing a business plan with a bank, emphasize:

    • Cash flow projections showing consistent positive cash flow.
    • Collateral you can pledge (real estate, equipment, inventory).
    • Personal guarantees from founders.
    • Debt service coverage ratio (DSCR) above 1.25.
    • Historical financial statements (if existing business).
    • Use of funds – specific, tangible assets.

    Angel Investors: The High-Risk, High-Reward Backers

    Angel investors are typically wealthy individuals who invest their own money in early-stage startups. They are willing to take on more risk in exchange for potentially high returns. They often invest in the founder as much as the idea. When pitching to investors in this category, focus on:

    • The problem you are solving and its magnitude.
    • Your unique solution and competitive advantage.
    • Market size and growth potential.
    • Traction – any early customers, revenue, or partnerships.
    • The team – their expertise and passion.
    • Exit strategy – how they will get their money back (e.g., acquisition, IPO).

    Venture Capitalists: The Institutional Growth Seekers

    Venture capitalists (VCs) manage pooled funds from limited partners and invest in high-growth startups with the potential for a massive return. They are more formal and data-driven than angels. When pitching to investors like VCs, emphasize:

    • Scalability – can the business grow exponentially?
    • Large addressable market (TAM, SAM, SOM).
    • Business model – unit economics, customer acquisition cost (CAC), lifetime value (LTV).
    • Competitive landscape and defensibility.
    • Financial projections with clear assumptions.
    • Use of funds – how the investment will fuel growth.

    Key Components of a Bank Loan Business Plan

    A bank loan business plan must be conservative, detailed, and focused on risk mitigation. Banks aren’t looking for hockey-stick growth; they want steady, predictable cash flow. Here are the essential sections:

    Executive Summary

    This is the most important page. It must succinctly summarize your business, the loan request, and how you will repay. Include:

    • Business name, location, and legal structure.
    • Amount of loan requested and purpose.
    • Repayment term and source of repayment.
    • Brief overview of business history and management.

    Company Description

    Provide a clear description of your business, its mission, and its legal structure. Explain the problem you solve and your target market. Include your business’s history (if any) and milestones achieved.

    Market Analysis

    Demonstrate that you understand your industry, target market, and competition. Use data to support your claims. Include:

    • Industry overview and trends.
    • Target market demographics and psychographics.
    • Competitive analysis – strengths and weaknesses of competitors.
    • Your unique selling proposition (USP).

    Organization and Management

    Detail your business’s legal structure (sole proprietorship, LLC, corporation) and ownership. Provide bios of key management team members, highlighting relevant experience. Include an organizational chart if applicable.

    Products or Services

    Describe what you sell, how it benefits customers, and what makes it unique. If you have intellectual property (patents, trademarks), mention it. Include pricing strategy and any future product development plans.

    Marketing and Sales Strategy

    Explain how you will attract and retain customers. Cover your marketing channels (online, offline, partnerships), sales process, and customer retention strategies. Include a budget for marketing activities.

    Funding Request

    Clearly state the amount of funding you need, the type of funding (loan, line of credit), and the terms you are seeking. Explain how the funds will be used (e.g., equipment purchase, inventory, working capital). Provide a detailed breakdown of costs.

    Financial Projections

    This is the heart of your bank loan business plan. Include:

    • Income statements (profit and loss) for 3-5 years.
    • Cash flow statements – monthly for the first year, quarterly thereafter.
    • Balance sheets – showing assets, liabilities, and equity.
    • Break-even analysis – when will you become profitable?
    • Key financial ratios – DSCR, current ratio, debt-to-equity.

    Be conservative in your assumptions. Banks will stress-test your numbers.

    Appendix

    Include supporting documents such as tax returns, personal financial statements, resumes, letters of reference, leases, contracts, and any other relevant materials.

    Crafting a Compelling Pitch Deck for Investors

    When pitching to investors, a pitch deck is your primary tool. It should be visually appealing, concise, and tell a compelling story. A typical pitch deck has 10-15 slides. Here’s a structure that works:

    Slide 1: Title Slide

    Company name, logo, tagline, and your name and title. Keep it clean.

    Slide 2: Problem

    Describe the problem you are solving. Use a relatable story or statistic. Make it emotional and urgent.

    Slide 3: Solution

    Present your product or service as the answer. Show how it works (screenshots, demo video link). Highlight the key benefits.

    Slide 4: Market Size

    Show the total addressable market (TAM), serviceable available market (SAM), and serviceable obtainable market (SOM). Use a visual like a pyramid or bar chart.

    Slide 5: Business Model

    Explain how you make money. Include pricing, customer acquisition cost (CAC), lifetime value (LTV), and gross margins.

    Slide 6: Traction

    Show evidence of progress: revenue, users, partnerships, press mentions. Use a timeline or graph to show growth.

    Slide 7: Marketing & Sales Strategy

    How will you reach customers? Outline your channels (social media, content marketing, sales team) and customer acquisition strategy.

    Slide 8: Competition

    Use a competitive matrix (table) to compare your features against competitors. Highlight your competitive advantages.

    Slide 9: Team

    Introduce key team members with photos, names, and relevant experience. Emphasize why your team is uniquely qualified.

    Slide 10: Financial Projections

    Show projected revenue, expenses, and profit for 3-5 years. Keep it high-level; details go in the appendix.

    Slide 11: Funding Ask

    State how much you are raising, the type of investment (equity, convertible note), and how the funds will be used (e.g., 40% product development, 30% marketing, 20% sales, 10% operations).

    Slide 12: Thank You & Contact

    End with a thank you slide and your contact information. Include a call to action (e.g., “Let’s build the future together”).

    Professional Business Presentation Tips

    Delivering a professional business presentation requires more than just good slides. Here are actionable business pitch tips to help you shine:

    Know Your Audience

    Research the background of the people you are presenting to. What have they invested in before? What are their interests? Tailor your language and examples accordingly.

    Tell a Story

    Humans are wired for stories. Structure your pitch as a narrative: the hero (your customer) faces a problem, and your product is the magic solution. Use anecdotes and emotional hooks.

    Practice, Practice, Practice

    Rehearse your pitch multiple times. Time yourself. Record yourself and watch for nervous habits. Practice in front of friends or mentors and ask for feedback.

    Keep It Concise

    Respect the time limit. If you have 10 minutes, prepare for 8. Leave time for questions. Avoid jargon and overly technical details unless the audience is technical.

    Use Visuals Wisely

    Slides should support your speech, not replace it. Use high-quality images, charts, and minimal text. Avoid reading from slides.

    Handle Q&A Confidently

    Anticipate tough questions and prepare answers. If you don’t know something, be honest and offer to follow up. Stay calm and composed.

    Show Passion and Confidence

    Your enthusiasm is contagious. Believe in your business and let that show. Maintain eye contact, use open body language, and speak clearly.

    Common Mistakes to Avoid

    Even experienced entrepreneurs make mistakes when sharing a business plan. Avoid these pitfalls:

    • Being too vague – Provide specific numbers and details.
    • Ignoring competition – Acknowledge competitors and explain your differentiation.
    • Overly optimistic projections – Be realistic; investors and banks will see through hype.
    • Poor design – Use a clean, professional template. Avoid clutter.
    • Not knowing your numbers – Memorize key financial metrics and be ready to discuss them.
    • Focusing on features instead of benefits – Explain how your product improves customers’ lives.
    • Neglecting the ask – Clearly state what you need and what you offer in return.

    Frequently Asked Questions (FAQs)

    What is the difference between a business plan for a bank and one for an investor?

    A bank loan business plan focuses on risk mitigation, cash flow, and collateral. It is conservative and emphasizes repayment ability. An investor-focused plan highlights growth potential, market opportunity, and exit strategy. Banks want to see stability; investors want to see scalability.

    How long should a pitch deck be?

    Aim for 10-15 slides. The ideal length is 10-12 slides for a 10-15 minute presentation. Keep it concise; you can provide additional details in an appendix.

    What financial documents do I need for a bank loan?

    You typically need income statements, cash flow statements, balance sheets (historical and projected), personal financial statements, tax returns, and a debt service coverage ratio calculation. Check with your specific bank for exact requirements.

    How do I handle rejection from investors?

    Rejection is part of the process. Ask for feedback, refine your pitch, and keep trying. Many successful entrepreneurs were rejected multiple times before securing funding. Use each rejection as a learning opportunity.

    Should I include a demo in my pitch?

    If your product is complex or highly innovative, a short demo (1-2 minutes) can be powerful. but, ensure it works flawlessly and doesn’t eat into your presentation time. Alternatively, include a link to a demo video in your deck.

    What is the most important slide in a pitch deck?

    While all slides are important, the problem and solution slides are critical. If you don’t clearly articulate a compelling problem and your unique solution, the rest of the pitch falls flat. Traction is also highly persuasive.

    Conclusion

    Pitching your business plan to banks and investors is both an art and a science. By understanding your stakeholder audience, you can tailor your message to address their specific needs. For banks, emphasize stability, cash flow, and collateral in your bank loan business plan. For investors, focus on growth, market opportunity, and your team’s ability to execute. When sharing a business plan, ensure it is well-structured, data-driven, and professionally presented. Use the business pitch tips outlined in this guide to deliver a professional business presentation that captivates your audience. Remember, pitching to investors is a process of continuous improvement. Learn from each experience, refine your approach, and persist. With the right preparation and mindset, you can secure the funding you need to turn your business vision into reality.
    Comparison of Bank vs. Investor Expectations
    Aspect Bank Investor
    Primary Concern Repayment ability Return on investment
    Risk Tolerance Low High
    Focus Cash flow, collateral Growth, market size
    Financial Projections Conservative Ambitious but realistic
    Decision Time Weeks to months Weeks to months
    Relationship Transactional Partnership

    “The best pitch isn’t about your product; it’s about the problem you solve and the value you create.” – Unknown

    Advanced Pitching Techniques for Different Scenarios

    Beyond the basics, mastering advanced techniques can set you apart from other entrepreneurs. These strategies are particularly useful when you have limited time, a skeptical audience, or a complex business model.

    The Elevator Pitch: 30 Seconds to Hook Them

    An elevator pitch is a concise, compelling summary of your business that you can deliver in the time it takes to ride an elevator. It should include:

    • The problem – one sentence.
    • Your solution – one sentence.
    • Your target market – one sentence.
    • Your competitive advantage – one sentence.
    • The ask – what you want from the listener (e.g., a meeting, an introduction).

    Practice your elevator pitch until it feels natural. Record yourself and refine it. A great elevator pitch can open doors to formal presentations.

    The 10-Minute Pitch: Maximizing Impact

    When you have only 10 minutes, every second counts. Structure your pitch as follows:

    • 0-2 minutes: Hook with a compelling story or statistic about the problem.
    • 2-4 minutes: Present your solution and how it works.
    • 4-6 minutes: Show market opportunity and traction.
    • 6-8 minutes: Explain your business model and financials.
    • 8-10 minutes: State your ask and close with a call to action.

    Use a timer during practice. Leave 2-3 minutes for questions. If you finish early, that’s better than going over.

    The Virtual Pitch: Engaging Remote Audiences

    With the rise of remote work, many pitches now happen via video conferencing. To succeed:

    • Test your technology – camera, microphone, screen sharing, internet connection.
    • Use a professional background – plain wall or virtual background that isn’t distracting.
    • Look at the camera – not the screen – to simulate eye contact.
    • Share your screen only when necessary; keep your face visible as much as possible.
    • Engage with questions – use chat or raise-hand features.
    • Send materials in advance – a PDF of your deck and any supporting documents.

    Financial Modeling for Pitching

    Your financial projections are the backbone of your pitch. They must be credible, well-supported, and easy to understand. Here’s how to build a robust financial model for your bank loan business plan or investor pitch.

    Key Assumptions

    List all assumptions behind your numbers, such as:

    • Customer acquisition cost (CAC) – how much to acquire one customer.
    • Customer lifetime value (LTV) – average revenue per customer over their relationship.
    • Churn rate – percentage of customers lost per period.
    • Sales growth rate – monthly or yearly.
    • Gross margin – revenue minus cost of goods sold (COGS).
    • Operating expenses – salaries, rent, marketing, etc.

    Be prepared to defend each assumption with data or industry benchmarks.

    Building the Three-Statement Model

    A complete financial model includes three interconnected statements:

    • Income Statement: Revenue, COGS, gross profit, operating expenses, net income.
    • Balance Sheet: Assets (cash, receivables, equipment), liabilities (debt, payables), equity.
    • Cash Flow Statement: Operating cash flow, investing cash flow, financing cash flow.

    Use Excel or Google Sheets. Link the statements so that changes in one automatically update the others. For a bank loan business plan, include a debt schedule showing principal and interest payments.

    Sensitivity Analysis

    Show how changes in key assumptions affect your bottom line. for instance, what if sales are 20% lower than expected? What if COGS increases by 10%? This demonstrates that you have considered risks and have contingency plans.

    Legal and Regulatory Considerations

    When sharing a business plan with external parties, you must protect your intellectual property and comply with securities laws.

    Non-Disclosure Agreements (NDAs)

    Many entrepreneurs ask investors to sign an NDA before sharing sensitive information. but, most venture capitalists and angel investors refuse to sign NDAs because they see many deals and want to avoid legal complications. Instead, share only high-level information initially and save detailed proprietary data for later stages when there is mutual interest.

    Securities Laws and Accredited Investors

    When raising equity, you must comply with securities regulations. In the U.S., most private placements are exempt from registration under Regulation D (Rule 506b or 506c). You can only accept investments from accredited investors (individuals with a net worth over $1 million or annual income over $200,000). Ensure you verify investor status and provide appropriate disclosures.

    Intellectual Property Protection

    Before pitching, ensure you have filed for patents, trademarks, or copyrights where applicable. If your business relies on trade secrets, have employees and contractors sign confidentiality agreements. In your pitch, you can mention that IP is protected without revealing the specifics.

    Building Relationships with Stakeholders

    Pitching isn’t a one-time event; it’s the start of a relationship. Nurture your connections with business plan stakeholders even after the pitch.

    Follow-Up Strategy

    Send a thank-you email within 24 hours of your pitch. Include a link to your deck and any additional information requested. If you don’t hear back within a week, send a polite follow-up. Keep the conversation going by sharing relevant news or milestones.

    Providing Updates

    Even if an investor passes initially, keep them updated on your progress. Quarterly updates with key metrics (revenue, users, partnerships) can turn a ‘no’ into a ‘yes’ later. Banks also appreciate regular financial reports if you have an existing loan.

    Leveraging Warm Introductions

    Cold emails rarely work. Instead, ask your network for introductions to investors or bankers. A warm introduction from a trusted source significantly increases your chances of getting a meeting. Attend industry events, join startup accelerators, and use LinkedIn to connect with mutual contacts.

    Case Studies: Successful Pitches

    Learning from real-world examples can provide valuable insights. Here are two anonymized case studies.

    Case Study 1: Tech Startup Secures Series A

    A SaaS company with a B2B product had strong traction (100 paying customers, $500K ARR) but needed $2M to scale. Their pitch focused on the massive market opportunity (TAM of $10B) and their unique AI-powered solution that reduced customer churn by 30%. They used a competitive matrix to show they were the only ones offering real-time analytics. The team had prior startup experience. They secured funding from a top-tier VC within three months.

    Case Study 2: Small Business Gets Bank Loan

    A family-owned restaurant wanted $150K to expand to a second location. Their bank loan business plan included detailed financials from the existing location (3 years of tax returns, profit margins of 12%), a personal guarantee from the owner, and a collateral offer of the owner’s home. They also provided a lease agreement for the new location and a contractor’s quote. The bank approved the loan in six weeks.

    Conclusion

    Pitching your business plan to banks and investors is a multifaceted process that requires preparation, adaptability, and persistence. By understanding the distinct needs of your stakeholder audience, you can tailor your approach whether you are sharing a business plan with a conservative lender or pitching to investors seeking high growth. A well-crafted bank loan business plan emphasizes stability and repayment, while an investor pitch highlights scalability and market opportunity. Use the business pitch tips in this guide to deliver a professional business presentation that resonates. Remember, every pitch is a learning opportunity. Refine your story, strengthen your financials, and build relationships. With dedication and the right strategy, you can secure the funding your business needs to thrive.

    “Success isn’t final, failure isn’t fatal: it is the courage to continue that counts.” – Winston Churchill

  • Why Your Small Business Needs a Business Plan Before You Launch

    Why Your Small Business Needs a Business Plan Before You Launch

    Starting a small business is exciting. You have a great idea and passion. But without a plan, you risk failure. A business plan is your roadmap. It guides every decision you make. This article explains why you need one before launching. We will cover the purpose of a business plan, business planning for beginners, steps in business plan preparation, effective business plan features, how to start a business plan, small business strategy, and the business creation cycle. By the end, you will see why planning is non-negotiable.

    What Is a Business Plan and Why Does It Matter?

    A business plan is a written document. It describes your business goals and how to achieve them. It covers your products, market, and finances. Think of it as a blueprint. Just like a house needs blueprints, your business needs a plan. It helps you stay focused and organized. It also attracts investors and lenders. Without a plan, you are flying blind. Many startups fail because they skip this step. A good plan reduces risks and increases chances of success.

    The Core Purpose of a Business Plan

    The purpose of a business plan is to clarify your vision. It forces you to think through every aspect. You must define your target market. You must analyze competitors. You must project financials. This process reveals weaknesses early. You can fix them before launch. A plan also sets milestones. You know what to do each month. It keeps you accountable. for instance, if you plan to sell 100 units in month one, you can track progress. If you fall short, you adjust. Without a plan, you might not notice problems until it’s too late.

    Why Beginners Must Start with a Plan

    Business planning for beginners can feel overwhelming. But it is the best way to learn. You research your industry. You understand your customers. You learn about costs and pricing. This knowledge is priceless. Many beginners skip planning because they think it’s too hard. They jump straight into selling. Then they run into cash flow problems. They realize they priced too low. Or they discover no one wants their product. A plan prevents these mistakes. It is a safe space to test ideas. You can change your plan without losing money. So start with a simple plan. You can refine it later.

    Steps in Business Plan Preparation: A Beginner’s Guide

    Knowing the steps in business plan preparation makes it easier. Follow these steps to create a solid plan. Each step builds on the last. Take your time. Research thoroughly. Your plan will be your guide for years.

    Step 1: Executive Summary

    This is a snapshot of your business. It includes your mission, product, and goals. Write it last, but place it first. Keep it to one page. Investors read this first. Make it compelling. for instance, “We offer eco-friendly cleaning products for busy families. Our goal is to reach $100k in sales in year one.” This summary hooks the reader.

    Step 2: Company Description

    Describe your business in detail. What problem do you solve? Who are your customers? What is your unique value? For instance, if you run a bakery, you might say, “We provide gluten-free pastries for health-conscious individuals. Our recipes are unique and delicious.” This section sets the stage.

    Step 3: Market Analysis

    Research your industry and competitors. Use data to support your claims. Show that there is demand for your product. Identify your target market size. for instance, “The gluten-free market grows 10% annually. Our target customers are women aged 25-45 who live in urban areas.” This proves you know your market.

    Step 4: Organization and Management

    Explain your business structure. Are you a sole proprietor or LLC? Who is on your team? List key roles and their experience. Investors want to see a capable team. for instance, “Our head baker has 10 years of experience. Our marketing manager has a degree in business.” This builds credibility.

    Step 5: Products or Services

    Describe what you sell. Focus on benefits, not features. How does it help customers? Include pricing strategy. for instance, “Our gluten-free bread costs $6 per loaf. It is made with organic ingredients. Customers enjoy great taste without gluten.” This shows value.

    Step 6: Marketing and Sales Strategy

    How will you attract customers? Use online ads, social media, or partnerships. Explain your sales process. for instance, “We will use Instagram ads targeting gluten-free groups. Customers can order online or visit our store.” This shows you have a plan to reach customers.

    Step 7: Funding Request

    If you need funding, specify how much and why. Break down costs: equipment, inventory, marketing. for instance, “We need $50,000 for kitchen equipment and initial inventory. We will use $10,000 for marketing.” This shows you have thought about finances.

    Step 8: Financial Projections

    Forecast revenue and expenses for 3-5 years. Include profit and loss, cash flow, and balance sheet. Use realistic assumptions. for instance, “We expect $100k in sales year one, with 20% profit margin.” This proves your business is viable.

    Step 9: Appendix

    Include supporting documents. Resumes, permits, patents, or product photos. This adds depth to your plan.

    Effective Business Plan Features That Make It Stand Out

    Not all business plans are equal. Effective business plan features include clarity, realism, and focus. A good plan is easy to read. It uses simple language. It avoids jargon. It includes data and evidence. It is realistic about risks. It shows you have thought about challenges. It also has a clear call to action. For investors, the plan should answer: Why should I invest? For yourself, it should answer: What do I do next?

    Clarity and Conciseness

    Use short sentences and bullet points. Break up text with headings. Use tables for financial data. for instance, a table comparing your product to competitors is effective. It shows you understand the market. Keep each section focused. Avoid rambling. Readers should quickly grasp your idea.

    Comparison of Business Plan Features
    Feature Effective Ineffective
    Length 15-25 pages Over 50 pages
    Language Simple, clear Jargon-filled
    Data Realistic projections Overly optimistic
    Focus Customer-centric Product-centric

    Realistic Financial Projections

    Investors see many plans. They know when numbers are fake. Be conservative. Show best-case and worst-case scenarios. for instance, if you project $100k sales, explain how. Show your assumptions: price, units sold, conversion rates. This builds trust. Also, include a break-even analysis. When will you start making profit? This shows you understand cash flow.

    Focus on the Customer

    Your plan should show deep customer understanding. Use personas. for instance, “Busy Mom Maria wants healthy snacks for her kids. She shops online and values convenience.” Then explain how your product meets her needs. This makes your plan relatable. It shows you aren’t just selling a product; you are solving a problem.

    How to Start a Business Plan: Practical Tips

    If you are wondering how to start a business plan, begin with research. Talk to potential customers. Read industry reports. Look at competitor websites. Then outline your plan. Use a template if needed. Many free templates are online. Start with the executive summary, but write it last. Begin with the market analysis. It is easier because it is research-based. Then move to products and marketing. Finally, do financials. Set aside time each day. Even 30 minutes helps. don’t aim for perfection. Your first draft will be rough. Revise it later.

    Use a Template

    Templates guide you. They have sections and prompts. You fill in the blanks. This saves time. But customize it. don’t copy-paste. Your plan must reflect your unique business. for instance, if you are a service business, focus on client acquisition. If you are a product business, focus on manufacturing and distribution. Templates are starting points, not final products.

    Get Feedback

    Share your draft with mentors or peers. Ask for honest criticism. They might spot gaps. for instance, a mentor might say, “Your marketing plan is too vague.” Then you can improve. Feedback makes your plan stronger. It also prepares you for investor questions. Practice explaining your plan out loud. This builds confidence.

    Small Business Strategy: How a Plan Fits In

    Your business plan is the foundation of your small business strategy. It defines your goals and how to achieve them. Strategy is about making choices. What market to enter? How to compete? What resources to use? Your plan answers these. It aligns your team. It helps you prioritize. for instance, if your strategy is low cost, your plan shows how you will reduce expenses. If your strategy is differentiation, your plan shows unique features. Without a plan, strategy is just talk. With a plan, strategy becomes action.

    Aligning Goals with Actions

    Your plan breaks down big goals into small steps. for instance, goal: reach $100k sales. Action steps: launch website, run ads, attend trade shows. Each step has a deadline. This makes strategy tangible. You can track progress. If you fall behind, you adjust. This is the essence of strategic management. Your plan is a living document. Update it quarterly. Markets change. Your strategy must adapt.

    Risk Management

    A good plan identifies risks. What if a competitor lowers prices? What if supplier costs rise? Your plan should have contingency plans. for instance, if costs rise, you might switch suppliers or raise prices. This shows you are prepared. Investors appreciate this. It shows you aren’t naive. Risk management is a key part of small business strategy. It protects your business from surprises.

    The Business Creation Cycle: From Idea to Launch

    The business creation cycle includes ideation, planning, launching, and growth. Planning is the second phase. It is crucial. Many entrepreneurs rush from idea to launch. They skip planning. Then they struggle. The cycle works best when you spend time planning. It saves time later. for instance, if you plan your marketing, you avoid wasting money on ineffective ads. If you plan your finances, you avoid cash flow crises. Planning is an investment that pays off.

    Ideation Phase

    You have a business idea. You think it is great. But is it viable? During planning, you test your idea. You do market research. You talk to customers. You might discover flaws. for instance, you want to open a coffee shop. Research shows the area has too many coffee shops. You might pivot to a tea shop. Planning saves you from a bad investment. It is better to fail on paper than in real life.

    Launch Phase

    With a plan, launch is smoother. You have a timeline. You know what to do first. You have funding secured. You have marketing materials ready. You can focus on execution. Without a plan, launch is chaotic. You might forget important steps. for instance, you might forget to register your business name. Or you might run out of inventory. A plan prevents these issues. It gives you confidence.

    Growth Phase

    After launch, you use your plan to grow. You track metrics. You compare actuals to projections. You adjust strategy. for instance, if sales are lower than expected, you increase marketing. If costs are higher, you find savings. Your plan is a benchmark. It helps you make data-driven decisions. This is how successful businesses scale. They plan, execute, and adjust.

    Common Mistakes in Business Planning

    Even with good intentions, beginners make mistakes. Avoid these common errors. First, being too optimistic. Overestimate costs and underestimate time. Second, ignoring competition. Assume you have no competitors. Third, skipping financials. They are the hardest part, but essential. Fourth, writing for yourself, not for investors. If seeking funding, focus on ROI. Fifth, not updating the plan. A static plan is useless. Review and revise regularly.

    Overoptimism

    Many entrepreneurs think they will succeed quickly. They project high sales and low costs. In reality, most businesses take time to profit. Be realistic. Use industry benchmarks. for instance, a new restaurant might take 6 months to break even. Plan for that. If you are too optimistic, you might run out of cash. Then you close. Realism is a virtue in planning.

    Ignoring Competition

    Every business has competitors. Even if you are unique, there are substitutes. Acknowledge them. Show how you are different. for instance, if you sell handmade soap, competitors include mass-produced soap. Your advantage is natural ingredients. But you must also consider price. If your soap costs more, explain why customers will pay. Ignoring competition makes you look naive.

    How to Use Your Business Plan After Launch

    Your business plan isn’t just for starting. Use it as a management tool. Review it monthly. Compare actual results to projections. Identify variances. for instance, if your revenue is 10% below plan, investigate why. Maybe your marketing isn’t working. Then adjust. Also, use it for strategic decisions. Should you expand? Should you add a new product? Your plan helps you evaluate. It keeps you focused on your core strategy.

    Performance Tracking

    Create a dashboard with key metrics. Revenue, expenses, customer acquisition cost, etc. Compare to plan. If metrics are off, take corrective action. This is how you stay on track. for instance, if customer acquisition cost is too high, try cheaper marketing channels. Your plan gives you targets. Without targets, you can’t measure success.

    Adapting to Change

    Markets change. Your plan should too. If a new competitor emerges, update your competitive analysis. If customer preferences shift, adjust your product. A plan is a living document. It evolves with your business. don’t be afraid to change it. The goal isn’t to stick to the plan blindly. The goal is to use the plan to make better decisions.

    Real-Life Examples of Business Plans in Action

    Let’s look at two examples. One business used a plan and succeeded. Another skipped planning and failed.

    Success Story: Sarah’s Bakery

    Sarah wanted to open a gluten-free bakery. She wrote a detailed business plan. She researched the market. She found that many people wanted gluten-free options. She projected costs and revenue. She got a small loan. She launched with a clear marketing strategy. Within a year, she was profitable. She used her plan to guide decisions. When a competitor opened nearby, she adjusted her marketing. She survived and thrived. Her plan was her roadmap.

    Failure Story: Tom’s Tech Startup

    Tom had a great app idea. He skipped planning. He thought it was a waste of time. He built the app quickly. He spent all his savings. He launched without marketing. No one downloaded the app. He ran out of money. He closed after six months. He later said, “I wish I had written a business plan. I would have seen that my target market was too small.” Tom’s story is common. Planning could have saved him.

    Tools and Resources for Business Planning

    Many tools can help you create a business plan. Use online software like LivePlan or Enloop. They have templates and financial calculators. Also, use free resources from the Small Business Administration (SBA). They offer guides and workshops. Books like “The Lean Startup” by Eric Ries provide modern planning methods. Also, consider hiring a mentor from SCORE. They are experienced business owners who volunteer to help. Use these resources to make planning easier.

    Software Options

    LivePlan is popular. It guides you step by step. It has financial forecasting tools. It also allows collaboration. Enloop is another option. It automatically generates financial statements. Both have free trials. Try them to see which fits. Also, use Excel for financials if you prefer. The key is to start. don’t let perfectionism delay you.

    Free Templates

    The SBA website has free templates. They are simple and effective. Also, Bplans.com has hundreds of sample plans. You can see how others wrote theirs. Use them as inspiration. But remember, your plan must be original. don’t copy. Adapt to your business.

    The Psychological Benefits of Writing a Business Plan

    Writing a plan also helps you mentally. It reduces anxiety. You feel more in control. You have a clear path. It builds confidence. When you face challenges, you remember your plan. You know you have thought about this. It also helps you communicate your vision to others. Your team will understand the mission. This alignment is powerful. A plan turns your dream into a concrete goal. It makes it real.

    Clarity and Focus

    When you write, you clarify your thoughts. You might realize your idea isn’t as good as you thought. That is okay. Better to know now. Or you might discover new opportunities. Writing forces you to think deeply. This clarity is invaluable. It helps you focus on what matters. You stop wasting time on irrelevant activities.

    Motivation and Commitment

    Writing a plan is a commitment. You are telling yourself and others that you are serious. This motivates you to follow through. You have a document to hold yourself accountable. When you feel like giving up, you read your plan. It reminds you why you started. This emotional boost can keep you going during tough times.

    Frequently Asked Questions (FAQs)

    What is the purpose of a business plan?

    The purpose of a business plan is to outline your business goals and the strategy to achieve them. It helps you secure funding, guide operations, and measure progress. It also forces you to research your market and finances, reducing risk.

    How long should a business plan be?

    A typical business plan is 15-25 pages. but, a lean startup plan can be as short as 1-2 pages. The length depends on your audience. Investors expect more detail. For internal use, a shorter plan may suffice.

    What are the key steps in business plan preparation?

    The key steps include: executive summary, company description, market analysis, organization, products, marketing, funding request, financial projections, and appendix. Each section builds on the previous one.

    What are effective business plan features?

    Effective features include clarity, realistic financials, customer focus, and a clear value proposition. Use data and evidence. Keep it concise. Avoid jargon. Make it easy to read with headings and bullet points.

    How do I start a business plan if I have no experience?

    Start with research. Talk to potential customers. Use free templates from the SBA or Bplans.com. Write one section at a time. Begin with market analysis. Get feedback from mentors. Revise as you learn.

    How does a business plan fit into small business strategy?

    A business plan is the foundation of your strategy. It defines your goals, target market, and competitive advantage. It translates strategy into actionable steps. It also helps you track progress and adapt to changes.

    What is the business creation cycle?

    The business creation cycle includes ideation, planning, launching, and growth. Planning is the critical phase where you test your idea and prepare for launch. Skipping planning leads to higher failure rates.

    Can I write a business plan after launching?

    Yes, but it is better to write it before. If you have already launched, write a plan to guide future growth. It can help you identify problems and opportunities. It is never too late to plan.

    How often should I update my business plan?

    Update your plan at least annually. but, review it quarterly. If your market changes significantly, update sooner. A living plan is more useful than a static one.

    Do I need a business plan if I am not seeking funding?

    Yes, even if you self-fund, a plan helps you stay organized. It clarifies your goals and strategy. It reduces the risk of failure. Many successful businesses use plans even without external funding.

    Conclusion: Start Planning Today

    Your small business needs a business plan before you launch. It isn’t optional. It is essential. The purpose of a business plan is to guide you. Business planning for beginners is achievable. Follow the steps in business plan preparation. Incorporate effective business plan features. Learn how to start a business plan with templates and feedback. Use it as your small business strategy. Understand the business creation cycle. A plan saves time, money, and stress. It increases your chances of success. don’t skip this step. Start your plan today. Your future self will thank you.

    How to Write a Lean Business Plan for Speed and Agility

    Traditional business plans can be long. But many startups prefer a lean plan. A lean plan is short and focused. It covers key points quickly. You can write it in a few hours. It is perfect for testing ideas fast. The lean plan includes nine parts: problem, solution, key metrics, unique value proposition, unfair advantage, channels, customer segments, cost structure, and revenue streams. This format comes from the Lean Startup methodology. It helps you iterate quickly. You can update it as you learn. for instance, if you discover a new customer segment, you add it. Lean plans are living documents. They evolve with your business.

    The Problem and Solution

    Start by defining the problem you solve. Be specific. for instance, “Small business owners struggle to manage their finances.” Then explain your solution. “Our app automates bookkeeping.” Keep it simple. This clarity helps you focus. It also helps customers understand your value. If you can’t state the problem clearly, your idea may be weak.

    Key Metrics and Unique Value Proposition

    Identify the metrics that matter. for instance, monthly recurring revenue or customer acquisition cost. Track these to measure success. Your unique value proposition is what sets you apart. Why should customers choose you? For instance, “Our app is 50% cheaper than competitors.” This is your hook. It must be compelling and clear.

    The Role of Market Research in Business Planning

    Market research is the backbone of your plan. It provides data to support your assumptions. Without research, your plan is just guesswork. Research helps you understand customer needs. It reveals market size and trends. It also shows who your competitors are. You can use surveys, interviews, and online tools. for instance, use Google Trends to see search volume. Use social media to listen to customer conversations. This data makes your plan credible. Investors trust plans backed by research.

    Primary vs. Secondary Research

    Primary research is data you collect yourself. Surveys, interviews, and focus groups. This gives you firsthand insights. for instance, you can ask potential customers about their pain points. Secondary research uses existing data. Industry reports, government statistics, and competitor websites. Both are important. Primary research is specific to your business. Secondary research provides context. Use both to build a complete picture.

    Analyzing Competitors

    Create a competitive matrix. List your main competitors. Compare their features, pricing, and market share. Identify their strengths and weaknesses. Then show how you are different. for instance, if competitors are expensive, you can offer a low-cost alternative. If they lack customer service, you can excel at it. This analysis helps you position your business. It also reveals gaps in the market.

    Financial Projections: A Deep Dive

    Financial projections are the most intimidating part. But they are crucial. They show if your business is viable. Start with a sales forecast. Estimate how many units you will sell each month. Multiply by your price. Then estimate costs. Fixed costs like rent and salaries. Variable costs like materials. Subtract costs from sales to get profit. Do this for three years. Use realistic assumptions. for instance, assume a conservative growth rate. Also, include a break-even analysis. When will your revenue cover costs? This shows investors when they will get their money back.

    Creating a Profit and Loss Statement

    A profit and loss statement shows revenue, costs, and profit over time. Start with revenue. Then list cost of goods sold. Subtract to get gross profit. Then subtract operating expenses like marketing and rent. The result is net profit. For a new business, you may have losses initially. That is normal. But show a path to profitability. for instance, by year two, you expect to break even. Use a table to present this data clearly.

    Sample Profit and Loss Projection (Year 1)
    Month Revenue Cost of Goods Gross Profit Operating Expenses Net Profit
    Jan $5,000 $2,000 $3,000 $4,000 -$1,000
    Feb $6,000 $2,400 $3,600 $4,000 -$400
    Mar $7,000 $2,800 $4,200 $4,000 $200

    Cash Flow Management

    Cash flow is king. Many profitable businesses fail because they run out of cash. Your cash flow statement shows money coming in and going out. Include startup costs like equipment and inventory. Then show monthly inflows from sales. Outflows for expenses. If cash is negative, you need funding. Plan for a cash reserve. for instance, keep three months of expenses in the bank. This buffer protects you from surprises. Investors look for this.

    How to Present Your Business Plan to Investors

    When you present your plan, be confident and concise. Start with the problem and your solution. Use visuals like charts and tables. Show your market opportunity. Then explain your business model. How will you make money? Present your team’s experience. Finally, state your funding request. Be specific about how much you need and how you will use it. Practice your pitch. Anticipate questions. for instance, investors might ask about your competitive advantage. Have a clear answer. Your plan is your script. Use it to guide the conversation.

    Creating a Pitch Deck

    A pitch deck is a short presentation. It summarizes your business plan. Use 10-15 slides. Include slides for problem, solution, market, competition, business model, team, financials, and ask. Keep text minimal. Use images and graphs. Tell a story. for instance, start with a customer’s pain point. Then show how your product solves it. End with a call to action. Investors see many decks. Make yours memorable.

    Handling Objections

    Investors will challenge you. They might say your market is too small. Or your projections are too optimistic. Prepare responses. Use data to back your claims. for instance, if they say market is small, show research that it is growing. If they question projections, explain your assumptions. Be open to feedback. It shows you are coachable. Investors invest in people as much as ideas.

    The Importance of a Business Plan for Solo Entrepreneurs

    Even if you work alone, a plan helps. It keeps you organized. You have a roadmap. You can track your progress. It also helps you make decisions. for instance, should you spend money on ads or hire a freelancer? Your plan guides you. It also helps you stay motivated. When you feel lost, you read your plan. It reminds you of your goals. Solo entrepreneurs often wear many hats. A plan reduces overwhelm. It prioritizes tasks.

    Time Management

    A plan helps you allocate time. You know what is important. for instance, if your goal is to get 100 customers in six months, you focus on marketing. You don’t get sidetracked by minor tasks. Use your plan to create a weekly schedule. Block time for key activities. This discipline is crucial for solo success.

    Building Credibility

    When you approach partners or suppliers, a plan shows you are serious. It builds trust. for instance, if you want a supplier to extend credit, show them your financial projections. They will see you have a plan to pay. This can open doors. A plan is a sign of professionalism.

    Common Myths About Business Plans Debunked

    Many myths discourage people from writing plans. Let’s debunk them. Myth 1: Plans are only for getting funding. Truth: Plans are for you too. They guide your decisions. Myth 2: Plans are set in stone. Truth: Plans should be flexible. Update them as you learn. Myth 3: You need a perfect plan. Truth: A good enough plan is better than no plan. Myth 4: Plans are only for large businesses. Truth: Small businesses benefit most. They have less margin for error. Myth 5: You can skip planning if you have experience. Truth: Even experienced entrepreneurs plan. Markets change. Plans help you adapt.

    Myth: Plans Are Too Time-Consuming

    Yes, a detailed plan takes time. But you can start with a one-page plan. It takes a few hours. That time saves you months of mistakes. Think of it as an investment. The time you spend planning is time you save later. It is worth it.

    Myth: Plans Stifle Creativity

    Some think plans limit flexibility. Actually, plans provide a framework. Within that framework, you can be creative. You know your boundaries. for instance, if your plan says you target young professionals, you can create creative marketing for them. Without a plan, you might waste creativity on the wrong audience.

    How to Keep Your Business Plan Alive

    Many entrepreneurs write a plan and forget it. That is a mistake. Your plan should be a living document. Review it monthly. Update it when you learn something new. for instance, if you discover a new customer segment, add it. If your costs change, update financials. Use your plan in team meetings. Discuss progress against goals. This keeps everyone aligned. It also helps you celebrate wins. When you hit a milestone, acknowledge it. Then set new goals. A living plan grows with your business.

    Quarterly Reviews

    Set aside time every quarter. Review your plan. Compare actual results to projections. Identify what worked and what did not. Adjust your strategy. for instance, if a marketing channel isn’t working, reallocate budget. If a product feature is popular, emphasize it. Quarterly reviews keep you agile. They prevent small issues from becoming big problems.

    Involving Your Team

    Share your plan with employees. They should understand the vision. Ask for their input. They might have insights you missed. for instance, a salesperson might know customer objections. Incorporate that into your plan. When the team feels ownership, they work harder. A plan isn’t just the founder’s document. It is the company’s guide.

    Case Study: How a Business Plan Saved a Restaurant

    Let’s look at a real example. A couple wanted to open a restaurant. They wrote a detailed plan. They researched the local market. They found that many restaurants failed within a year. Their plan included a unique concept: farm-to-table with a fixed menu. They projected costs carefully. They secured a loan. During the first year, they faced challenges. A supplier raised prices. But because they had a plan, they had a contingency. They switched to a local farm. They also adjusted their menu to maintain margins. They survived. After three years, they expanded. Their plan was their anchor. It helped them navigate storms.

    Lessons Learned

    This case shows the value of planning. The couple did not just write a plan. They used it. They updated it. They made decisions based on it. Their plan included a risk analysis. That prepared them for supplier issues. Without a plan, they might have panicked. They might have closed. Instead, they adapted. This is the power of a business plan.

    Integrating Technology into Your Business Plan

    Modern businesses use technology. Your plan should reflect that. Include your tech stack. for instance, what software will you use for accounting, CRM, or marketing? This shows you are efficient. Also, consider how technology gives you a competitive edge. for instance, using AI for customer service. Or using data analytics for personalized marketing. Investors like tech-savvy founders. But be realistic. don’t overcomplicate. Choose tools that fit your budget.

    Digital Marketing Plan

    Your marketing plan should include digital channels. Social media, email, SEO, and paid ads. Set specific goals. for instance, gain 1,000 Instagram followers in three months. Then outline tactics. Post daily, use hashtags, collaborate with influencers. Track metrics like engagement and conversion. Digital marketing is measurable. Use data to refine your strategy. Your plan should show you understand this.

    Automation and Efficiency

    Automation saves time. Use tools to automate email sequences, social media posting, and invoicing. This reduces manual work. Your plan can highlight how you will use automation to scale. for instance, you can handle more customers without hiring more staff. This improves profitability. Investors like scalable businesses.

    The Emotional Side of Business Planning

    Writing a plan is emotional. You face your fears. You confront doubts. But it is also empowering. You realize you can control your destiny. The process builds resilience. When you write down your goals, you commit. This commitment carries you through tough times. Many successful entrepreneurs say their plan kept them going. It was their north star. Embrace the emotional journey. It is part of building a business.

    Dealing with Uncertainty

    No plan is perfect. The future is uncertain. But a plan gives you a framework to handle uncertainty. You have thought about scenarios. You have contingency plans. This reduces anxiety. You can focus on execution. Remember, a plan isn’t a prediction. It is a guide. Adjust as you go. That is okay.

    Celebrating Milestones

    When you achieve a goal in your plan, celebrate. It boosts morale. It shows progress. for instance, if you hit your first $10,000 in sales, treat your team. This positive reinforcement keeps everyone motivated. Your plan isn’t just about work. It is about achieving dreams. Enjoy the journey.

    Conclusion: Your Business Plan Is Your Best Friend

    Your small business needs a business plan before you launch. It isn’t optional. It is essential. The purpose of a business plan is to guide you. Business planning for beginners is achievable. Follow the steps in business plan preparation. Incorporate effective business plan features. Learn how to start a business plan with templates and feedback. Use it as your small business strategy. Understand the business creation cycle. A plan saves time, money, and stress. It increases your chances of success. don’t skip this step. Start your plan today. Your future self will thank you.

  • Dairy Farming in Uganda: Breeds, Feeding and Profitability

    Dairy Farming in Uganda: Breeds, Feeding and Profitability

    Dairy farming in Uganda means keeping cattle that are milked for sale or for home use, and it is one of the most practical Senior 3 Agriculture topics because its numbers are easy to compare. Uganda kept 14.5 million cattle in the 2021 national livestock census and produced about 3.7 billion litres of milk that year (UBOS, National Livestock Census Report 2021 ).

    The gap between a pure Ankole cow and a Friesian cross explains most of what a learner must understand about breeds, feeding and profit. These notes follow the NCDC syllabus and pair with the wider Senior 3 Agriculture notes hub.

    Friesian-cross dairy cow standing in a shaded zero-grazing unit on a Ugandan smallholder farm
    A dairy cow in a Ugandan zero-grazing unit, the intensive system that protects animals, concentrates manure and keeps milking close to the parlour.

    Breeds of dairy cattle used in Uganda

    Uganda’s dairy herd rests on two groups: indigenous cattle and exotic or cross-bred cattle. The NCDC Senior 3 Agriculture syllabus names seven breeds a learner must distinguish — Ankole, Sanga, Zebu, Boran, Friesian, Jersey and Guernsey. The exotic and cross-bred animals carry almost all commercial milk because they yield far more per cow.

    Indigenous cattle made up 11.2 million of Uganda’s 14.5 million cattle, or 77 percent, in 2021; exotic and cross-bred cattle made up 3.3 million, or 23 percent (UBOS, 2021). Within the indigenous herd, 78.2 percent are Zebu or Nganda and 21.8 percent Ankole long-horned, while about 90 percent of exotic cattle are kept for dairy.

    The economics of dairy farming in Uganda rest on this breed divide, because yield per cow sets the revenue side of every profit sum.

    Breed or typeGroupCharacteristics documented for Uganda
    Ankole (long-horned Sanga)IndigenousLong horns, small hump, large body, long legs; about 2.4 litres a day on Kiruhura farms.
    SangaGroup nameThe long-horned group; in Uganda the Sanga is the Ankole long-horned cow.
    East African short-horn ZebuIndigenousShort horns, large thoracic hump, small body, short legs.
    NgandaIndigenousIntermediate horns, hump and body; found in central Uganda.
    Zebu (Nkedi / Karamojong)IndigenousSmall, stocky short-horned Zebu of the north and east.
    BoranExotic (beef)Kenyan-born; listed as a beef breed in NAGRC&DB’s 2023 catalogue.
    Friesian (Holstein)Exotic (dairy)High-yielding dairy breed; crossed with Ankole to raise milk yield.
    JerseyExotic (dairy)Dairy breed; Kenyan-born bulls in NAGRC&DB’s 2023 catalogue.
    GuernseyExotic (dairy)Dairy breed; the only Uganda-bred bull (BRIGHT) in the 2023 catalogue.
    SahiwalExoticNamed on the NAGRC&DB 2023 catalogue cover with Friesian, Ayrshire and Boran.
    AyrshireExotic (dairy)Named on the NAGRC&DB 2023 catalogue cover.
    Friesian-Ankole (HF50%)Cross-bredAbout 11.2 litres a day on Kiruhura farms; the more suited cross.
    Friesian-Ankole (HF>50%)Cross-bredAbout 10.4 litres a day on Kiruhura farms.
    • Sanga and Ankole are one: The syllabus lists both, but Sanga is the group name, and in Uganda the Sanga is the Ankole long-horned cow.
    • Adaptability: Indigenous breeds are heat-tolerant, partly disease-resistant, and survive long feed and water shortages (FAO AGRI 15).
    • Why farmers keep Ankole: For cultural reasons, as a drought and disease buffer, and for income from selling live animals.
    • Crossbreeding is fast and haphazard: Land is being fenced off and Ankole crossed with Friesian to raise yields, often without a plan.
    • Guernsey is bred in Uganda: The only Uganda-bred bull in NAGRC&DB’s 2023 catalogue is the Guernsey BRIGHT.
    • Boran is beef: Boran bulls in the national catalogue are Kenyan-born and beef, so Boran is not an indigenous dairy breed.

    For how a farmer picks a good dairy animal by eye, read the companion notes on breeds and physical selection of production cattle. This topic sits inside the Senior 3 Agriculture cattle production notes pillar.

    Common mistake: writing “Ankole cattle are 50 percent of Uganda’s herd.” That is 1990s data. UBOS 2021 puts Ankole long-horned at 21.8 percent of indigenous cattle — about 2.4 million of 11.2 million.

    Feeding dairy cattle for milk yield

    Feeding is the lever that most directly controls milk yield in dairy farming in Uganda, and the evidence is dramatic. On Kiruhura farms a pure Ankole cow gave about 2.4 litres a day, a Friesian-Ankole cross (HF50%) about 11.2 litres, and a higher-grade cross 10.4 litres (Galukande et al., Tropentag 2008). The gap is feed and management, not luck. For the ration maths, see the notes on cattle nutrition and feed rations.

    Young napier grass fodder being cut in a dairy farm plot in Uganda
    Napier grass, Uganda’s main fodder grass, is richest in protein when cut young at about one metre tall.
    1. Balanced ration: A milking cow needs roughage for the rumen plus concentrate for energy and protein, never one feed alone.
    2. Roughage first: Grasses supply 5-19 percent crude protein while legumes supply 15-34 percent, so a legume mixed into grass lifts the diet’s protein (ILRI/EADD, 2012).
    3. Napier cutting height: Napier cut at 30 cm is about 9.2 percent crude protein, but over 2 m it drops to about 5.0 percent, so harvest at 1 m or every 6-8 weeks.
    4. Protein concentrates: Cottonseed cake carries about 33.0 percent crude protein and wheat bran about 17.8 percent, on a dry-matter basis (ILRI/EADD, 2012).
    5. Energy feeds: Molasses is an energy feed, not a protein feed, and works best as a carrier for urea and minerals.
    6. Local ingredients: MAAIF’s 2004 Animal Feeds Policy names maize, sorghum, cassava, sweet potatoes, cottonseed cake, soybean and fish as feed ingredients.
    7. Dairy meal standard: A basic dairy meal needs at least 15.5 percent crude protein and calf booster at least 17.5 percent (ILRI Manual 59, 2022).
    8. Calf feeding: A calf needs the richer 17.5 percent-protein booster, while a lactating cow is kept on the 15.5 percent dairy meal.
    9. Water: UBOS’s 2021 census found keepers give cattle an average of only 8.3 litres a day — survey practice, not a full requirement.
    10. Mineral lick: A zero-grazing unit includes a mineral lick box, because salt and trace minerals are part of the feeding plan.
    11. Legume supplements: Calliandra leaves carry about 26.3 percent and sesbania about 28.2 percent crude protein, so fodder trees are planted.
    12. Sweet potato vines: These supply about 19.2 percent crude protein and can be fed up to about 15 kg fresh per cow per day (ILRI/EADD, 2012).
    13. Adulteration risk: Maize bran is commonly adulterated with sawdust, husks and cassava, so check feed quality rather than trust appearance (ILRI Manual 59).
    Stage of productionMain feed needsVerified anchor
    Calf (pre-weaning)Milk plus a starter and calf booster feedCalf booster minimum 17.5% crude protein (ILRI Manual 59, 2022).
    Weaned calf / heiferGood roughage plus a legumeLegumes are 15-34% crude protein, grasses 5-19%.
    Dry cowQuality roughage plus a mineral lickA mineral lick box is a standard unit component.
    Early lactationConcentrate plus young napierNapier at 1 m is about 7.0% crude protein; over 2 m about 5.0%.
    Mid to late lactationNapier plus a legume plus branMaize bran 9.4% and cottonseed cake 33.0% crude protein.
    Milking cow (daily)Roughage plus concentrate plus waterBasic dairy meal minimum 15.5% crude protein.
    All stagesClean water every dayUBOS 2021: keepers give an average 8.3 litres a day.

    Exam tip: In a Pearson-square question you are usually balancing protein, so state every crude-protein value on the same basis — dry matter — before you calculate. Mixing “as fed” and “% DM” numbers is the commonest S3 feed error.

    Housing and milking hygiene

    Housing and milking hygiene decide whether the milk a cow produces is safe to sell, and most Ugandan dairy cattle lack even basic shelter. Only 32.5 percent of cattle-keeping households had a shelter or enclosure for their cattle in 2021 (UBOS). The standard answer is the zero-grazing unit Uganda’s National Dairy Development Project designed. Clean handling is covered in the notes on hygienic milking techniques.

    Iron-roofed zero-grazing cattle unit with a feed trough on a Ugandan farm
    A partly roofed zero-grazing unit, with a roofed sleeping area and an open walking area that slopes to drain.
    1. Zero-grazing unit: A typical unit has a sleeping area, walking area, feed, water and mineral-lick troughs, a milking area and a manure pit (NDDP/ILRI).
    2. Partly roofed: The sleeping area, milking parlour and calf pens must be roofed; the walking area need not be, so a unit is partly roofed.
    3. Roofing materials: Iron sheets or thatch (grass or makuti) are both accepted; galvanised sheets are made to Uganda Standard US EAS 11:2013.
    4. Floor choice: The sleeping area may be soft earth or concrete with bedding, while the walking area, milking place and calf pen should be concrete.
    5. Concrete ratio: Uganda’s specification mixes 1 bag cement with 2 wheelbarrows sand and 3 wheelbarrows ballast, and the floor needs two weeks to cure.
    6. Slope and grip: The walking floor slopes away from the troughs and sleeping area, and its surface is roughened so cows do not slip.
    7. Ventilation: A unit is well ventilated but protected from wind, rain and direct sunshine, which prevents coughs, colds and stress.
    8. Termite protection: All timber in the unit is treated against termites using anti-termite chemicals or old engine oil.
    9. Movable neck-pole: The sleeping pen’s length is adjusted with a movable neck-pole, so one structure fits cows of different sizes.
    10. Strip cup: The syllabus requires detecting milk abnormalities using a strip cup, so checking milk is a skill, not an option.
    11. Clean milk production: Milking techniques and clean-milk production are their own syllabus outcome, because clean handling keeps milk saleable.
    12. Dairy law: The Dairy Development Authority Act 1998 licenses milk processors, exporters, importers and collection centres and regulates dairy quality.
    13. Milking frequency: On Ugandan farms all Ankole are milked once a day, while crossbreds are milked once or twice (Tropentag 2008).

    Common mistake: quoting “a cow needs 10 square metres of barn space” in an exam. No Ugandan source verifies a per-animal floor area for cattle — the NDDP specification gives the five-cubicle unit and its adjustable neck-pole, so describe those instead.

    Common dairy cattle diseases and control

    Disease is the biggest controllable cost in dairy farming in Uganda, and ticks lead the list. East Coast fever, spread by the brown ear tick, is the most prevalent and economically important tick-borne disease, and Uganda loses over USD 1.1 billion a year to ticks and tick-borne diseases (Kasaija et al., 2021). The syllabus fixes the diseases to know: red water, heartwater, foot and mouth disease, anthrax, roundworm and ticks.

    DiseaseCause or spreadControl in Uganda
    East Coast feverProtozoan Theileria parva, spread by the brown ear tickAcaricide tick control, ECF vaccination, integrated control.
    Red water (babesiosis)Tick-borne blood parasiteAcaricide tick control.
    Heartwater (cowdriosis)Tick-borne diseaseAcaricide tick control.
    AnaplasmosisTick-borne diseaseAcaricide tick control.
    Foot and mouth diseaseVirus; direct contact, aerosols and open marketsCompulsory twice-yearly vaccination, quarantine, movement control.
    AnthraxBacterium; infected carcassesLivestock vaccination, report deaths, never eat dead cattle.
    Roundworm (gut worms)Worm eggs and larvae on pastureStrategic deworming and grazing management.
    Ticks (brown ear tick)Parasite and disease vectorAcaricides, but resistance is spreading; only 11.3% of households own a spray pump.
    BrucellosisDeclared disease (SI 38-2); also a human riskTesting, culling and careful handling.
    Lumpy skin diseaseDeclared disease (SI 38-2)Reporting and movement control under the law.
    Acaricide resistanceSelected by intensive sprayingIntegrated tick control, vaccination, resistant breeds.
    Notifiable diseasesDeclared under the Animal Diseases Act, Cap. 38Owners must report any diseased animal to the nearest veterinary officer.
    Movement-spread diseaseInfected animals moved between districtsPermits, quarantine, and no movement of live animals at night.
    • Tick control is primary: The main Ugandan method to control tick-borne diseases, especially East Coast fever, is intensive tick control with acaricides.
    • Resistance problem: Intensive acaricide pressure has selected resistant ticks, so vaccination and integrated control are also needed (Kasaija et al., 2021).
    • FMD is endemic: Uganda has been an endemic foot-and-mouth-disease country since 1953, with serotypes O, A, SAT 1 and SAT 2 recorded from 2001 to 2024.
    • Vaccination is compulsory: About 44.5 million susceptible animals are to be vaccinated twice a year against FMD, and farmers pay per animal.
    • Quarantine is district-wide: During an FMD outbreak, quarantine in Uganda covers the entire district, not just the affected farm.
    • Report every death: Under the Animal Diseases Act (Cap. 38), owners must report any diseased animal, and moving live animals at night is prohibited.
    • Deworming reinfection: A Ugandan calf study found worm egg counts rose within three weeks of deworming, because calves ingest larvae while grazing.

    Exam tip: The syllabus asks for “red water” and “heart water” as two separate words. Red water is babesiosis and heartwater is cowdriosis. Both are tick-borne, so the control answer is the same — acaricide tick control — but name both diseases separately.

    Costs and profitability of dairy farming

    Profitability in dairy farming in Uganda is the difference between what a cow earns in milk and what it costs to feed, house and protect her, and the breed choice sets the size of both numbers. A Kiruhura Ankole at about 2.4 litres a day earns far less per litre than a Friesian cross at about 11.2 litres, but the cross costs more to feed and protect.

    No published shilling price list exists, so the cost table is illustrative.

    Cost itemWhat it coversWhy it is counted
    Breeding stockBuying a heifer or cow, or semen and AI serviceThe breed choice fixes the yield ceiling.
    Feed — roughageNapier, hay, silage, pastureThe largest running cost on most dairy units.
    Feed — concentrateDairy meal, bran, cottonseed cakeNeeded to lift yield above a roughage-only level.
    MineralsMineral lick and saltPart of the balanced ration.
    WaterTrough water, especially in the dry seasonMilk is mostly water, so supply is a cost.
    HousingPoles, iron sheets or thatch, cement, sand, ballastA five-cubicle unit lists quantities, not prices.
    Veterinary careVaccines, acaricides, dewormers, vet feesDisease is the biggest preventable loss.
    LabourFeeding, milking, cleaningZero grazing has a high labour requirement.
    EquipmentSpray pump, troughs, strip cupOnly 11.3% of households own a spray pump.
    Transport and marketingMoving milk to buyers, cooling itQuality and distance change the price received.
    Record-keepingRegisters, tags, record cardsNeeded to know which cow pays for itself.
    Finance costLoan interest, e.g. the ACF at 12% fixedBorrowing for stock or housing adds a cost.
    InsuranceLivestock cover, e.g. the UAISInsures against death and disease loss.
    • Feed dominates: Feed is the biggest expense, so growing your own napier and legumes cuts the largest single cost.
    • Yield gap is the profit story: The 2.4-to-11.2 litres-a-day gap between Ankole and Friesian-cross cows is the clearest argument for careful crossbreeding.
    • Affordable credit exists: The Agricultural Credit Facility lends at up to 12 percent a year fixed, with a Block Allocation line for groups and SACCOs.
    • Insurance is subsidised: The Uganda Agricultural Insurance Scheme covers cattle, with a capped 6 percent premium and about 2.5 percent effective after subsidy.
    • Tax incentives: Animal feeds and processed milk are VAT-exempt, while seeds, fertilisers, pesticides and hoes are zero-rated (URA, FY 2025/26).
    • Record-keeping pays: Records keep input costs visible and support deductions, and the syllabus lists record-keeping as an outcome.

    Common mistake: presenting a made-up shilling price as a market fact. Uganda’s official data gives quantities and index numbers, not shilling prices per bag or per sheet, so label every budget line “illustrative” and price it from a named market and date.

    Frequently asked questions about dairy farming in Uganda

    Which dairy cattle breed gives the most milk in Uganda?

    Friesian-Ankole crosses give the most. On 18 Kiruhura farms, a pure Ankole cow gave about 2.4 litres a day, a 50 percent Friesian cross about 11.2 litres, and a higher-grade cross 10.4 litres (Galukande et al., 2008). The 50 percent cross suits the local environment best.

    How much milk does Uganda produce in a year?

    Uganda produced about 3.7 billion litres of milk in 2021, or 71.7 million litres a week, up from 667.5 million litres in 2008 — a five-fold increase (UBOS, National Livestock Census 2021). Ankole sub-region alone contributed about 1.2 billion litres.

    What do I feed a dairy cow to increase milk?

    Feed roughage such as napier cut at one metre, plus a concentrate like dairy meal and a protein source such as cottonseed cake. Napier at 30 cm is 9.2 percent crude protein but over 2 m falls to 5.0 percent, so cut young. Add clean water and a mineral lick.

    Why do dairy cows get sick from ticks?

    Ticks carry East Coast fever, the most economically important tick-borne disease in Uganda, plus red water, heartwater and anaplasmosis. Uganda loses over USD 1.1 billion a year to ticks and tick-borne diseases (Kasaija et al., 2021). Acaricides are the main control.

    Is dairy farming profitable in Uganda?

    It can be, if a farmer closes the yield gap with crossbred cows and controls feed and disease costs. Feed is the biggest expense, so growing napier and legumes helps. Credit is available at up to 12 percent a year through the Agricultural Credit Facility.

    Which syllabus topic covers dairy farming?

    Dairy farming sits in the Senior 3 Agriculture “Cattle production” topic, worth 48 periods in Term 1 of the NCDC syllabus. It covers breeds, feeding, housing, disease control and milking, with outcomes on records, strip-cup checks and clean-milk production.

    Key terms and revision summary

    Use this glossary to lock the terms, then attempt the exam-style questions that follow.

    TermMeaning
    Zero grazingKeeping cattle in a unit where feed is brought to them instead of roaming to graze.
    CrossbreedingMating two breeds, such as Ankole and Friesian, to combine hardiness and yield.
    Crude proteinA feed’s nitrogen content expressed as protein, measured on a dry-matter basis.
    RoughageBulky, fibrous feed such as napier, hay and silage that keeps the rumen working.
    ConcentrateAn energy- or protein-rich feed such as dairy meal, bran or cottonseed cake.
    Strip cupA cup used to detect milk abnormalities before and during milking.
    Notifiable diseaseA disease an owner must report to a veterinary officer under the law.
    QuarantineA restriction on moving animals and products out of an infected area.
    AcaricideA chemical applied to control ticks on cattle.

    Exam-style questions

    1. Distinguish between Ankole and Friesian cattle, and explain why farmers cross them. Outline: Ankole is indigenous, long-horned and heat-tolerant but yields about 2.4 litres a day; Friesian is an exotic dairy breed with a much higher yield. Crossbreeding gives hardiness plus higher milk — about 11.2 litres a day for a 50 percent cross.

    2. State four diseases of cattle in Uganda and one control measure for each. Outline: East Coast fever (acaricide and vaccination), foot and mouth disease (twice-yearly vaccination), anthrax (vaccination and reporting deaths), roundworm (strategic deworming).

    3. A farmer feeds napier grass cut at 2 m. Explain the effect on milk yield and how to improve it. Outline: 2 m napier is only about 5.0 percent crude protein against 9.2 percent at 30 cm, so low protein limits milk.

    Harvest at 1 m or every 6-8 weeks and add a legume.

    4. Why is record-keeping important in a dairy unit? Outline: Records track yield, feed, disease and cost, so a farmer can cull unprofitable cows and plan. It is syllabus outcome 3.1(l) and supports tax deductions.

    Get these five sections right and you can answer any Senior 3 question on dairy farming in Uganda.

  • Top Side Hustles for Students in Uganda: Earn While You Learn

    In today’s fast-paced and financially demanding world, students in Uganda are increasingly looking for side hustles to supplement their income. Whether you’re in university, vocational school, or secondary school, there are many opportunities to earn money without disrupting your education. This blog explores the best side hustles for students in Uganda, how to get started, what to avoid, and when a side hustle should evolve into your main hustle.


    🌟 Why Students in Uganda Need Side Hustles

    With rising tuition fees, accommodation costs, and day-to-day expenses, students often face financial pressure. A side hustle helps to:

    • Cover personal needs (food, transport, internet)
    • Avoid over-reliance on parents or guardians
    • Learn business and money management skills
    • Build experience and a resume before graduation

    🔥 Top Side Hustles for Students in Uganda

    Let’s look at some practical and profitable side hustles that suit students’ flexible schedules and limited capital.

    1. Freelancing (Writing, Design, and Programming)

    Keywords: freelance jobs in Uganda, online jobs for students Uganda, Upwork Uganda
    If you have a skill like graphic design, copywriting, or coding, freelancing platforms like Upwork, Fiverr, or Remotasks are goldmines.

    • Requires a laptop and internet connection
    • Learn from YouTube or Coursera
    • Pays in USD (great conversion rate!)

    🔗 Bonus: Check out Remedial Corner’s Computer & ICT content to boost your tech skills.


    2. Blogging & YouTube Content Creation

    Keywords: how to start a blog in Uganda, make money on YouTube Uganda
    Do you love writing, reviewing products, or storytelling? Blogging or vlogging can earn you money via AdSense, affiliate marketing, and brand deals.

    • Start a free blog using WordPress
    • Focus on trending topics like education, fashion, or lifestyle
    • Requires consistency but yields passive income

    3. Tutoring and Coaching

    Keywords: home tutoring jobs Uganda, online tutoring Uganda, academic coaching
    Students strong in academics can earn by helping others through:

    • Peer tutoring in your class or lower classes
    • Offering online coaching via Zoom or WhatsApp
    • Working with educational platforms like Remedial Corner or Teesas

    📘 Pro Tip: Create a mini-course on a subject you excel in and sell it.


    4. Selling Secondhand Clothes (Kampala Boutiques)

    Keywords: mitumba business Uganda, how to start a clothes business Uganda
    The mitumba business is thriving. Buy bales or select high-quality clothes from Owino Market and resell online or in hostels.

    • Start with as little as UGX 100,000
    • Use WhatsApp Status, TikTok, or Facebook Marketplace
    • High-profit margins with trendy fashion sense

    5. Phone & Computer Repairs

    Keywords: phone repair business Uganda, student tech business Uganda
    Tech-savvy students can learn basic repairs and charge for services. It’s a skill in high demand on campuses.

    • Invest in simple repair kits and online tutorials
    • Partner with gadget dealers for spare parts
    • Upsell accessories like chargers or screen protectors

    6. Dropshipping and E-commerce

    Keywords: dropshipping in Uganda, sell online Uganda, ecommerce business Uganda
    Don’t want to handle inventory? Sell products through dropshipping. Platforms like Jumia, Xente, or your own WhatsApp Business account can help.

    • Promote trending items (phone accessories, cosmetics, bags)
    • Partner with local suppliers
    • Automate deliveries via boda boda riders

    7. Social Media Management

    Keywords: social media jobs Uganda, digital marketing for students Uganda
    Businesses in Uganda are going online but lack social media skills. If you know Facebook, TikTok, or Instagram marketing, you can charge for managing pages and creating content.

    • Free tools like Canva help you design
    • Learn basic copywriting and analytics
    • Work for churches, small shops, and NGOs

    8. Photography & Videography

    Keywords: student photography business Uganda, affordable photographer Kampala
    If you own or can rent a decent camera or smartphone, you can start shooting events like birthdays, graduation parties, or campus events.

    • Charge per session or sell prints
    • Edit using mobile apps like Lightroom or CapCut
    • Offer event live streaming with tools like Facebook Live

    9. Campus Errand Services (Logistics)

    • Use a bicycle, foot, or boda-boda partnerships
    • Works best with loyal and busy student clientele
    • Expand with partnerships with stationery shops

    💼 When Does a Side Hustle Become Your Main Hustle?

    This is a critical question every serious student hustler must ask.

    ✅ Signs Your Side Hustle Is Ready to Be a Main Hustle

    1. Consistent Income: You’re earning more than your pocket money — or even your expected salary post-graduation.
    2. Growing Demand: Customers keep coming, and referrals are increasing.
    3. Scalability: You can expand by hiring others, automating, or opening a shop/office.
    4. Passion > Pressure: You wake up excited about it more than school sometimes (careful here!).
    5. Proof of Concept: You’ve tested, failed, and adjusted — and the model is working.

    🎯 Tip: Don’t rush to drop out. Combine smart planning, savings, and strategic reinvestment.


    🚫 Side Hustles to Avoid as a Student

    Not every income opportunity is worth it. Be cautious of:

    • Betting and gambling apps (high risk, poor returns)
    • Pyramid schemes / online scams (e.g. fake crypto)
    • Unlicensed forex trading without real knowledge
    • Overcommitting time and failing classes

    Stick to legal, ethical, and educationally supportive side hustles.


    🧠 Skills You Need for a Successful Side Hustle in Uganda

    Whether online or offline, success will depend on:

    • Time Management: Balance academics and work.
    • Digital Literacy: The more tech-savvy, the more options.
    • Customer Service: Politeness, communication, and consistency matter.
    • Creativity: Marketing your hustle through memes, storytelling, and TikToks is underrated.
    • Networking: Your friends, lecturers, and alumni can become your clients or mentors.

    💡 Final Thoughts: Be Smart, Not Just Busy

    Side hustles in Uganda are no longer optional—they’re a survival and empowerment tool. With the right mindset, tools, and persistence, you can earn decent income even as a student. From online jobs in Uganda to small physical businesses, opportunities are everywhere.

    However, remember that education is still your primary hustle for now. Use your side hustle to learn real-world skills, build capital, and set a solid foundation for after graduation.


    📌 Useful Resources


    If you enjoyed this guide, share it with fellow students and subscribe to our newsletter for more tips on education, finance, and digital success.

  • Rabbit Farming in Uganda: A Guide to Profitable Commercial Rabbit Farming in Africa

    Rabbit Farming in Uganda: A Guide to Profitable Commercial Rabbit Farming in Africa

    Are you looking to venture into commercial rabbit farming in Africa? Uganda is rapidly becoming a hub for innovative and profitable rabbit farms. This guide explores rabbit farming in Uganda, offering practical insights, common diseases, profitability analysis, and answers to the most searched questions about this growing industry.

    Whether you’re a beginner or a seasoned farmer, this blog will help you understand why rabbit farming is becoming one of the most profitable agribusiness ventures in Uganda and Africa at large.


    Overview of Rabbit Farming in Africa

    The rise of commercial rabbit farming in Africa is driven by the growing demand for lean, organic meat, natural fertilizers, and bio-urine-based pesticides. Countries like Kenya, Nigeria, and especially Uganda are leading the way with innovations in breeding, disease management, and income diversification.


    Rabbit Farming in Uganda: An Emerging Agribusiness Trend

    In Uganda, rabbit farming is gaining popularity due to its low start-up costs, small land requirements, and fast growth rates. On just one acre of land, a farmer can raise up to 60,000 rabbits annually, making it a scalable and highly profitable business model.

    Unlike traditional livestock, rabbits require minimal feed, reproduce quickly, and offer multiple income streams: meat, urine, and even manure.


    Common Diseases Affecting Rabbits (and How to Prevent Them)

    Healthy rabbits lead to higher profits. Below are common rabbit diseases in Uganda and how to manage them:

    1. Meng Lice, Omukuru, Emicemba

    • Symptoms: Fur peeling off skin.
    • Treatment: Disinfect non-pregnant rabbits with Evamectin. For pregnant rabbits, use copper-based acaricides such as Milbitrus and spray the walls of the hutch.

    2. Foot and Mouth Rot

    • Home remedy: Apply ghee and salt on affected areas.

    3. Infant Mortality in Rabbits

    • Causes: Cold weather, poor housing.
    • Solution: Place pots or containers in the hutch to simulate the warmth and safety of natural rabbit holes.

    4. Worm Infestation

    • Cause: Grass grown on overly fertile soils.
    • Solution: Regularly slash and clean grazing areas.

    5. Maggots from Droppings

    • Clean hutches frequently to prevent buildup of droppings which attract flies.

    6. Aggression by Male Rabbits

    • Males can kill or urinate on newborns. Always separate male rabbits from the hutch after mating.

    7. Salmonellosis

    • Common in both poultry and rabbits. Infected rabbits may appear restless and raise their ears constantly. Immediate veterinary consultation is recommended.

    Feeding and Slaughtering Guide

    • Provide a balanced diet of water and marsh grass.
    • At slaughter, expect a 50% yield: a 2 kg live rabbit will produce approximately 1 kg of meat.

    Profitability of Rabbit Farming in Uganda

    Revenue from Meat

    • One acre accommodates 30,000 rabbits, which can be raised twice a year.
    • That’s 60,000 rabbits, producing 180,000 kg of meat.
    • At UGX 15,000 per kg, annual revenue =
      UGX 2,700,000,000

    Revenue from Rabbit Urine

    • Each rabbit produces 0.2 litres of urine daily.
    • 60,000 rabbits = 12,000 litres/day
    • Over 120 maturity days, total = 1,440,000 litres/year
    • At UGX 1,000 per litre, annual revenue =
      UGX 1,440,000,000

    ✅ Total Annual Revenue: UGX 4,140,000,000

    This demonstrates the immense potential of rabbit farming as a lucrative agribusiness in Uganda.


    Frequently Asked Questions (FAQs)

    🐇 Is rabbit farming profitable in Uganda?

    Yes. A well-managed rabbit project can earn over UGX 4 billion annually from meat and urine alone. With low operational costs, quick reproduction, and small land requirements, it’s one of the most profitable farming ventures in Uganda today.

    🌿 What is the most profitable farming in Uganda?

    While crops like coffee and vanilla are lucrative, rabbit farming is emerging as one of the most profitable agribusinesses, thanks to multiple income streams (meat, urine, manure) and growing market demand.

    💰 How profitable is a rabbit farm?

    With 60,000 rabbits annually, farmers can generate up to UGX 4.14 billion from meat and urine. Profit margins improve with efficient disease control, local feed sourcing, and direct market access.

    ⚠️ What are the disadvantages of rabbit farming?

    • Sensitivity to cold and disease
    • High infant mortality if mismanaged
    • Requires frequent cleaning
    • Male aggression toward young

    Proper training and infrastructure easily overcome these challenges.

    📈 How profitable is rabbit farming?

    Extremely profitable. A small farm can scale rapidly and offers consistent returns throughout the year. Moreover, rabbit urine is a high-demand organic pesticide, adding to the income potential.


    Where is The Largest Rabbit Farm in the World: Can Uganda Compete?

    While the largest rabbit farm in the world is located in China and produces millions of rabbits annually, Uganda is quickly catching up. With improved technology, access to veterinary services, and rising local demand, Uganda has the potential to become Africa’s rabbit farming powerhouse.


    🔍 Conclusion: Why Rabbit Farming Is the Future of Agribusiness in Uganda

    In a time when land is scarce and input costs are high, rabbit farming offers a smart, scalable, and sustainable alternative. From addressing food security to creating youth employment, its benefits are unmatched.

    If you’re looking to join this agricultural revolution, now is the time to invest in rabbit farming in Uganda.


    ✅ Ready to Get Started?

    👉 Contact Remedial Corner for training, startup kits, and market access for your rabbit farming journey.

  • Taxation: Types, Importance, and Challenges in Modern Economies

    The meaning, types, and purposes of taxation. Explore how tax systems work, why they matter to governments and citizens, and key issues affecting tax compliance.


    Introduction

    Taxation is a cornerstone of every functioning society. Without taxes, governments would not have the funds to build roads, run hospitals, pay teachers, or provide public security. Yet, the topic often seems complex and misunderstood by the public.

    In this blog, we break down what taxation really is, the main types of taxes, why we pay them, and how they affect everyday life. Whether you’re a student, entrepreneur, or civil servant, understanding taxation can help you make more informed financial and civic decisions.


    What Is Taxation?

    Taxation is the system through which governments collect money from individuals, organizations, and businesses to fund public services and development. It is a mandatory contribution, enforced by law, and used for the common good of society.

    Simply put: Taxes are how citizens contribute financially to the running of their country.


    Types of Taxes

    Taxes can be grouped into two major categories:

    1. Direct Taxes

    These are paid directly to the government by individuals or organizations.

    • Income Tax: Tax on wages, salaries, and profits.
    • Corporation Tax: Tax on company profits.
    • Property Tax: Tax paid by property owners.
    • Capital Gains Tax: Paid when a person profits from selling an asset.

    2. Indirect Taxes

    These are levied on goods and services and are usually passed on to consumers.

    • Value Added Tax (VAT): A percentage added to the price of goods and services.
    • Excise Duty: Tax on specific products like alcohol, tobacco, and fuel.
    • Customs Duty: Tax on imports and exports.

    Why Do We Pay Taxes?

    Taxes serve multiple functions in society:

    1. Funding Public Services

    Government needs money for:

    • Health care
    • Education
    • Roads and infrastructure
    • Public safety (police, army, judiciary)

    2. Redistribution of Wealth

    Progressive tax systems ensure that wealthier individuals pay more, which helps reduce income inequality.

    3. Economic Stability

    Governments can raise or lower taxes to control inflation, encourage investment, or stimulate economic growth.

    4. Encouraging or Discouraging Behavior

    Taxation can be used to:

    • Discourage harmful behaviors (e.g., high taxes on cigarettes)
    • Promote savings and investments (e.g., tax incentives)

    How Taxes Are Collected

    In most countries, tax authorities are in charge of collecting taxes. In Uganda, for example, the Uganda Revenue Authority (URA) manages the tax system.

    Tax collection methods include:

    • Pay As You Earn (PAYE) for salaried workers
    • Self-assessment for businesses and freelancers
    • Withholding tax on interest or dividends
    • Electronic tax payment systems for convenience and transparency

    Taxation in Uganda and East Africa

    East African countries like Uganda, Kenya, Tanzania, and Rwanda have made significant strides in improving tax administration. Digital platforms and awareness campaigns have helped increase compliance.

    However, challenges remain:

    • High levels of informality in the economy
    • Tax evasion and avoidance
    • Limited enforcement capacity
    • Corruption and misuse of tax funds, which reduces public trust

    Efforts such as e-tax systems, mobile money tax payments, and tax education in schools aim to bridge the gap.


    Common Tax Challenges

    1. Tax Evasion

    This is illegal avoidance of taxes by underreporting income or inflating expenses. It robs the government of revenue.

    2. Tax Avoidance

    A legal use of loopholes in the tax code to reduce liabilities. Though not illegal, it’s often controversial.

    3. Lack of Awareness

    Many people do not fully understand their tax obligations, especially informal workers and small businesses.

    4. Over-Taxation

    High tax rates can discourage investment, reduce productivity, and push businesses into the informal sector.


    Benefits of a Fair and Efficient Tax System

    A good tax system should be:

    • Simple: Easy to understand and comply with.
    • Fair: Everyone pays according to their ability.
    • Transparent: People can track how their money is spent.
    • Efficient: Collection should not be costly or time-consuming.

    When managed well, taxation leads to:

    • Better public services
    • More jobs and economic growth
    • Social stability
    • Stronger national identity and civic responsibility

    The Role of Technology in Taxation

    Modern taxation relies heavily on digital tools to improve efficiency and reduce fraud.

    Some tech applications include:

    • E-filing and online payments
    • Mobile tax apps
    • AI-based risk assessment and fraud detection
    • Digital tax stamps and invoice tracking

    These innovations simplify processes and help reach more taxpayers.


    How to Stay Tax Compliant

    Here are practical steps to stay on the right side of the law:

    • Register with your national tax body (e.g., URA in Uganda)
    • Maintain good records of income, expenses, and transactions
    • File tax returns on time
    • Use professional help (like accountants) if unsure
    • Avoid cash-only transactions that can’t be tracked

    Taxation vs. Other Government Revenue Sources

    While taxation is a primary source of income, governments also earn from:

    • Natural resources (e.g., oil, minerals)
    • Donor funds and grants
    • Service fees (e.g., passport or license fees)
    • Fines and penalties

    However, reliance on taxes is more sustainable in the long run.


    Conclusion

    Taxation is more than just a financial obligation—it’s a civic duty. It connects citizens to their government and helps fund the systems that support life, business, and development. Whether direct or indirect, taxes ensure that society functions fairly and efficiently.

    However, a balanced tax system must be fair, transparent, and accountable. Citizens, in return, should remain informed, responsible, and compliant. With evolving technologies and better administration, the future of taxation looks more efficient and inclusive.


    Frequently Asked Questions (FAQs)

    1. What is the difference between direct and indirect tax?

    Direct taxes are paid straight to the government by the taxpayer (e.g., income tax), while indirect taxes are paid when purchasing goods/services (e.g., VAT).

    2. Why is taxation important for a country?

    It funds public services, reduces inequality, promotes economic growth, and allows governments to serve citizens.

    3. What happens if I don’t pay taxes?

    Failure to pay taxes can lead to fines, legal action, seizure of assets, or imprisonment depending on the law.

    4. How can small businesses in Uganda file taxes?

    They can register with URA, get a TIN (Tax Identification Number), and use the eTax portal or authorized agents to file returns.

    5. Are taxes the same in all countries?

    No. Tax systems vary by country based on policies, economic priorities, and levels of development.

    6. How do I know how much tax I owe?

    Check your income bracket and consult tax tables or use an official online calculator provided by your national tax authority.

  • Electronic Banking: Revolutionizing Financial Transactions in the Digital Age

    Explore how electronic banking is transforming the way individuals and businesses manage money. Learn about its types, benefits, challenges, and its future in a cashless world.


    Introduction

    The financial world is changing fast. With the rise of smartphones, the internet, and digital systems, banking has moved from physical counters to virtual platforms. Electronic Banking (e-banking) is no longer a luxury—it’s a necessity. Whether you’re paying bills, transferring funds, or checking your account balance, e-banking makes it all faster, easier, and more accessible.

    In this blog, we explore the definition, types, benefits, risks, and future of electronic banking. We also look at its role in Uganda and other developing countries, where it’s promoting financial inclusion and efficiency.


    What is Electronic Banking?

    Electronic Banking refers to the use of electronic means to conduct financial transactions and manage banking activities without visiting a physical branch. This includes internet banking, mobile banking, ATMs, debit/credit cards, and other digital payment systems.

    The goal is to provide customers with 24/7 access to their accounts and enable fast, secure, and convenient financial services.


    Types of Electronic Banking Services

    1. Internet Banking

    Also known as online banking, it allows customers to access their accounts through a bank’s website. Users can:

    • View account balances
    • Transfer funds
    • Pay bills
    • Apply for loans
    • Download bank statements

    2. Mobile Banking

    Banking apps or USSD codes let customers perform transactions using their mobile phones. Services include:

    • Balance inquiry
    • Airtime purchase
    • Peer-to-peer transfers
    • Merchant payments

    3. ATM (Automated Teller Machine)

    ATMs allow customers to withdraw cash, check balances, and deposit money without a bank teller.

    4. POS (Point of Sale) Transactions

    Used for card payments in shops, supermarkets, and service centers.

    5. Electronic Funds Transfer (EFT)

    This enables the transfer of money between accounts using computer systems, often for payrolls and business transactions.

    6. SMS Banking

    Customers receive text alerts for transactions and can initiate some services through SMS codes.


    Benefits of Electronic Banking

    1. Convenience

    Customers can access banking services 24/7 from anywhere, reducing the need to visit a branch.

    2. Faster Transactions

    Electronic banking significantly reduces transaction time for activities like bill payments and money transfers.

    3. Cost-Efficiency

    Banks can serve more customers at lower operational costs, and customers save money on transport and time.

    4. Improved Record-Keeping

    Electronic systems provide digital records, reducing the risk of lost receipts or manual errors.

    5. Enhanced Financial Inclusion

    Mobile banking brings financial services to remote areas where physical branches may not exist.

    6. Security Features

    With encryption, biometric verification, OTPs, and firewalls, electronic banking is increasingly secure (though not risk-free).


    Challenges and Risks of Electronic Banking

    While e-banking is convenient, it comes with a few risks and challenges:

    1. Cybersecurity Threats

    Hackers, phishing scams, and data breaches pose risks to customer information and funds.

    2. Network and System Downtime

    Transactions may fail due to poor internet connectivity or technical failures.

    3. Digital Literacy Gaps

    Not all users are tech-savvy, particularly in rural areas or among the elderly.

    4. Fraud and Identity Theft

    Fraudsters may impersonate banks or use stolen credentials to steal money.

    5. Limited Accessibility

    Not everyone has access to smartphones, internet, or power, limiting their ability to use e-banking services.


    Electronic Banking in Uganda and East Africa

    In Uganda and across East Africa, electronic banking is growing rapidly due to the popularity of mobile money and government-led digital finance initiatives.

    Mobile money platforms like MTN Mobile Money, Airtel Money, and M-Pesa have brought banking services to millions of people without a formal bank account.

    Banks such as Stanbic, Centenary, Equity, and PostBank Uganda have developed mobile apps and USSD services to support:

    • School fees payments
    • Water and electricity bill payments
    • Bulk salary transfers
    • Savings and loan management

    E-banking has enhanced transparency, reduced cash handling risks, and improved revenue collection in both public and private sectors.


    How Banks Ensure Security in E-Banking

    To address risks, banks implement strict cybersecurity protocols:

    • Two-Factor Authentication (2FA): Using a password plus an OTP (One-Time Password) or biometric data.
    • Encryption: Data is scrambled during transfer to prevent interception.
    • Firewalls: Block unauthorized access.
    • Regular Monitoring: Banks detect unusual transactions using AI systems.

    Customers are also encouraged to:

    • Avoid sharing passwords or PINs
    • Update apps regularly
    • Use strong and unique passwords
    • Verify URLs and avoid clicking suspicious links

    The Future of Electronic Banking

    The digital finance landscape is evolving rapidly with new trends such as:

    1. Open Banking

    Customers will be able to securely share their financial data with third-party apps to access better services.

    2. Blockchain and Cryptocurrencies

    Blockchain may improve security and reduce costs, while regulated crypto could offer new payment channels.

    3. Artificial Intelligence (AI)

    Chatbots, fraud detection, and personalized financial advice are already powered by AI in advanced banking systems.

    4. Digital-Only Banks

    These are banks without physical branches, offering all services online (e.g., Chipper, Kuda, and TymeBank).

    5. RegTech and SupTech

    Regulatory technologies help monitor compliance, while supervisory technologies assist regulators in ensuring safe digital banking.


    Conclusion

    Electronic banking has revolutionized the financial landscape by making banking faster, easier, and more inclusive. Whether through a mobile phone, computer, or ATM, customers can now manage their money on the go.

    Despite the risks, the benefits of e-banking—convenience, cost-savings, accessibility, and transparency—are undeniable. For developing countries like Uganda, electronic banking is not just a trend but a powerful tool for development and poverty reduction.

    Going forward, financial literacy, improved cybersecurity, and regulatory innovation will be key to maximizing the benefits of this digital revolution.


    Frequently Asked Questions (FAQs)

    1. What is the difference between e-banking and internet banking?

    Internet banking is a type of e-banking done specifically through a website or web-based platform. E-banking includes all electronic forms like ATMs, mobile banking, and online platforms.

    2. Is electronic banking safe?

    Yes, if used correctly. Banks use encryption, OTPs, and biometric verification to protect users, but customers must also take precautions.

    3. Can I open a bank account online in Uganda?

    Many banks in Uganda now offer digital account opening using national ID verification, especially for savings and mobile-linked accounts.

    4. What happens if my mobile banking transaction fails?

    You should receive a refund within 24–72 hours. Always keep transaction IDs and contact your service provider if delays occur.

    5. How do I protect myself from fraud?

    Never share your PIN or password, use strong login credentials, and avoid clicking on suspicious links or messages.

    6. What are the benefits of mobile banking over traditional banking?

    Mobile banking offers speed, convenience, 24/7 access, and saves time and transport costs compared to traditional banking.

  • The Role of Microfinance Institutions in Financial Inclusion and Poverty Reduction

    Discover how microfinance institutions are transforming lives through small loans, savings, and training. Learn about their benefits, challenges, and impact on economic development.

    Introduction

    In many developing countries, millions of people—especially women, rural communities, and small entrepreneurs—lack access to traditional banking services. Without a bank account or credit history, it’s almost impossible to secure a loan, grow a business, or even save securely. This is where Microfinance Institutions (MFIs) come in.

    Microfinance Institutions are financial organizations that provide small-scale financial services such as microloans, savings, insurance, and financial literacy training to low-income individuals or groups. These services empower people to build sustainable livelihoods, start small businesses, and improve their standard of living.

    This blog explores the nature of MFIs, their importance, types, operations, impact, and the challenges they face in promoting financial inclusion.


    What Are Microfinance Institutions?

    Microfinance Institutions are specialized financial entities focused on offering affordable financial services to underserved populations, particularly those who do not qualify for services from commercial banks. The concept of microfinance became globally recognized through the work of Dr. Muhammad Yunus and the Grameen Bank in Bangladesh, who pioneered small loans (microcredit) to poor women with remarkable success.

    MFIs aim to bridge the financial gap, enabling people at the grassroots to access credit, manage risks, and improve their income generation abilities.


    Services Offered by MFIs

    1. Microcredit: Small loans to individuals or groups to start or expand income-generating activities such as farming, tailoring, or small retail shops.
    2. Microsavings: Secure savings accounts for people with irregular incomes.
    3. Microinsurance: Insurance services covering health, life, crop failure, or business loss.
    4. Financial Training: Capacity-building in business skills, budgeting, and record-keeping.

    Types of Microfinance Institutions

    MFIs come in various forms depending on their structure, size, and area of operation:

    • Non-Governmental Organizations (NGOs): Many MFIs start as NGOs offering development aid and gradually shift to financial services.
    • Credit Unions and Savings Cooperatives: Member-based institutions promoting savings and offering small loans.
    • Microfinance Banks: Fully licensed banks specializing in serving low-income clients.
    • Rural Financial Institutions: Target rural populations and smallholder farmers.
    • Mobile and Fintech-Based MFIs: Use digital platforms to deliver services to remote areas.

    Importance of MFIs in Economic Development

    Microfinance Institutions are central to poverty reduction and financial empowerment. Their benefits include:

    1. Financial Inclusion

    MFIs bring the unbanked population into the financial system, allowing them to build financial history and access more significant financial products in the future.

    2. Poverty Alleviation

    Access to small loans helps people start small businesses, earn income, and break the cycle of poverty.

    3. Empowerment of Women

    Most microfinance clients are women. Access to finance increases their decision-making power at home and in the community.

    4. Job Creation

    Small-scale businesses funded through microfinance create employment for owners and others in the community.

    5. Social Development

    MFIs often combine financial services with literacy, health awareness, and vocational training, improving the overall well-being of communities.


    Challenges Facing Microfinance Institutions

    While MFIs have made significant strides, they face several challenges:

    1. High Operating Costs

    Serving low-income clients in remote areas is expensive due to small transaction sizes and frequent monitoring.

    2. Loan Defaults

    Clients may default due to poor business performance, natural disasters, or lack of financial discipline.

    3. Lack of Regulation

    Some MFIs operate without clear legal frameworks, leading to mismanagement or exploitation.

    4. Over-indebtedness

    Without proper coordination among MFIs, clients may borrow from multiple sources and become trapped in debt.

    5. Digital Divide

    While mobile banking can lower costs, some clients lack digital literacy or access to mobile devices.


    Microfinance in Uganda and East Africa

    In Uganda and East Africa at large, microfinance plays a critical role in promoting grassroots entrepreneurship. Institutions like Pride Microfinance, FINCA, BRAC, and Centenary Bank offer microfinance products targeting farmers, market vendors, boda-boda riders, and small traders.

    Uganda’s Tiered Financial System (Tier 1 to Tier 4 institutions) allows MFIs to operate under different levels of regulation by the Bank of Uganda, with Tier 4 Microfinance Institutions and Money Lenders Act, 2016 providing a strong legal foundation for consumer protection.


    Best Practices for Successful MFIs

    For sustainability and impact, MFIs should adopt the following strategies:

    • Conduct thorough client assessment before loan disbursement.
    • Offer financial literacy training to clients.
    • Promote group lending to encourage accountability and mutual support.
    • Use digital technologies to reduce transaction costs and improve efficiency.
    • Ensure transparent pricing and communication.

    Conclusion

    Microfinance Institutions are vital players in the quest for inclusive economic growth. By extending small-scale financial services to those traditionally excluded, they enable people to create businesses, manage financial shocks, and improve their lives.

    However, for MFIs to remain effective, they must operate transparently, adopt responsible lending practices, and embrace technology. Policymakers must also ensure strong regulatory frameworks and support innovations that strengthen the financial ecosystem.

    As the world pushes for the Sustainable Development Goals (SDGs), especially Goal 1 (No Poverty) and Goal 8 (Decent Work and Economic Growth), microfinance remains a powerful tool for change.


    Frequently Asked Questions (FAQs) on microfinance institutions in Uganda and east Africa

    1. What is the main purpose of microfinance institutions?

    Microfinance institutions aim to provide financial services like loans, savings, and insurance to low-income individuals or groups who cannot access traditional banking services.

    2. Who are the primary beneficiaries of microfinance?

    Typically, women, rural populations, small-scale traders, and informal business owners are the primary beneficiaries.

    3. How do MFIs differ from traditional banks?

    MFIs focus on small loan amounts, have more flexible repayment terms, and often provide financial education. Traditional banks serve clients with collateral and credit history.

    4. Are MFIs profitable businesses?

    Yes, many MFIs are sustainable and even profitable. However, they also prioritize social impact and poverty alleviation.

    5. Can microfinance really reduce poverty?

    When combined with training and support, microfinance can significantly improve household incomes and reduce poverty.

    6. Is group lending better than individual lending?

    Group lending encourages collective responsibility and peer monitoring, which reduces default risks. However, individual lending offers more flexibility.

  • Commercial Banks: Role and Importance in Economic Growth

    Discover the role of commercial banks in the economy, their functions, types, and how they support businesses and individuals in financial management.


    Introduction

    Commercial banks are the heart of any financial system, playing a crucial role in economic development. They provide essential services such as savings, loans, and financial transactions, helping individuals, businesses, and governments manage their money effectively.

    This blog explores:
    ✅ What commercial banks are
    ✅ Functions of commercial banks
    ✅ Types of commercial banks
    ✅ How they contribute to economic growth

    Understanding the importance of commercial banks can help individuals and businesses make better financial decisions and take advantage of banking services.


    What Are Commercial Banks?

    A commercial bank is a financial institution that accepts deposits, provides loans, and offers financial services to individuals and businesses. These banks operate with the primary aim of making a profit while supporting economic activities.

    Key Features of Commercial Banks

    ✅ Accept deposits – Customers can save and earn interest.
    ✅ Provide loans and credit – Helps businesses and individuals finance projects.
    ✅ Facilitate money transfers – Securely process financial transactions.
    ✅ Regulated by the central bank – Ensure financial stability and security.

    Example:
    In Uganda, Stanbic Bank, Centenary Bank, and Equity Bank are examples of commercial banks providing financial services to individuals and businesses.


    Functions of Commercial Banks

    Commercial banks play a critical role in economic growth by offering a wide range of financial services.

    FunctionDescriptionExample
    Accepting DepositsCustomers save money and earn interest.A farmer deposits UGX 500,000 in Centenary Bank.
    Providing Loans & CreditHelps businesses and individuals access capital.A small shop owner gets a UGX 5M loan for stock.
    Money Transfer ServicesFacilitates payments locally and internationally.A student receives school fees from a relative abroad.
    Issuing Debit & Credit CardsAllows cashless transactions.Using an ATM card to withdraw money.
    Foreign Exchange ServicesConverts currencies for international trade.Exchanging UGX to USD for import payments.
    Investment & Wealth ManagementHelps clients grow savings through investment.A bank offers stock market investment options.
    Business Advisory ServicesProvides financial guidance to companies.A startup receives advice on business expansion.

    Types of Commercial Banks

    Commercial banks vary based on their functions and ownership structures.

    1. Public Sector Banks

    • Owned and controlled by the government.
    • Provide affordable banking services to the public.
    • Example: PostBank Uganda.

    2. Private Sector Banks

    • Owned by private individuals or corporations.
    • Focus on profit-making and innovation.
    • Example: Stanbic Bank Uganda, Equity Bank.

    3. Foreign Banks

    • Operate in Uganda but are owned by international companies.
    • Provide global financial services.
    • Example: Standard Chartered Bank Uganda.

    4. Cooperative Banks

    • Owned by members who share common interests.
    • Provide loans to farmers, traders, and small businesses.
    • Example: Uganda Cooperative Savings and Credit Union.

    Importance of Commercial Banks in Economic Growth

    Commercial banks play a key role in developing economies by:

    📌 Providing Capital for Business Expansion – Loans and financial support help businesses grow.
    📌 Encouraging Savings Culture – Promotes financial security for individuals and families.
    📌 Facilitating Trade & Investments – Supports local and international businesses.
    📌 Creating Job Opportunities – Banks employ thousands and enable business growth.
    📌 Enhancing Digital Financial Services – Mobile and online banking increase accessibility.

    Example:

    In Uganda, banks such as Equity Bank and Centenary Bank offer loans to small businesses, helping entrepreneurs expand their enterprises and create jobs.


    Challenges Facing Commercial Banks

    Despite their benefits, commercial banks face several challenges, including:

    🔹 High interest rates – Making loans expensive for small businesses.
    🔹 Bank fraud and cybercrime – Digital transactions expose customers to risks.
    🔹 Limited access in rural areas – Some people lack banking services.
    🔹 Non-performing loans – Borrowers failing to repay debts affect financial stability.

    Possible Solutions:

    ✅ Lowering interest rates for small businesses.
    ✅ Strengthening digital banking security.
    ✅ Expanding financial literacy programs.

    Types of Bank Accounts in Commercial Banks

    Commercial banks offer different types of accounts to meet the financial needs of individuals, businesses, and organizations. These accounts provide various banking services, including deposits, withdrawals, savings, and credit facilities. Below are the main types of bank accounts available in commercial banks:

    1. Savings Account

    A savings account is designed for individuals who want to save money securely while earning interest. It encourages savings habits and allows limited withdrawals.

    Key Features:
    ✅ Earns interest on deposits.
    ✅ Requires a minimum balance.
    ✅ Allows limited withdrawals per month.
    ✅ Accessible through ATM, mobile banking, and online platforms.

    Best For:

    • Students, employees, and individuals looking to save money.
    • Anyone who wants secure savings with easy access.

    Example: A student saving UGX 100,000 per month for school fees.


    2. Current Account

    A current account is used for frequent transactions, making it ideal for businesses and traders. It does not earn interest but offers unlimited withdrawals and a cheque book facility.

    Key Features:
    ✅ Allows frequent deposits and withdrawals.
    ✅ Offers a cheque book and overdraft facility.
    ✅ No transaction limits.
    ✅ Suitable for high-volume transactions.

    Best For:

    • Business owners, traders, and professionals who need quick access to funds.
    • Companies that handle bulk payments and salary processing.

    Example: A retail business owner making daily deposits and withdrawals for stock purchases.


    3. Fixed Deposit Account

    A fixed deposit account (time deposit account) is designed for long-term savings with higher interest rates than a regular savings account. The money is locked in for a fixed period, such as 3 months, 6 months, or 1 year.

    Key Features:
    ✅ Higher interest rates than a savings account.
    ✅ Fixed tenure (e.g., 3, 6, or 12 months).
    ✅ Early withdrawal may attract a penalty.
    ✅ Encourages disciplined savings.

    Best For:

    • Individuals or businesses looking to grow their savings.
    • Retirees or investors seeking secure, high-return savings.

    Example: A teacher investing UGX 5,000,000 in a fixed deposit for 12 months to earn higher returns.


    4. Joint Account

    A joint account is shared between two or more people, allowing them to manage finances together. It is commonly used by married couples, business partners, or family members.

    Key Features:
    ✅ Allows multiple people to operate the account.
    ✅ Can be a savings or current account.
    ✅ Transactions require approval from all account holders.

    Best For:

    • Couples managing household expenses together.
    • Business partners sharing financial responsibilities.

    Example: A husband and wife saving for their child’s education fund using a joint account.


    5. Salary Account

    A salary account is offered by banks to employees of a company or organization. Employers deposit monthly salaries directly into the account.

    Key Features:
    ✅ No minimum balance required.
    ✅ Easy withdrawals and transfers.
    ✅ Additional benefits like loans, credit cards, and insurance.

    Best For:

    • Employees receiving a fixed monthly salary.
    • Companies managing payroll for staff.

    Example: A company in Uganda depositing salaries of 50 employees into salary accounts every month.


    6. Business Account

    A business account is designed for companies and corporations that handle large transactions daily. It offers high transaction limits, business loans, and payroll management services.

    Key Features:
    ✅ Supports bulk transactions and high withdrawals.
    ✅ Provides access to loans and overdrafts.
    ✅ Helps with tax management and payroll processing.

    Best For:

    • Medium and large businesses and corporations.
    • Importers, exporters, and traders dealing with foreign currencies.

    Example: A supermarket chain using a business account to process supplier payments.


    Choosing the right bank account is essential for managing finances efficiently. Whether you need an account for personal savings, business operations, or payroll processing, commercial banks offer various options to suit different financial needs.

    Before opening an account, consider transaction limits, interest rates, and banking fees to ensure you select the best option for your financial goals. 🚀


    Conclusion

    Commercial banks are vital for economic development, providing capital, financial services, and business support. Their role in savings, credit, and investment helps individuals and businesses grow while maintaining financial stability.

    For sustainable growth, regulations, digital banking expansion, and financial literacy programs are necessary to make banking services more inclusive and effective.


    Frequently Asked Questions (FAQs)

    1. What is the primary role of commercial banks?

    Commercial banks accept deposits, provide loans, facilitate money transfers, and support investments.

    2. How do commercial banks make money?

    They earn through interest on loans, transaction fees, and investment returns.

    3. What are the advantages of saving money in a bank?

    ✅ Security from theft
    ✅ Earn interest on savings
    ✅ Easy access to financial services

    4. How do commercial banks help small businesses?

    They offer business loans, financial advice, and money transfer services to help businesses grow.

    5. What challenges do commercial banks face?

    📌 High loan default rates
    📌 Cybersecurity threats
    📌 Limited banking access in rural areas


    💡 Final Thought: Commercial banks are essential for financial stability and economic growth. Understanding their functions and services can help individuals and businesses make informed financial decisions. 🚀

  • Money and Financial Institutions: Understanding Their Role in Economic Stability

    Learn about money and financial institutions, their importance in economic development, and how the central bank regulates monetary policies to ensure financial stability.


    Introduction

    Money and financial institutions form the backbone of any economy. They facilitate trade, regulate economic activities, and ensure stability in financial transactions. Without money, modern economies would struggle with inefficiencies like barter trade, and without financial institutions, there would be no structured system for saving, lending, or regulating monetary flow.

    This blog explores:
    ✅ What money is and its role in the economy
    ✅ The functions and types of money
    ✅ The role of financial institutions, particularly the central bank

    By the end, you’ll have a clear understanding of how money and financial institutions work together to maintain economic stability and promote growth.


    1. What is Money?

    Money is any medium of exchange that is widely accepted for the purchase of goods and services. It serves as a standard measure of value and helps in financial transactions.

    Functions of Money

    Money plays a critical role in any economy by performing the following functions:

    FunctionDescriptionExample
    Medium of ExchangeEnables trade without barterBuying food using cash or mobile money
    Unit of AccountMeasures the value of goods and servicesA car costs UGX 30,000,000
    Store of ValueMaintains value for future useSaving UGX 100,000 in a bank
    Standard of Deferred PaymentUsed for future financial obligationsPaying school fees in installments

    Types of Money

    1. Commodity Money – Money with intrinsic value (e.g., gold, silver).
    2. Fiat Money – Government-issued currency without intrinsic value (e.g., the Ugandan Shilling).
    3. Digital Money – Includes mobile money, credit cards, and cryptocurrencies.

    2. Financial Institutions and Their Importance

    Financial institutions act as intermediaries between savers and borrowers, ensuring smooth economic transactions. They provide banking services, credit facilities, and investment opportunities.

    Types of Financial Institutions

    1. Commercial Banks – Provide loans, savings accounts, and other financial services.
    2. Microfinance Institutions – Offer small-scale credit to individuals and small businesses.
    3. Cooperative Societies – Enable members to save and access affordable loans.
    4. Insurance Companies – Provide financial security against risks.
    5. Stock Markets – Allow companies to raise capital through the sale of shares.

    Financial institutions help maintain economic stability by controlling liquidity, facilitating investments, and providing credit access.


    3. The Central Bank: Regulator of Financial Systems

    What is the Central Bank?

    The Central Bank is the highest financial institution responsible for regulating and stabilizing a country’s economy. In Uganda, this role is played by the Bank of Uganda (BoU).

    Functions of the Central Bank

    The central bank is responsible for controlling inflation, managing currency supply, and regulating financial institutions.

    FunctionDescriptionExample
    Issuing CurrencyEnsures a stable money supplyPrinting Ugandan Shillings
    Controlling InflationImplements policies to stabilize pricesAdjusting interest rates
    Regulating Commercial BanksEnsures fair banking practicesLicensing banks
    Managing Foreign ReservesStabilizes exchange ratesControlling USD-UGX rates
    Setting Interest RatesInfluences borrowing and lending ratesIncreasing rates to control inflation
    Lender of Last ResortProvides emergency funds to banksBailout loans during crises

    Why is the Central Bank Important?

    📌 It ensures that inflation remains stable, preventing a rapid increase in the cost of goods.
    📌 It regulates commercial banks, ensuring fair interest rates and protecting customers.
    📌 It influences economic growth by controlling money supply and credit availability.


    4. The Relationship Between Money, Financial Institutions, and the Central Bank

    • Financial institutions facilitate the use of money by providing services like savings, loans, and investments.
    • The central bank oversees financial institutions to ensure economic stability.
    • Proper monetary policies help prevent inflation and economic crises.

    Example:

    When inflation rises in Uganda, the Bank of Uganda may increase interest rates to reduce excessive borrowing, thereby stabilizing the economy.


    5. Challenges Facing Money and Financial Institutions

    Despite their importance, money and financial institutions in Uganda face several challenges:

    🔹 Inflation – A decrease in money’s purchasing power affects savings and investments.
    🔹 Bank Fraud & Cybercrime – Digital transactions are prone to hacking and scams.
    🔹 Financial Exclusion – Some rural populations lack access to banking services.
    🔹 High Interest Rates – Borrowing money can be expensive for small businesses.

    Possible Solutions:

    ✅ Strengthening digital banking security
    ✅ Expanding financial literacy programs
    ✅ Regulating interest rates to encourage business growth


    Conclusion

    Money and financial institutions are essential for economic stability and growth. The central bank plays a key role in regulating money supply, controlling inflation, and overseeing banking operations.

    Understanding how money works and the role of financial institutions can help individuals and businesses make better financial decisions. To ensure economic success, Uganda must continue to strengthen its monetary policies, improve financial inclusion, and enhance banking security.


    Frequently Asked Questions (FAQs)

    1. What is the main function of money?

    Money serves as a medium of exchange, store of value, unit of account, and standard of deferred payment.

    2. What is the role of financial institutions?

    Financial institutions facilitate savings, provide loans, regulate transactions, and offer investment opportunities.

    3. What is the purpose of the central bank?

    The central bank controls inflation, issues currency, regulates commercial banks, and stabilizes the financial system.

    4. How does inflation affect money?

    Inflation reduces the purchasing power of money, making goods and services more expensive.

    5. How can financial institutions reduce poverty?

    Financial institutions promote economic growth by providing loans, supporting businesses, and encouraging savings.


    Final Thought:
    💡 Financial literacy is key! Understanding how money works, the role of banks, and the importance of the central bank can help individuals and businesses thrive in Uganda’s economy. 🚀

×
Listen to Remedial Radio

Listen to Remedial Radio

Enjoy the rhythm of knowledge. where books sing!
Learn More
🚀 Stuck in School? Catch Up and Stand Out!

🚀 Stuck in School? Catch Up and Stand Out!

Don't let difficult topics hold you back. Our fast-track Remedial Courses are designed to bridge the gap and boost your confidence instantly.

What We Offer:

  • Speak Kiswahili From Day One: Master conversational Swahili with zero stress.

  • English for Locals: Perfect your grammar and speak English with absolute confidence.

  • Targeted Remedial Support: Easily catch up on core subjects you find challenging.

Stop struggling. Start mastering.


Learn More